While you were living your life, the IRS quietly changed five rules that affect every retiree in America. No press conference, no letter, nothing announced in the media. They sat deep within legislation exceeding a thousand pages, the type of document ordinary people never touch. And the people they affect the most, retirees on a fixed income, are the ones least likely to ever hear a word about them.
Two of these changes can put thousands of dollars back in your pocket every year. One can cost you thousands when you fail to notice the threshold shifted. And each of them counts on you never catching on.
I am not a lawyer, not a CPA, not a financial advisor. All of this is for education, drawn from 2026 tax law as it currently stands and from public sources. Your circumstances are unique to you, so check with a professional before taking any action.
To make the numbers real, meet Frank and Carol. They are both 67, married, and own the house they have called home for three decades in a state where property taxes run high. They collect $48,000 a year in Social Security, Frank has a $20,000 pension, and they pull about $27,000 from their IRA. Total income: $95,000. They are not rich, not poor, just the great American middle of retirement. Watch what these five changes are worth to a couple like them, and by extension to you.
Quick Tips Before You Start
Pull Your Return
Have your most recent tax return in front of you, line by line, before you read further.
Run Both Ways
If you own a home, compare itemizing versus the standard deduction every year now, not once a decade.
Watch the Mail
A new car loan interest form is coming; do not toss it as junk.
Note the Deadlines
The senior bonus and car loan deductions are scheduled to end after 2028.
Ask Directly
Call your preparer and ask if they claimed the senior bonus deduction.
1. A New $6,000 Senior Deduction Most Miss
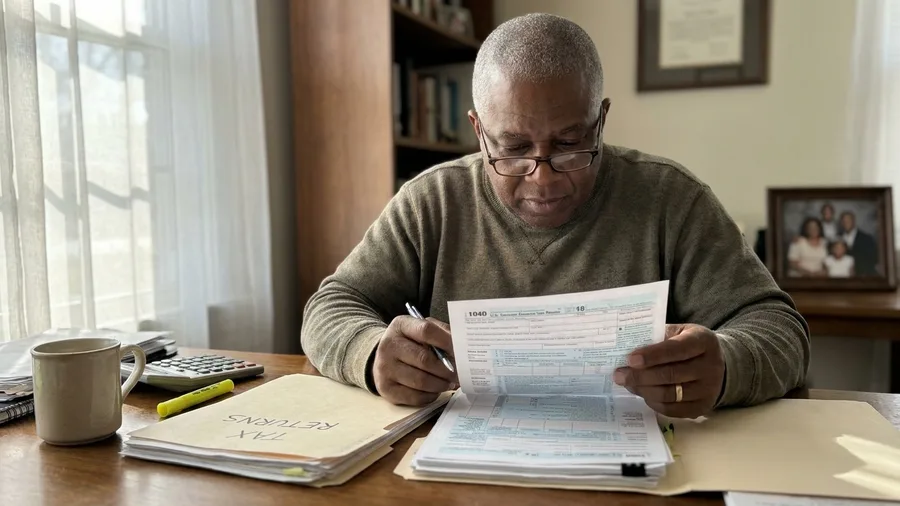
Before you write another check, go back to that first bucket of money: the new senior bonus deduction is the one most retirees never hear about, and it is the one that quietly vanishes after 2028. Starting with the 2025 tax year, it is worth $6,000 per person, so $12,000 for a couple where both of you are 65 or older.
It stacks, and that is the whole point. It sits on top of your standard deduction and on top of the extra standard deduction you already get for being over 65, so you are not choosing one over the other. Full amount below $75,000 single or $150,000 married. For a couple like Frank and Carol, that $12,000 works out to roughly $1,440 annually in genuine tax savings; a single retiree with the $6,000 figure saves around $720. But the clock is short: scheduled to disappear after 2028.
pull out your most recent return today and examine each line for the senior bonus deduction. If it is missing and you qualified, ask the preparer directly whether it was claimed, and if not, file an amended return for that year. Go back as far as the deduction existed and claim every dollar.
💡 Tip: Call your preparer and ask directly: 'Did you claim the senior bonus deduction on my return?' Do not assume.
📋 How to Check and Claim the Senior Bonus Deduction
Start with 2025
The deduction first applies to the 2025 tax year, so that return is your starting point. If you have not filed yet, claim it now. If you have, check what you sent.
Check the right line
It sits on Schedule 1-A (Form 1040), not on the standard deduction line. A blank 1040 alone does not mean it was missed.
Test the phaseout
Full amount below $75,000 single or $150,000 married. Above those, the $6,000 shrinks by 6% of excess income and reaches zero at $175,000 single / $250,000 married.
Call your preparer before amending
Ask for a copy of the filed Schedule 1-A. If it is blank, ask why in writing. One call can save you a $0 amendment and a $0 refund.
File Form 1040-X early
Use the 2025 Form 1040-X. The normal window is 3 years from filing or 2 years from paying, whichever is later. Do not wait for 2029: the deduction expires after 2028.
2. The SALT Cap Quadrupled, But Only If You Itemize
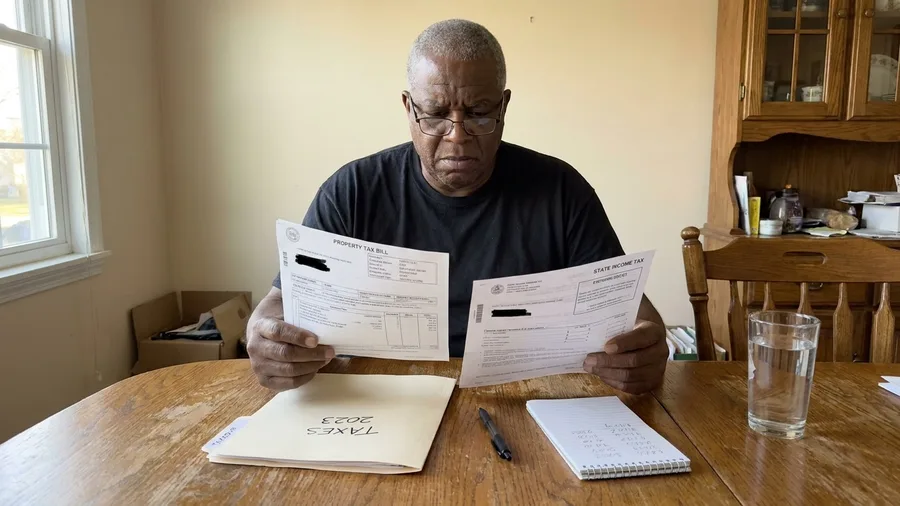
The cap on the state and local tax deduction jumped from $10,000 to $40,400 for 2026, and it keeps adjusting upward through 2029. For eight straight years the old $10,000 ceiling punished homeowners who paid far more than that in property and state income taxes, because every dollar above the cap gave them nothing. Now, for Frank and Carol with their roughly $22,000 in state and local taxes, the full amount is deductible, worth roughly $1,400 to $2,600 annually depending on their bracket.
But here is the trap inside the good news: you have to itemize. Itemizing and the standard deduction are mutually exclusive, and when the cap was slashed to $10,000 eight years ago itemizing stopped paying for millions of homeowners. They switched to the standard deduction and put it on autopilot, year after year, never questioning it. The math has flipped back, but the habit has not. In high-tax states like New Jersey, New York, California, Illinois, Massachusetts and Connecticut, some homeowners will see swings of three, four, or even five thousand dollars a year.
The fix is a three-number test you run every single year. Tally your state and local taxes, any mortgage interest you still pay, and whatever you give to charity. If that total beats your standard deduction, itemize and capture every dollar; if it does not, take the standard deduction and you have lost nothing by checking. Ask your preparer to run it both ways in front of you, and if you already filed and took the standard deduction when itemizing would have saved you more, file an amended return and recover the difference.
💡 Tip: If you own a home in a high-tax state, run the three-number test every single year from now on. Do not trust an eight-year-old habit.
⚠️ COMMON MISTAKE
The Autopilot Trap
Millions of retirees are still taking the standard deduction out of habit, even though the higher SALT cap now makes itemizing worth it for them. If you have not run both calculations this year, you are probably leaving money on the table.
3. Your State's Estate Tax Is Now the Real Threat
This one works the opposite way from the first two. It does not put cash in your pocket today, but it removes a deadline that had retirees panicking for years. For a long time the sum you could hand down to heirs free of tax was set to fall roughly in half at the end of 2025, from around $14 million per person toward $7 million. Between a paid-off home that tripled in value, a retirement account, life insurance and savings, ordinary families in expensive parts of the country were suddenly doing math and getting scared. Estate lawyers were booked solid with people rushing to set up trusts, many paying thousands in legal fees out of fear.
Then the rule changed quietly. Instead of dropping, the exemption was raised and made permanent: $15 million per individual, $30 million for couples, entirely exempt from federal estate tax, and now indexed to rise with inflation. The panic deadline is gone, which means you can plan calmly and deliberately instead of in a rush.
But here is what the headlines do not tell you. Your state may have its own estate or inheritance tax with a threshold far below the federal figure, sometimes reaching down to just one or two million dollars. That is the levy that can actually hit a normal household with a valuable home, and it is the one worth planning for now.
So the real lesson is to stop doing federal estate tax math entirely. This week, find out whether your own state has an estate or inheritance tax and exactly where its threshold sits, because that is the danger zone for your family's money, and almost nobody points that out to you.
💡 Tip: Ask your tax preparer or a local estate attorney one direct question: does this state have its own estate or inheritance tax, and at what threshold?
| Change | What changed for 2026 | Who qualifies | What it is worth | Expires |
|---|---|---|---|---|
| Senior bonus deduction | New $6,000 per person deduction | 65+ with income under $75k single / $150k married | $1,440 a year for a couple, $720 for a single | After 2028 |
| SALT cap | Raised from $10,000 to $40,400 | Homeowners who itemize | $1,400 to $2,600 a year for the example couple | Adjusts through 2029 |
| Estate tax exemption | $15 million per person, permanent | Estates under $30 million per couple | Certainty; state taxes may still apply | Permanent |
| Medicare IRMAA thresholds | $109k single / $218k married | Anyone on Medicare | Avoid surcharges of $1,100+ a year | Annual |
| Car loan interest | Up to $10,000 deductible | New US-assembled car, personal loan | Up to $10,000 in interest | After 2028 |
4. One Dollar Over the Medicare Line Costs Thousands
Picture the morning the envelope from Social Security arrives and your Medicare premium has doubled, with no explanation inside. That is this rule, and it decides how much you pay for Medicare. There is a surcharge on premiums for higher-income retirees called IRMAA, and in 2026 the first threshold rose to $109,000 for a single retiree, $218,000 for a married couple, previously $106,000.
But the mechanic underneath it is cruel, because this surcharge is a cliff, not a ramp. Earn one dollar over the line and the entire surcharge slams down at once, so a few extra dollars costs you plenty. The first tier alone runs above $1,100 annually for a single person; for a couple where both are on Medicare, over $2,000, triggered by going $1 over. One retiree took out an extra $100 from an IRA, crossed the threshold by $40, and paid over $1,000 in surcharges for it. And the income they use is not this year's. It is your income from two years ago, so a Roth conversion, property sale or large IRA withdrawal two years back spikes your premiums today. The standard Part B premium in 2026 is already $202.90 a month, up nearly 10%, before any surcharge.
Two fixes. Watch your income around those thresholds like a hawk in any year you plan a large withdrawal, and divide a big withdrawal over two calendar years so neither one crosses the line. And if your income recently dropped because you retired, file Form SSA-44, report the life-changing event, and get the surcharge recalculated on your new lower income.
💡 Tip: Before any big withdrawal, check where your income lands relative to $109,000 single or $218,000 married. Stay a comfortable margin under the cliff.
5. Car Loan Interest Counts Only for the Right Car
The interest on a new car loan is now deductible, up to $10,000 a year, and unlike the SALT change this one does not require itemizing at all. Your standard deduction stays, your senior bonus deduction stays, and this comes on top of both.
The rules are strict, though. The loan must have originated after 2024 closed, the car must be new and used for personal purposes, and its final assembly must have happened in the United States, so plenty of familiar-sounding brands built overseas will not qualify. It phases out above $100,000 single or $200,000 married and runs only through 2028. Two retirees can buy the same week, take near-identical loans, and only one gets the deduction, purely on where the car was bolted together.
Starting with the 2026 tax year, your lender must send a new form itemizing precisely what deductible interest you paid. Most people will take it for junk mail and toss it in a drawer, and with it goes a deduction worth real money. Check final assembly before you sign, watch your mailbox for that form, and if you already filed and missed it, amend the return to claim it.
💡 Tip: Check the window sticker or the VIN plate for final assembly location before you sign. US assembly is the whole game.
Which of the Five You Can Still Amend
So you filed in February, and now you are reading about a $6,000 senior deduction and wondering whether you have already lost your shot. You have not. Three of the five can still be fixed, and the fix is a form you probably have never touched.
Start with the senior bonus deduction. If you were 65 or older and under the income line, and your return did not claim it, that is a correction you can make on an amended individual return, Form 1040-X. The same form handles the itemize-versus-standard decision. Ran the standard deduction when your state and local taxes would have beaten it? That arithmetic gets redone on the 1040-X too. And the car loan interest, up to $10,000 a year on a qualifying new vehicle, is a third line you can add after the fact.
You generally have three years from the date you filed to claim a refund. Before you trust a half-remembered deadline, pull the current window from the IRS site or ask your preparer to confirm it.
The Medicare surcharge is the one that will not budge. You cannot amend a tax return to fix IRMAA. That runs through Social Security on Form SSA-44, the same agency behind the spousal top-up rule, and it only works if you have a life-changing event to document. Estate planning is not a return line at all, so there is nothing to amend there. The only move is the state tax question.
Then there is the arithmetic nobody likes. If your preparer charges more to prepare the amendment than the refund is worth, let it go. But if a preparer missed a deduction, call them first. A good one will correct their own mistake without charging you for the privilege.
What to Hand Your Preparer Before the Appointment
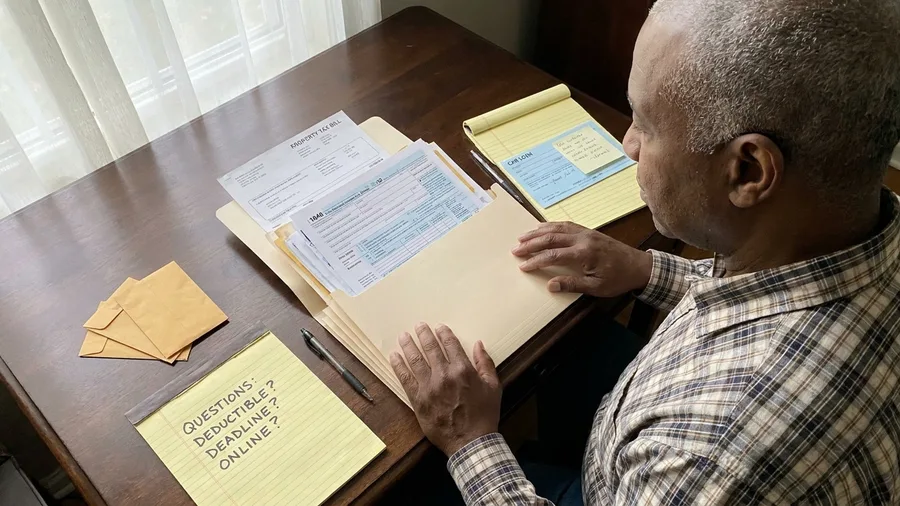
The appointment goes better when the folder is right, so here is what belongs in it. Start with last year's return, and flip it to the deduction page. You want the itemize-versus-standard number visible from the moment you sit down, because that is the single most expensive line on the whole return.
Next, the property tax bill and the state income tax statement. Those two documents are what feed that comparison, and without them your preparer is guessing at a $1,400 to $2,600 swing.
Then the car loan. Since lenders started issuing a new interest form, dig it out of the junk drawer and bring it for any 2025 or 2026 loan. Add a short note confirming where the vehicle was assembled, since US final assembly is part of the test. No note, no deduction.
The one people forget is the income history. Write down any large IRA withdrawal, Roth conversion or property sale from two years back. That is the income that sets this year's Medicare premium, and your preparer cannot see it on the current return.
Save room for one question at the end: does this state have its own estate or inheritance tax, and at what threshold? Some states start as low as $1 million or $2 million. That single answer can be worth more than everything else in the folder.
Frequently Asked Questions
Do I need to itemize to claim the senior bonus deduction?
No. The senior bonus deduction stacks on top of the standard deduction and the extra 65+ standard deduction. You get it even if you take the standard deduction.
What if I already filed and missed the senior bonus deduction?
File an amended return using Form 1040-X. You generally have three years to claim a refund, so check the current deadline on the IRS site.
How do I know if my car qualifies for the loan interest deduction?
The car must be new, for personal use, with a loan that started after 2024, and its final assembly must be in the United States. Check the window sticker or VIN plate.
Can I appeal a Medicare IRMAA surcharge?
Yes. If your income dropped due to a life-changing event like retirement, file Form SSA-44 with Social Security to have the surcharge recalculated based on your current income.
Does my state have an estate tax?
Some states do, with thresholds as low as $1–2 million. Check with your state tax authority or a local estate attorney.
The Stack of Small Changes Worth Thousands
Look at what just happened. Five rules changed quietly, buried in legislation with no real effort to inform the people they affect most. For Frank and Carol, the senior bonus deduction and the higher SALT cap alone are worth roughly $2,800 to $4,000 every single year, money that was sitting right there and would have been missed without someone pointing it out.
The system is not built to inform you. The IRS gains nothing by alerting you to a deduction you are owed, so it stays silent. Your software does only what it was programmed to do. Your preparer is buried under returns. Nobody in that chain has a job that depends on making sure you keep the most of your own money. That responsibility falls on exactly one person: you.
Here is the one move to make first. Pull last year's return and look for the senior bonus deduction line. If you own a home in a high-tax state, go straight to the itemize-versus-standard math. If you have a paid-off house and a grown family, find out this week whether your state has an estate or inheritance tax. And if you are planning a big IRA withdrawal or Roth conversion, check the Medicare lookback two years out. Do those, and you have handled every quiet change the IRS made this year.
Check Your Return Today
Pull out your most recent tax return and look for the senior bonus deduction line. If it is missing and you qualify, file an amended return.

Hello there! I’m Jesse Joe, the author and editor behind SolganGenius. I’m thrilled you’ve stopped by, and I can’t wait to share with you the essence of what this platform is all about.
I’m a writer, social media enthusiast, and a firm believer in the power of words. I’ve always been fascinated by how a simple phrase or slogan can capture an emotion, convey a message, and even change perspectives. Learn More