Ask someone when they plan to retire and you'll get an age or a year. Ask which month, and most people pause. The date got inherited from a birthday, not chosen.
That pause is where money gets left on the table. The month you stop working decides how much of your final salary, bonus, and first retirement income land on the same tax return. One date can turn a normal year into your highest-income year on record.
It also changes when you can start Social Security, how much of your benefit gets taxed, what you pay for Medicare two years later, and how many months of withdrawals your portfolio has to fund.
By the end, you'll know which systems collide in a retirement year, how an early-year exit compares with a late-year one, and how to compare two or three candidate months against your own numbers. The month is not fixed. Treat it like a lever.
| Factor | Retire January–March | Retire November–December |
|---|---|---|
| Wages on the tax return | About $30,000 plus bonus and PTO | About $120,000 plus bonus and PTO |
| Social Security taxation | Wages fall off before benefits start | Benefits stack on top of full-year wages |
| Medicare IRMAA risk | Income may stay low enough to avoid it | High income year can trigger a surcharge two years later |
| Roth conversion room | Low tax year creates cheap conversion space | High tax year makes conversions expensive |
| Portfolio withdrawals in year one | $54,000 for a March exit on $6,000 monthly spending | $6,000 for a December exit |
| Pension service credit | Working into January can earn a full year | December 31 may forfeit the year |
| Healthcare transition | Months to sort coverage before first claim | Overlapping deductibles and rushed enrollment |
The retirement year is a transition year.
Because the year you retire is the one year your working income and your retirement income share a single tax return, and the month sets how much of each side shows up.
Think about what an ordinary return looks like. Either you are working and it shows wages, or you are retired and it shows pension checks, Social Security and portfolio withdrawals. The year you stop working is the only year it shows both at once, which makes it neither a normal working year nor a normal retired year.
Now stack it up. A $120,000 salary can sit on the same return as a $15,000 bonus, an $8,000 unused-PTO payout, a first pension payment, a first Social Security check, and an initial IRA withdrawal to fund spending before benefits begin. Every one of those is perfectly ordinary on its own. Together they are a spike, and the tax code treats a spike differently than it treats a normal year.
Here is where the month earns its keep. Retire in March and only about $30,000 of wages plus the bonus and PTO make it onto that return. Retire in December and nearly the full $120,000 arrives with them, along with anything else that lands late in the year.
That gap is the whole conversation in one line. The rest of what follows is just the ripple spreading out from it, hitting your brackets, your Social Security taxation, your Medicare premiums and your conversion room in different ways.
The income stack can push you higher.
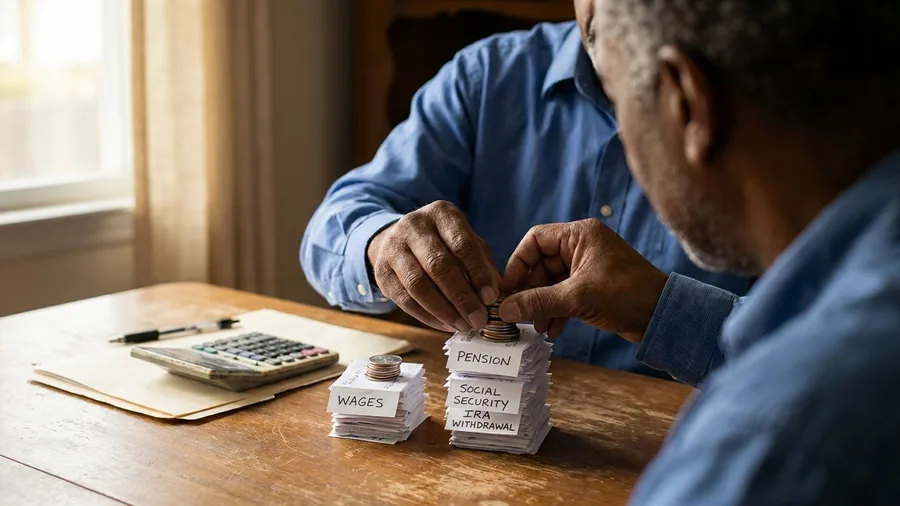
The income stack is everything that lands on the return in the same twelve months, and you avoid the worst version of it by not stacking a full year of wages on top of brand-new retirement income.
Retire in November or December and you have already banked almost a full year of pay. A bonus may have hit earlier in the year. PTO gets cashed out. Restricted stock or options can vest on the company's schedule whether you are still at your desk or not.
Then the new income starts arriving on top. The first pension deposit. The first Social Security check. An IRA withdrawal to bridge the gap before benefits begin. Your broker may even send a year-end mutual fund distribution you had nothing to do with. None of these is a mistake. The problem is pure overlap.
Brackets fill from the bottom up, so a full salary races through the lower ones and pushes the rest of the stack into higher rates. Nothing was mismanaged and you still pay more, because a larger share of your money lands in the top of your range compared with nearly every other year you'll live through.
Now picture February or March. Only six to eight weeks of wages reach the return. The taxable total drops sharply, and every other move you might want that year gets cheaper because the baseline underneath it is lower.
Same person, same salary, same savings. About $120,000 of wages late in the year versus roughly $30,000 early in it. Two months on a calendar separate a high-income year from a low-income one.
⚠️ COMMON MISTAKE
The late-year trap nobody names
Retiring in December and starting Social Security immediately puts a full year of wages and a full year of benefits on the same return. That single decision can make most of your benefit taxable when it did not have to be.
A December retirement can tax more of your Social Security.
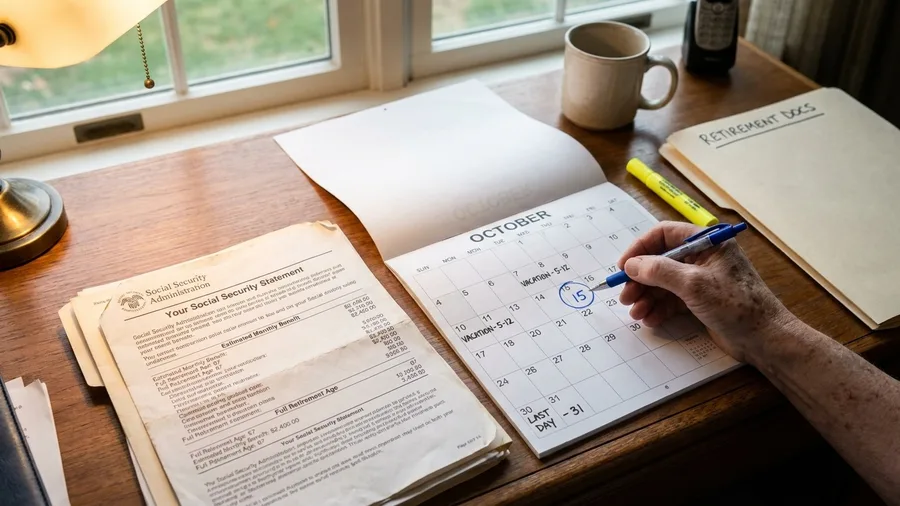
It raises the odds that most of your benefit becomes taxable, because a December exit keeps your wages and your first Social Security checks in the same calendar year.
Social Security taxation runs off a figure called provisional income. It totals your earnings, IRA distributions, interest, dividends, and 50% of your benefit. When that number is high, up to 85% of your benefit can be taxable. When it is low, only a small slice is, and sometimes none of it is.
The thresholds move, so pull the SSA's current rules and the IRS worksheet rather than working from an old number you remember.
Retire in December and claim right away, and you are dropping your benefit into a year where provisional income already sits near its peak. The high-tax outcome is close to automatic. Retire in March and you can let the wages fall off the return first, so the first check arrives in a much cleaner year.
You have more room here than most people assume. Social Security can start any month after age 62 and can be delayed all the way to 70. When your benefit begins is a separate decision from when you stop working, and you get to sequence the two.
Get that order right and the taxable share of your benefit can fall from most of it to a sliver.
A high-income year can raise your Medicare premium two years later.
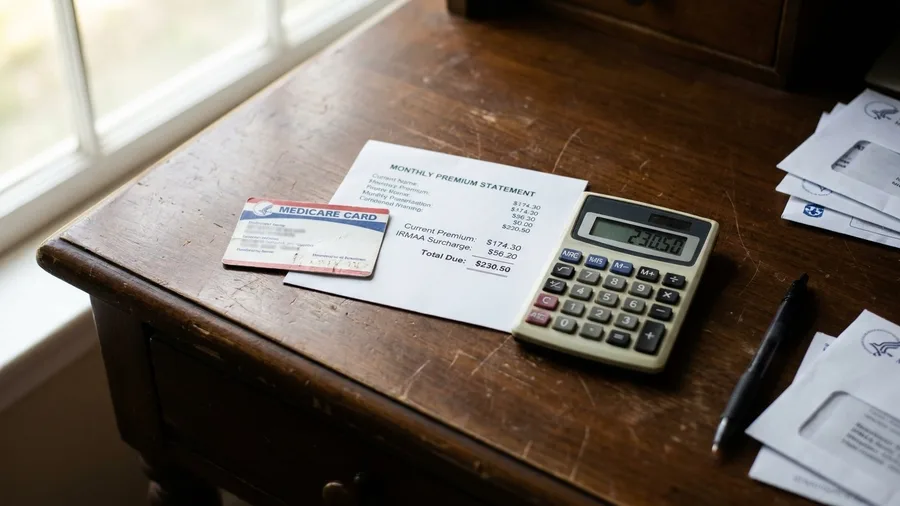
It can trigger an income-based surcharge on your Medicare premiums, because the program looks back two years to decide what you pay.
That surcharge is called IRMAA, and it is not small. It can add hundreds of dollars a month to your Part B and Part D costs, and it is set from the income you reported two years earlier. So the return you file in your retirement year is the one that sets your premium down the road.
A December exit is the perfect setup for it. Almost a full salary, a bonus, a PTO payout and a first IRA withdrawal all land on that return, and the total can push you over a tier. An early-year exit may keep your income low enough that IRMAA never fires at all.
The tiers and dollar amounts change, so open Medicare's current table instead of guessing at a threshold. Medicare also has a process for asking for a review when your income has dropped since that earlier year, and retirement is one of the situations worth raising with them.
Here is what makes it sting. The extra premium is not a one-time hit. You pay it every month for a full year before the next income test resets it, which is a long time to fund a surcharge created by income you no longer earn.
Early-year exit vs. late-year exit
Retire January–March
- Low wage total on the return
- Social Security can start after wages drop off
- Cheap room for Roth conversions
- Fewer first-year portfolio withdrawals
- Time to sort healthcare before the first claim
Retire November–December
- Full year of wages plus bonus and PTO
- Benefits likely taxed at the highest rate
- High income can trigger an IRMAA surcharge later
- Roth conversions become expensive
- Overlapping deductibles and rushed enrollment
Early retirement gives Roth conversions cheaper room.
You convert in a year when your tax rate is low, and retiring in the first quarter of the year gives you the case for a Roth conversion months earlier instead of making you wait.
A Roth conversion moves money out of a traditional IRA and into a Roth. You pay the tax now, and every dollar converted at a low rate is a dollar that never gets taxed again, growth included.
The first stretch of retirement is usually the cheapest window you will ever get. The salary has stopped, Social Security has not started, and the standard deduction has room to absorb income. Retire in December and that window stays shut for another year, because your first retirement year is still a high-income year and a conversion costs full price. Retire in March and by April your 401(k) balance, not a W-2, is the main story.
Run it with the example. Say you have $800,000 in a traditional IRA and a $120,000 salary that largely disappears in an early exit. That leaves a bracket with real room in it. Convert part of the IRA now and the future tax on that money's growth is gone.
Do the math with current IRS brackets, not rates you remember from a decade ago, and think about slicing the conversion across two or three years rather than doing it all in one go.
The spread between converting in a high-rate year and a low-rate one can be worth tens of thousands across a retirement.
Later retirement dates mean fewer portfolio withdrawals.
A later retirement date means fewer months the portfolio has to carry you in that first year, which cuts your exposure to sequence-of-returns risk.
Sequence-of-returns risk is the danger of selling investments in a downturn early in retirement. Sell into a bad market and you give up shares at the worst possible price. Those shares never come back, so the recovery has less to work with.
Count the withdrawals by month. Retire in January and the portfolio funds all 12 months of that first year. March, and it funds nine. June, six. December, one. The calendar quietly sets your exposure.
Run the example. With $6,000 a month of retirement spending, a January retirement pulls roughly $72,000 out in year one. March pulls about $54,000, June about $36,000, December about $6,000.
That gap is where the risk lives. Selling $72,000 after a bad first quarter is a different event from selling $6,000. Same portfolio, same plan, very different damage if markets go south early.
Don't overread it, though. This changes your first-year exposure only. The ongoing withdrawal rate still decides whether the money lasts thirty years or twenty, so a December date doesn't rescue a plan that spends too much. Think of the later date as a cushion on top of a sound plan, not a replacement for one. Check your own projected drawdown against the withdrawal your plan can carry.
An early date makes the healthcare switch smoother.
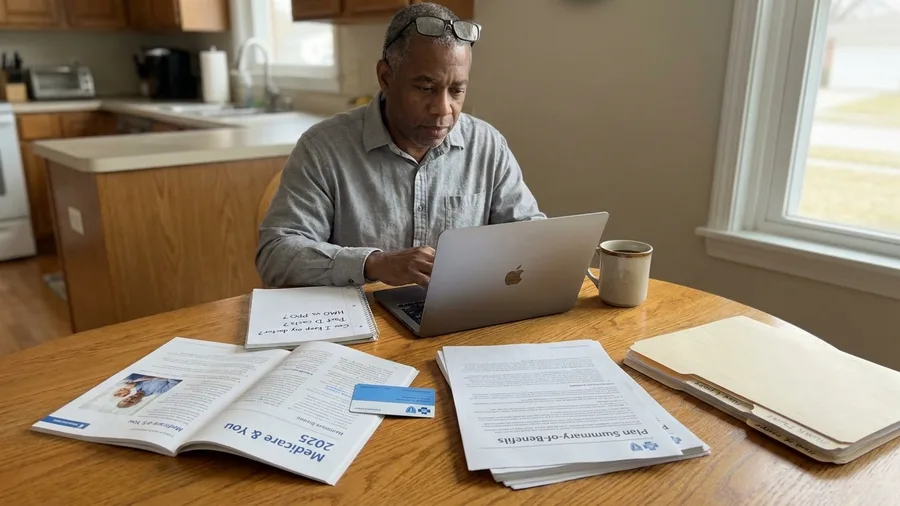
Retire before you sort out health insurance, not after. An earlier date in the year gives you months to move from employer coverage onto Medicare, COBRA, or a marketplace plan before the first claim lands.
Health insurance is the part of retirement that bites before the taxes do. You leave the employer plan and each option has its own enrollment rules and its own deductible cycle, and none of them line up neatly with a December exit.
Retire in December and the switch happens while you're still closing out work. You get overlapping deductibles, a coverage period nobody can quite explain, and a first claim filed before anyone has read the plan documents. That's how surprise bills happen.
Retire in, say, March and you get months of runway. Time to understand what Medicare Parts A, B, and D actually cover, pick a supplement or an Advantage plan, and schedule care around the new deductible instead of right before it resets. If a knee replacement is coming, timing it into a fresh deductible year can save real money, and timing it deliberately beats paying twice in one calendar year.
Go to the documents. Read your plan's summary of benefits and Medicare's enrollment rules directly, because the deadlines and penalties are specific and unforgiving. A smooth handoff is mostly a matter of giving yourself the months to do it.
💡 PRO TIP
Ask for the service-credit rule in writing
Pension service-credit rules live in dense plan documents. Request the specific paragraph in writing, or have your plan administrator confirm it by email, before you set your retirement date around a single day.
One January day can earn a full pension year.
It can, because some pension plans credit a full year of service to anyone who works even one day into the new year. Whether yours does is the whole question.
If your plan works that way, retiring January 2 can permanently raise your pension, and quitting on December 31 can permanently leave that year's credit on the table. On the example pension of $2,200 a month, one extra credited year is easy to measure and almost impossible to undo.
Do the long math. Over a retirement spanning twenty or thirty years, that single day of work is not a rounding error. It's a decision you make once and live with for a very long time, and it costs you a day of vacation to capture it.
So don't guess at the rule and don't take a colleague's version of it as gospel. Ask the plan administrator to confirm the service-credit provision in writing and apply it to a sample retirement date. Ask specifically whether partial years are rounded up, whether the credit requires work in the new calendar year, and how it flows into the benefit formula. The answer lives in the plan document, not in the break room.
Get it in writing, and if it comes back favorable, a January date may be the cheapest raise you'll ever earn.
December feels rushed; January feels like a clean slate.
It usually is, because a December exit collides with everything else that happens in December. Office year-end deadlines, holiday travel, family gatherings, the crowded social season. The retirement itself gets swallowed by the noise.
January or February feels like a start. The year turns, the parties are over, and you have space to notice the change and decide what comes next. That clean slate is worth something real, even though it never shows up on a tax return.
There's another factor in the timing that people underestimate. The last few months of work are usually the hardest emotionally. Once you've decided to go, you're already half out the door, and burnout peaks in that stretch. Choosing an earlier date can spare you those months.
But an early date can feel abrupt, and a late one can fit better than the logic suggests. If your company pays a bonus in February, if a stock award vests in March, if you need a coverage or vesting date to hold, or if you genuinely want the holiday goodbye, December might be right for you. The honest answer is whichever version you can live with, weighed next to the numbers rather than instead of them.
📅 Compare your two or three candidate months this way
List your income sources
Write down your salary, bonus, PTO payout, stock vesting dates, pension start, Social Security start, and any planned IRA withdrawals.
Project the transition-year total
Add up what would land on one tax return for each candidate month and compare the totals.
Check the two downstream systems
Look at the Social Security taxation thresholds and the Medicare IRMAA tiers against your projected income.
Measure the Roth window
Estimate how much conversion room the low-income year creates and what it costs to skip it.
Run the first-year withdrawal count
Multiply your monthly spending by the number of months between your date and the end of the year.
Check pension and healthcare rules
Confirm the service-credit rule in writing and map the coverage transition before the first claim.
Pick the date that fits the whole picture
Weigh the eight systems together and choose the month you can defend, not the one you inherited.
The best month depends on your full picture.
There is no single best month. There are eight systems to weigh, and your answer comes from whichever one dominates your situation.
Here's the list: income taxes, Social Security taxation, Medicare premiums, Roth conversions, portfolio withdrawals, the healthcare transition, pension credit, and emotional rhythm. Each one leans a little differently on the calendar, and they don't all point the same way.
For most people, an early-year retirement produces a cleaner transition. Wages fall off fast, the income stack stays low, the Roth window opens wider, and the withdrawal count is smaller. Not always. But more often than the calendar usually gets credit for.
So compare two or three candidate months side by side instead of assuming one is correct. Settle where your money comes from, what your health coverage looks like, and your Social Security plan first, because those are the facts you can't move. Then look at what your pension rule adds and whether a late exit pays you enough to justify a higher income year.
Write the projected numbers for each candidate month on one page. The comparison usually makes the answer obvious, and the cases where it doesn't are exactly the ones worth a second set of eyes before you hand in the badge.
Find your own numbers before you pick.
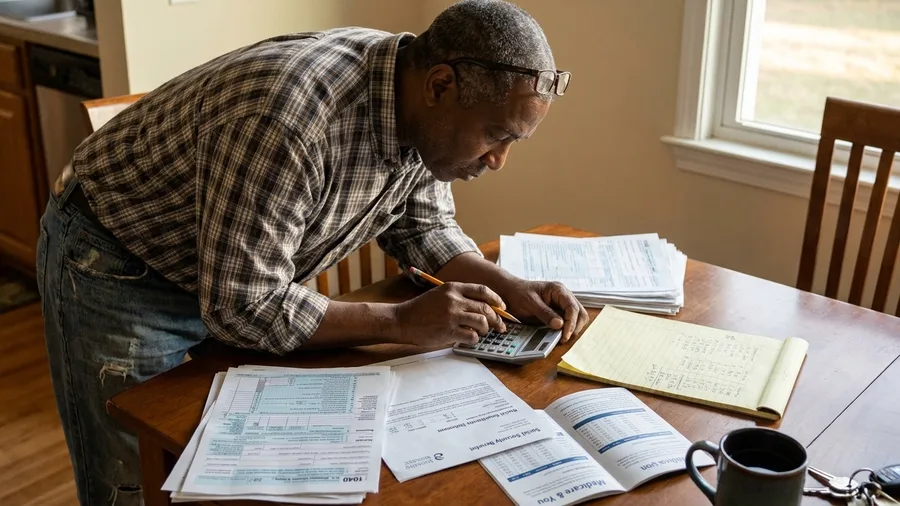
The last step isn't a decision, it's homework: pull your own live numbers before you commit to any month, because the thresholds that drive every comparison in this article get updated, and working from memory is how people get this wrong.
Three documents get you most of the way. Grab last year's tax return, sketch a projection of what each income source will pay you in the transition year, and download your benefit estimate from your account at ssa.gov. Together, those give you the raw material every month-by-month comparison runs on.
Then go to the source that publishes each figure, not a blog and not a remembered number. The IRS has the current brackets and the provisional-income rules. The SSA handles how your benefits get taxed and when you can start them. Medicare publishes the IRMAA tables, and it also publishes the appeal process for when your income drops after you stop working, which matters if a high year two years back is inflating your premium.
Run the comparison yourself once so you understand it, then hand the numbers to a tax professional or a financial planner to check before you set a date. Your own work gets you the picture; the second set of eyes is the safety net.
Frequently Asked Questions
Does the month I retire affect my taxes even if I retire mid-year?
Yes. A mid-year retirement splits the difference between a full year of wages and an early exit. It still stacks wages with any first pension check, Social Security benefit, or IRA withdrawal, so the tax return is a blend of working and retired income.
Can I delay Social Security to avoid the high-income year?
Yes. Social Security can start any month after age 62 and be delayed to age 70. Retiring early and waiting to start benefits until your wages drop off the return can lower your provisional income and reduce how much of the benefit is taxable.
How far back does Medicare look at my income?
Medicare uses the income from two years earlier to set your IRMAA surcharge. That means the tax return from your retirement year can raise your premiums later, so it is worth projecting both years before you pick a retirement date.
Is it always better to retire in the first quarter?
No. An early-year exit is often cleaner because taxable income drops fast, but a late-year exit can make sense if a bonus or stock vesting is scheduled, if your pension credits a full year only when you work into January, or if you want the holiday goodbye.
Can I do a Roth conversion in the same year I retire?
Yes, and the first few years of retirement are often the best time because your rate is lower. The lower your transition-year income, the more conversion room you have, so choose the retirement month with that in mind.
What documents should I gather before I compare retirement months?
Gather last year's tax return, a projection of your income sources for the transition year, and your Social Security estimate. Then pull current brackets from the IRS, benefit rules from the SSA, and IRMAA tiers from Medicare.
The date on the calendar that decides your first year
If nothing else dominates your situation, default to an early-year month. An exit between January and March usually produces the lowest income stack, the cheapest Roth window, the fewest first-year withdrawals, and the most time to sort healthcare. That is the safe choice more often than not.
Name the exceptions plainly. A late-year exit is the right call when a bonus or stock vesting lands there, when your pension credits a full year only if you work into January, when a coverage date matters, or when you simply want the holiday goodbye. Those are real reasons, not excuses.
Run your own numbers against the IRS, SSA, and Medicare, then have someone check the comparison. The month is a lever, and you are the one who decides where to set it.
Compare your two best months before you sign anything
Take your last tax return, your projected income, and your Social Security estimate. Put your two strongest candidate months on one page and check them against current thresholds before you hand in your notice.

Hello there! I’m Jesse Joe, the author and editor behind SolganGenius. I’m thrilled you’ve stopped by, and I can’t wait to share with you the essence of what this platform is all about.
I’m a writer, social media enthusiast, and a firm believer in the power of words. I’ve always been fascinated by how a simple phrase or slogan can capture an emotion, convey a message, and even change perspectives. Learn More