I once filed a December 31 IRA withdrawal request the year after a missed deadline and the money counted in the following year anyway; I had watched the calendar instead of the settlement date. Do not be that person.
Late November, the folder opens: $840,000 in a traditional IRA that has taken nothing this year, $2,850 a month from Social Security, a $1,100 pension, $18,000 in savings set aside for April, and a $3,000 charity check still unwritten. The instinct is that year-end tax moves belong to people with big gains or itemized returns, and this filer has neither now that the mortgage is paid off.
Property tax of $4,300 and a $3,000 gift do not startle anyone, and it is easy to assume that means nothing is left to do.
What is actually true is narrower and steadier: the required $40,000 withdrawal and its 20% ($8,000) withholding are the floor. Every other move adds income, offsets it, or uses the cash the withdrawal exposes, so the withdrawal sets the size of the Roth conversion, the loss harvest, the charitable routing and the April bill. Schedule it first, then work down a dated December order with a dollar amount and a keep-or-skip verdict at each stop.
Quick Tips Before You Start
Schedule the big withdrawal first
Request the $40,000 IRA withdrawal by the first week of December so the transfer clears before December 31.
Keep every confirmation
Save the custodian's withdrawal confirmation, the withholding election and the year-end statement in one folder.
Pull last year's return
Your prior-year 1040 shows the income that actually showed up, which is the baseline for every move below.
Protect the April cushion
The $18,000 savings account is for the tax bill, not for holiday spending or an extra conversion.
One call to the custodian
Ask for the exact required amount under the IRS uniform table; their number is the one to book, not your own estimate.
1. The Required IRA Withdrawal, Scheduled Early
Yes on the first count, and late November on the second. The calendar is the whole game here, not the amount.
Nothing has left the $840,000 traditional IRA in 2024. That is the fact that should make a 74-year-old sit up, because the required minimum distribution is not optional and December 31 is not a suggestion. A request typed on the 30th can settle in January, and January does not count toward this year.
The plan on the table is $40,000 gross, with the custodian holding back 20 percent, or $8,000, for the IRS. Picture the confirmation page: gross $40,000, federal withholding $8,000, net to the savings account $32,000. That $8,000 is money already sent in, not a fee, and it comes off whatever April would otherwise demand. Take the same $40,000 with nothing withheld and the April check is $8,000 heavier.
Nobody can hand you the required dollar figure from a magazine page. The starting age, the deadline that actually binds, and the amount itself come from the custodian running the IRS uniform table against the December 31 balance. The custodian's number is the one to book.
So the first move of the season is a phone call in the last days of November or the first days of December, early enough that the transfer has weeks to clear. A reader with no traditional IRA, or one already past the deadline, has nothing to schedule here. Everyone else: make the call before the month gets away.
💡 Tip: Ask the custodian for the required amount in writing. Their number, not a rough estimate, is what you book.
Required Withdrawal Myths, Corrected
2. A Roth Conversion Sized to This Year
The worry is always the same: I will convert too much and owe a tax bill I cannot cover.
Once the mandatory withdrawal sets the year's taxable income, the question flips. With $40,000 already on the return, a $20,000 Roth conversion sized to the bracket room that remains is deliberate income, not a surprise. In practice the hardest part was arithmetic, not paperwork: the $8,000 withholding sat in the $18,000 savings set aside for April, and I could see exactly how much cushion was left after the conversion tax came out of that same cash and not from the conversion itself, which would have shrunk what landed in the Roth.
The ceiling gets looked up in the IRS tables or set with a CPA, and the five-year rules for a Roth opened in 2019 live in Publication 590-B. This only works if the money can stay put for years and the savings still cover April afterward. If it cannot, the conversion adds income with nothing behind it.
💡 Tip: Do the conversion after the $40,000 withdrawal is confirmed, so you know exactly how much bracket room is left.
⚠️ COMMON MISTAKE
Don't withhold tax from the conversion
Withholding on a Roth conversion shrinks the amount that reaches the Roth and leaves the tax bill to be paid from the wrong pocket. Pay the conversion tax from savings; withhold only on the required withdrawal, where it acts as a credit.
3. Tax-Loss Harvesting in the Brokerage Account
The story going around is that a loss only helps if you are a trader who sold at the bottom and is now sitting on a pile of winners, yet which account to pull from first decides the tax bill. Not so. A loss on paper is worth nothing until it is realized, and once it is realized it becomes a number that comes straight off this year's taxable gains.
Start with what the account actually holds: $210,000 in the taxable brokerage, $60,000 of it unrealized long-term gain, plus two lots carrying $9,000 of losses. A Roth conversion piles income onto the return. Those two losing lots are the counterweight, and they only pull if the sale is executed before the year closes.
The system is three envelopes, and it takes one afternoon to set up. Envelope one: the gains you expect to realize this year, written down as a single figure. Envelope two: the losses on lots you are willing to sell, with the ticker of each written beside its dollar amount. Envelope three: the calendar, holding the 30-day wash-sale window that starts the moment a sale settles. Subtract envelope two from envelope one and that difference is your net taxable gain, the number the return will actually use.
The $9,000 is the entire benefit, and only against gains you realize. The tax saved is the tax on $9,000 at your rate, which at 15 percent is roughly $1,350. Real, modest, and small next to $60,000. Losses left over after the offset follow the IRS instructions, not a rule of thumb from this page.
Where the wash-sale rule bites: sell those two lots and then buy a substantially identical fund back within 30 days, and the loss is disallowed. IRS Publication 550 spells out the window. Mark the date the sale settles on a wall calendar and leave that space empty of any repurchase until it passes.
It does not help a portfolio with no gains to offset, and it does not help if those two lots are the core position the reader intends to hold through retirement. Selling a long-held stake to save $1,350 is a poor trade if it breaks the plan.
For this filer, the loss sale earns its place after two checks: confirm the wash-sale window, and confirm the two lots are peripheral, not the center of the account. The gain reduction is genuine but modest against $60,000.
💡 Tip: Wait 31 days before buying back a similar fund or ETF. The wash-sale rule counts purchases in the 30 days before and after the sale.
Loss Harvesting — The Numbers the Prose Left Out
🧮 Net gain after offset
$51,000 ($60,000 – $9,000)
↩️ Excess loss carryforward
$3,000/yr against ordinary income, unlimited years
📅 Repurchase deadline
Day 31 after settlement — mark it
🚫 Same-day trap
Buying back in any account (including IRA) disallows the loss
🛑 If the lots are core
Skip — $1,350 saved is not worth breaking the plan
Do this first
Sell before Dec 31; then leave 31 days empty of any substantially identical purchase in every account you own.
4. The Charitable Gift Made From the IRA
Nobody is auditing your generosity here. You can give the same $3,000 to the same two local nonprofits and simply route it differently, and that routing is the whole move. Writing the check in December works, and it is not wrong. But a direct transfer from the IRA to the charity never appears as income on the return at all, which matters for a filer whose itemizable pile is $4,300 of property tax plus a $3,000 gift – not enough to itemize, so a deduction you cannot use is worth nothing to you. Sending it from the IRA skips the deduction question entirely and keeps the income off the return.
The deadline is the part that gets missed. Request the transfer in the first week of December so the custodian's check actually clears before December 31; a check that settles in January is next year's gift, not this year's.
Eligibility runs through the IRS and the custodian – the age and limit conditions are confirmed by them, not assumed here. Already itemizing heavily and want the deduction? Keep writing the check; the direct gift trades that deduction for staying out of income.
| Move | What it changes | Finish by | Paperwork to keep |
|---|---|---|---|
| Required IRA withdrawal | Adds $40,000 to income; $8,000 withheld as a tax credit | Withdrawal clears by Dec 31 | Custodian confirmation, withholding election, year-end statement |
| Roth conversion | Adds $20,000 to income; builds tax-free Roth balance | Conversion processed by Dec 31 | Conversion form 1099-R, copy of tax payment from savings |
| Tax-loss harvesting | Reduces taxable gain by $9,000 | Trade settles by Dec 31, mind 30-day wash-sale window | Trade confirmations, cost-basis records for two lots |
| Charitable gift from IRA | Keeps $3,000 out of income entirely | Request first week of December | Custodian-to-charity transfer receipt, charity acknowledgment letter |
| Bunching deductions | Moves $7,300 toward the itemized pile | Property tax paid by Dec 31 | Property tax receipt, gift receipts |
| HSA reimbursement | Returns $10,500 cash with no income added | Withdrawal by Dec 31 | Receipts showing provider, date, service, amount, no prior reimbursement |
| Withholding on withdrawal | Covers the year's tax through the custodian, not an estimated payment | Election made when withdrawal is requested | Withholding confirmation from custodian |
| State tax check | Ohio withholding added to the $40,000 withdrawal | Before withdrawal processes | Last year's Ohio return, Ohio withholding election form |
| Family gifts | Moves $10,000 out before year-end | Transfers clear by Dec 31 | Bank transfer confirmations, gift records |
5. Bunching Two Years of Deductions Into One
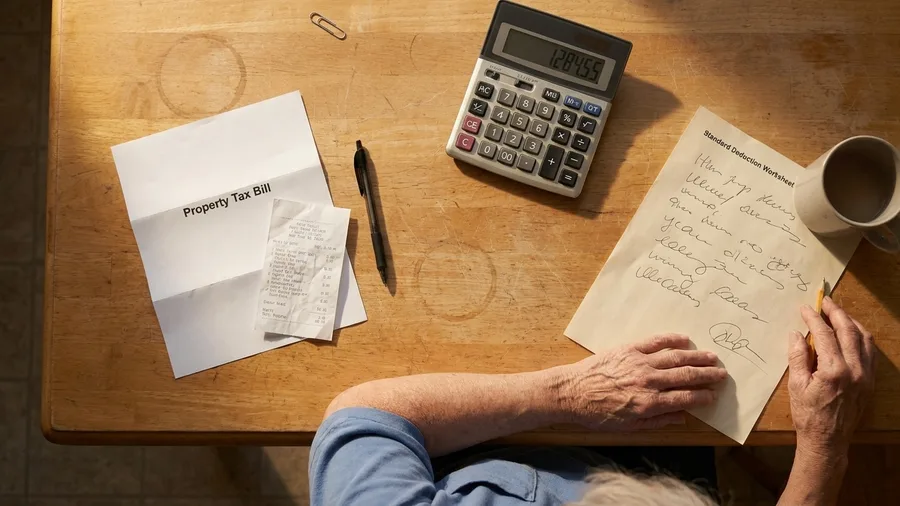
Add up what is actually left to itemize before you assume there is nothing. The mortgage came off the books in 2022, so what remains is $4,300 of property tax and the $3,000 gift – $7,300 if the gift is a check. Send that gift from the IRA instead and it cannot be deducted twice, which drops the pile to $4,300.
Next, pull the standard deduction for single filing status from the current Form 1040 instructions and put it beside your number. That comparison is the entire decision, and you can do it in ten minutes at the kitchen table.
If $7,300 does not clear that figure, bunching is not for you, and paying next year's property tax early buys you nothing but a tied-up $4,300 until the bill would have come anyway. Skipping is a real answer, not a failure. You are not leaving money on the table by declining a deduction that was never going to count.
Where it does turn worth doing: switch the charitable gift back to a check so it lands on the pile, and let other itemized costs – a big medical year, a large unreimbursed expense – stack on top. Then two years of property tax in one return can be enough to clear the standard deduction and make the whole exercise pay.
If you only have the $4,300 and the gift, do nothing this December. Bunching rewards a pile that already nearly clears the bar, and yours does not yet.
💡 Tip: Paying property tax early helps only in the year you itemize. In a standard-deduction year, it just ties up cash.
6. HSA Dollars for This Year's Medical Bills
An old health savings account will pay out this year's medical bills tax-free, and unlike a deduction it hands cash back whether or not the return itemizes.
It comes down to what the folder proves. Every receipt needs the provider's name, the date, the service, the amount, and something showing the plan never paid that bill. In this example that is $6,400 paid out of pocket since January plus $4,100 of older receipts still sitting unreimbursed, and the withdrawal only pulls back what those papers support, one matched dollar at a time; missing details shrink the number fast.
The lines worth checking with a CPA are the older receipts and anything touching Medicare enrollment, since IRS Publication 969 sets the rules and this article quotes no limits. With no HSA or no matching paperwork, every dollar pulled is just taxable income. For this filer, $10,500 of returned cash with no income added is the largest quiet move on the list.
Your December Tax Moves, Stacked by Priority
Start at the bottom: the required withdrawal sizes everything above it
7. Withholding on the December Withdrawal
The hour I spent on the phone with a custodian two Decembers ago, asking whether the withholding box on the form would count, taught me something I use every year: get the tax taken at the source and stop mailing checks, one of the retiree tax return mistakes a CPA sees repeat.
The $40,000 withdrawal comes with $8,000 of federal withholding built into it, and that $8,000 is not a payment sitting in a mailbox somewhere waiting to clear in April. It leaves the IRA through the custodian, the same way the withdrawal does, the same day, and the IRS records it as paid.
That timing is the whole point. When the underpayment penalty gets figured at tax time, withholding is treated as though it were spread evenly across the year, while an estimated payment carries only the date you actually mailed it. Two payments of the same $8,000 can produce two different penalty results, and the mechanics behind that sit in Form 2210.
Here is where the money gets real. Skip the withholding, mail the $8,000 yourself in January or April, and an underpayment penalty can quietly swallow the benefit of the $9,000 loss harvest, the $10,500 HSA reimbursement, or both. The moves still happen; the savings just get eaten by a charge nobody planned for.
So the setup is one conversation with the custodian, made once: $40,000 gross, $8,000 federal withholding on the election form, no separate quarterly estimate mailed for this year unless a CPA says otherwise.
Who can leave this alone? Anyone whose existing withholding already covers the year's bill. For this filer it does not, so the $8,000 withheld is the reason to cancel the extra check rather than send both.
Two things to confirm before hanging up: that the withholding lands with the withdrawal and not after it, and the confirmation number for the request. Then leave it alone.
💡 Tip: Withholding is counted as paid evenly through the year, so a December election can still cover earlier months. An estimated payment cannot do that.
Withholding vs. Estimated Payment: What Each One Costs If You Guess Wrong
Withhold from the IRA withdrawal
- Form 2210 treats it as paid in four equal quarters, even if the cash leaves in December
- Therefore no penalty for the December timing, which is the whole advantage
- Nothing to mail, so nothing to lose or forget in a January mailbox
- Keep the Form 1099-R showing the $8,000 in Box 4 for the CPA's file
Mail an estimated payment
- The quarter it counts against is the one whose due date you cleared, so a January check credits January
- Penalty is figured on the shortfall for each quarter you were under, at the federal underpayment rate plus interest
- A check lost in the mail counts as not paid until the IRS processes it, and the date on the stub is not the date that matters
- If a CPA already told you to file Form 2210 with annualized income, this is the only method that fits, so ask before switching
8. A State Tax Check on Retirement Income
Twenty minutes at the kitchen table with last year's Ohio return is the whole review, and it is worth doing before the $40,000 comes out of the IRA rather than after.
Federal withholding is handled once the custodian form is set. Ohio runs its own rules on the same money, and the state publishes how it treats a $1,100 monthly pension, Social Security and IRA withdrawals, along with any retirement-income credit or deduction a filer can claim. No figure is quoted here because the booklet is the source and it changes. Pull last year's Ohio return and read the line where the pension was reported, then check whether that credit was already taken. That single page tells you what the $40,000 withdrawal will add to the state bill.
The request for Ohio withholding has to go on the custodian's form in the same call that sets up the withdrawal. Ask after the money is processed and the option is gone for this year, which leaves the state share to be paid later out of the $18,000 savings.
This review is skippable if you live in a state with no income tax, or if you moved mid-year and file as a part-year resident. For an Ohio filer, the state bill is the one nobody sets money aside for. Twenty minutes ahead of the transfer beats finding the gap in April.
9. Family Gifts Finished Before the Holiday
Nobody needs to fear the gift tax on $10,000 to two grandchildren; the annual exclusion amount and any Form 709 reporting get looked up in the current instructions, and the real question is whether the cash can leave without breaking April's cushion.
The $5,000 to each grandchild was already planned for the holidays, before any tax thinking entered the picture. Moving the transfer before December 31 rather than after the holiday is the only tax-relevant change; it changes nothing else about the gift.
That is why this comes last. The $18,000 April-tax cushion survives the $10,000 only if the Roth-conversion tax, the HSA paperwork and the charitable routing have already been settled, which leaves $8,000 unless other cash covers the gap. Anyone whose reserve would drop below a year of spending should skip the gift; finish the $10,000 only if the cushion still covers the April bill, and otherwise keep the cash.
💡 Tip: The gift is not deductible, and it does not lower your income. It only matters for gift-tax reporting if you exceed the annual exclusion.
📆 Your December Order of Operations
This week
Call the custodian to schedule the $40,000 IRA withdrawal with 20% federal withholding, so it clears before December 31.
This week
Ask the custodian for the exact required amount under the IRS uniform table and confirm the Ohio withholding election on the same call.
By mid-month
Request the $3,000 IRA charitable distribution to the two nonprofits, and decide on the $20,000 Roth conversion once the withdrawal is confirmed.
By mid-month
Sell the $9,000 loss lots if the wash-sale window allows, and pull the HSA receipts for the $10,500 reimbursement.
Before December 31
Confirm every transfer has settled, and decide whether the $10,000 in family gifts still leaves the $18,000 April cushion intact.
January
Hand the CPA the custodian confirmations, the conversion form, the trade confirmations, the HSA receipts and last year's Ohio return.
Frequently Asked Questions
Do I have to take money out of my IRA this year if I don't need it?
Yes, once you are past the required beginning age, the IRS requires a minimum withdrawal each year. The custodian calculates the amount using the prior year-end balance and the IRS uniform table. Schedule the withdrawal early enough that it settles before December 31; a request that clears in January counts for next year and leaves this year short.
Should I convert IRA money to a Roth before December 31?
Only if you have bracket room left after your required withdrawal and can pay the conversion tax from savings, not from the conversion itself. For this example, a $20,000 conversion fits after the $40,000 withdrawal, but the exact ceiling depends on your income and filing status. Look it up in the IRS tables or set it with a CPA.
Is it better to write a check to charity or give from my IRA?
If you do not itemize, giving directly from the IRA is usually better because the money never shows up as income, and you do not need a deduction to get the benefit. The age and eligibility rules are set by the IRS and confirmed with your custodian. Request the transfer by the first week of December so the check clears this year.
Do I need to make an estimated tax payment in January?
Not if your withholding already covers the year. Withholding on an IRA withdrawal is treated as paid evenly through the year, so an $8,000 withholding in December can cover earlier months too. An estimated payment mailed in January is counted on the date it arrives and can trigger an underpayment penalty. Check with your CPA before canceling a quarterly estimate.
Can I use old medical receipts to reimburse myself from an HSA now?
Yes, if the receipts show provider, date, service, amount and proof the expense was not already reimbursed. The IRS allows reimbursement for qualified expenses incurred after the HSA was established. In this example, $6,400 from this year plus $4,100 of older receipts totals $10,500 available before December 31. Keep the records with your tax file.
Does Ohio tax my pension and IRA withdrawals?
Ohio has its own rules for retirement income, including a retirement-income credit or deduction. The specifics are published by the Ohio Department of Taxation, and no one figure applies to every filer. Pull last year's Ohio return to see how your pension was reported, and ask the custodian to add Ohio withholding to the December withdrawal before it processes.
The $40,000 Withdrawal Comes First, Then the Calendar
The verdict is plain: these are not nine equal chores. The mandatory $40,000 gross withdrawal, with $8,000 withheld, has to be booked first, because the income it adds is what sizes the Roth conversion, the $9,000 loss harvest, the $3,000 charitable routing and the April bill. Skip the bunching while the $7,300 itemized pile sits under the standard deduction, and skip the $10,000 in grandchild gifts if they would break the $18,000 cushion.
Week of December 1: book the $40,000 withdrawal with $8,000 federal withholding, open the $3,000 direct IRA charity request for the two local nonprofits, and ask the custodian about Ohio withholding on that same form. By December 15: sell the two losing lots for the $9,000 loss after the wash-sale check, decide the $20,000 conversion and pay its tax from savings, reimburse the $6,400 plus $4,100 HSA receipts, and finish the grandchild gifts only if the cushion holds.
In January the CPA gets the withdrawal confirmation and withholding statement, the QCD acknowledgment letters, trade confirmations, HSA receipts, last year's Ohio return, and any Form 709. Then the folder comes back out, one move already settled, and the calendar reminder you set this week is what keeps December 30 from being the day you call the custodian.
Schedule the $40,000 withdrawal this week
Call the custodian, request the required withdrawal with 20% federal withholding, and confirm the transfer will clear before December 31. Everything else on this list is sized around that one number.

Hello there! I’m Jesse Joe, the author and editor behind SolganGenius. I’m thrilled you’ve stopped by, and I can’t wait to share with you the essence of what this platform is all about.
I’m a writer, social media enthusiast, and a firm believer in the power of words. I’ve always been fascinated by how a simple phrase or slogan can capture an emotion, convey a message, and even change perspectives. Learn More