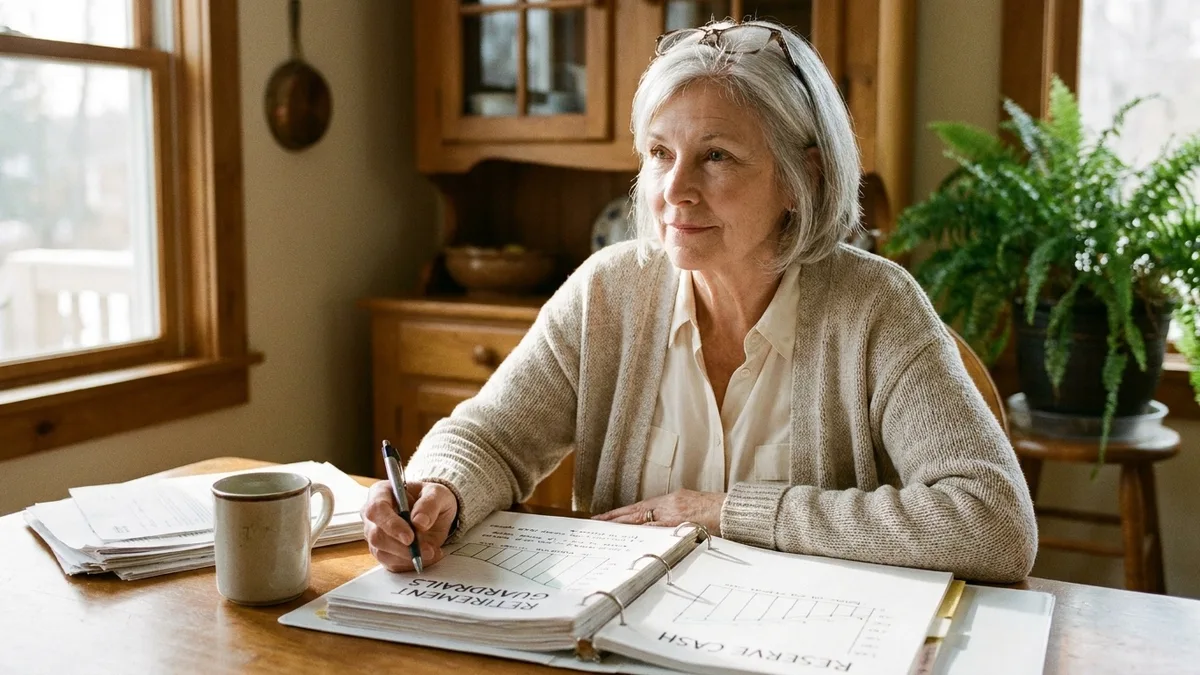
The first time a client crossed $3 million, I thought we were done. Fourteen years and hundreds of retirements later, I know I had it exactly backwards.
Almost everyone plans retirement the same way: put money away toward a target, avoid risk, take out as little as possible, and hope the rest works out. I held every one of those. Then I watched real retirements grade them against reality, and most didn't survive.
That gap is expensive, because the advice most people consume still teaches what I believed in year one. Here's what I saw instead, and what I'd tell you to do now.
Quick Tips Before You Start
Diagnose Your Level First
Before touching an allocation, figure out which wealth level you're in: foundation, comfortable, or abundant.
Write the Income Down
Turn the pile of money into a steady monthly figure you can point to on a piece of paper.
Rehearse the Drop
Write your response to a 25% decline before it happens, not during it.
Map the Low-Income Years
The years between your last paycheck and RMDs have expiration dates. Use them on purpose.
Design the Life Too
Ask what an ideal week looks like before retirement, not after the honey-do list is empty.
1. $3 Million Is a Starting Line, Not a Finish
That set of problems is exactly why the number itself was never the thing. Crossing $3 million doesn't finish the game, it changes it, and that was the first belief I had to unlearn after fourteen years of this work.
In my first year advising at this level, I assumed a household that hit $3 million had arrived and my job was keeping the ship steady. What actually happened is they ran straight into taxes at a scale they'd never seen, forced distributions coming, an unanswered survivor question, and no idea what was safe to spend. Four new problems, all at once.
So now I diagnose the level before we discuss a single allocation. Under $1.5 million is foundation, $1.5 to $3 million is comfortable, and $3 million and up is what I call abundant. Every relationship starts with which level this household is actually in and which problems belong to them.
The first two years after crossing that line shape the next twenty to thirty, which is why the diagnosis comes first. And here's the part that surprised me: abundant-level households were often more anxious than foundation households, because the advice they were reading was still written for people with a fraction of their assets.
💡 Tip: Write down every question you'd ask an advisor. If they can't name which level you're in and list your specific problems within the first meeting, keep looking.
| Level | Assets | What shows up | First move |
|---|---|---|---|
| Foundation | Under $1.5M | Covering basics, building buffer | Lock in a written monthly income figure |
| Comfortable | $1.5M–$3M | Balancing travel and long-term care risk | Map taxes and account sequencing |
| Abundant | $3M and up | Distribution strategy, tax windows, survivor planning, permission to spend | Diagnose level, then write the income plan |
2. Overcaution Buys a Bigger Balance and Fewer Years
The most cautious households I've worked with are the ones that wound up later in life with the largest balances and the fewest items actually crossed off their list. The trips got postponed until health canceled them. The help to the kids got delayed until the kids no longer needed it.
Inflation quietly eats an ultra-conservative portfolio over a long retirement. The number looks safe on paper and buys less every year, and over thirty years that gap is not small.
The fix isn't spending recklessly, it's a plan that tells you what you can spend. I use a risk-based guardrail system: you live on a steady monthly income while the plan's risk is evaluated every month, and spending happens inside boundaries you set in advance. Cross the upper guardrail and it's permission to spend more without the guilt.
I have never once heard a client say they wished they'd built a bigger balance. It's always about how to live the life they wanted. One caveat, though: if your current spending already sits above what your plan can sustain, the answer is the opposite of this.
🌱 GROWING TIP
Build the Written Income Before You Build the Budget
Turn your $3.2M into a steady monthly figure first. Then decide what to spend it on. Going the other direction is where the fear lives.
3. The Portfolio Doesn't Carry People Through a Crash
Spending with permission only works if you can hold your nerve when the market drops, and that's where a different belief I held for years was quietly wrong. I defended the idea that the portfolio decides the outcome longer than any other. Letting go meant admitting the product I was pitching was never the part that counted most.
Every client I had went through the same declines at the same time. The portfolios were similar. What separated people wasn't the allocation, it was whether we'd already rehearsed the storm together before it showed up.
For years I tried to engineer around volatility with layered products, extra meetings, fallback plans stacked on top of the portfolio. It never bought the steadiness I thought it would. Simpler is smarter: a well-diversified portfolio of quality companies, staying the course, and getting comfortable living with volatility instead of building ways around it.
What I do now is a lifeboat drill. Before the next drop, we sit down and walk through exactly what the plan will do when it comes, down to which account we spend from and what we don't touch. Picture a household that ran that drill in the fall: when the drop came in spring, the call was short because the decisions were already made.
If you want to feel steady in the next downturn, you need three things. A diversified portfolio, a level head, and a written plan for volatility.
Rehearsed vs. Unrehearsed
Household with a written drop response
- Knows the plan's next moves before the drop
- Spends through the storm without calling an advisor in a panic
- Both spouses on the same page about risk
- Uses the upper guardrail guilt-free when markets recover
Household that waits to see how they feel
- Makes decisions mid-crisis, when fear is loudest
- Often sells at the bottom or freezes entirely
- Spouse learns about the plan for the first time in a downturn
- Layered products attempt to engineer around volatility
4. Taxes Are the Largest Bill of the Entire Retirement
I added it up once and stopped thinking of taxes as an April task, because lifetime taxes rivaled or beat every other spending category the household had. The gap between managed and unmanaged households at this level routinely runs six figures, and every decision behind that gap was available to anyone.
It crawls up slowly. A reasonable year, another reasonable year, then a jump at 73 or 75 when required distributions begin, and no statement anywhere shows you the thirty-year total unless you go looking for it. The years between your last paycheck at 65 and required distributions at 73 are eight low-income years, a window with an expiry date, during which withdrawals or conversions of pre-tax money happen at controlled rates.
Map that window, then work it every year alongside a tax professional, and answer the end-game question: whose rate does that pre-tax money finally get taxed at, yours, your surviving spouse's filing single, or your kids'?
🗓️ The Eight-Year Tax Window, Step by Step
Age 65: Last paycheck ends
Eight years, 65 to 72, before RMDs at 73. Miss one and the rate is gone.
Map the window with a tax pro
Project each year's taxable income first, then convert only up to the top of your bracket.
Draw down or convert every spring
Convert early in the year, not December: recharacterize by the filing deadline if markets fall.
Sequence across account types
Spend cash first, then taxable, then pre-tax. Leave Roth last for the survivor's single-filer years.
Age 73: RMDs begin
RMDs on $1.4M pre-tax start near $51K; skipped RMDs cost 25%, or 10% if fixed within two years.
5. A Fully Funded Retirement Can Still Feel Adrift
It's a Tuesday about six months into retirement, the coffee's gone cold, the calendar is empty, and you realize the thing you planned for decades was the money and not the week. That's the moment the first retiree I helped wrote to me, eighteen months in, after the trips, the fishing, and a finished honey-do list. His question was short: now what?
I didn't have a better answer than to joke he could go fishing again. What he was missing had nothing to do with money. Some of the wealthiest households I've worked with were restless and adrift within two years, while those at a modest, comfortable level were flourishing, and the balance had nothing to do with which was which.
What work quietly supplied for forty years was structure, identity, community, and purpose. Retirement removes all four at once, and no portfolio can replace them.
So I ask life-design questions alongside the financial ones now. What does an ideal week look like, hour by hour? Who are you with? Where is the part that feels like contributing? Both spouses answer before they retire, not after, because the answers rarely match on the first pass.
The early years run on travel backlog and novelty. The later years run on purpose, and purpose has to be planned before you need it.
💡 Tip: Do this exercise on a Sunday evening, not a Tuesday afternoon. Spending a workday imagining not working reveals the real answer faster.
6. Four Beliefs I'd Start With at $3 Million
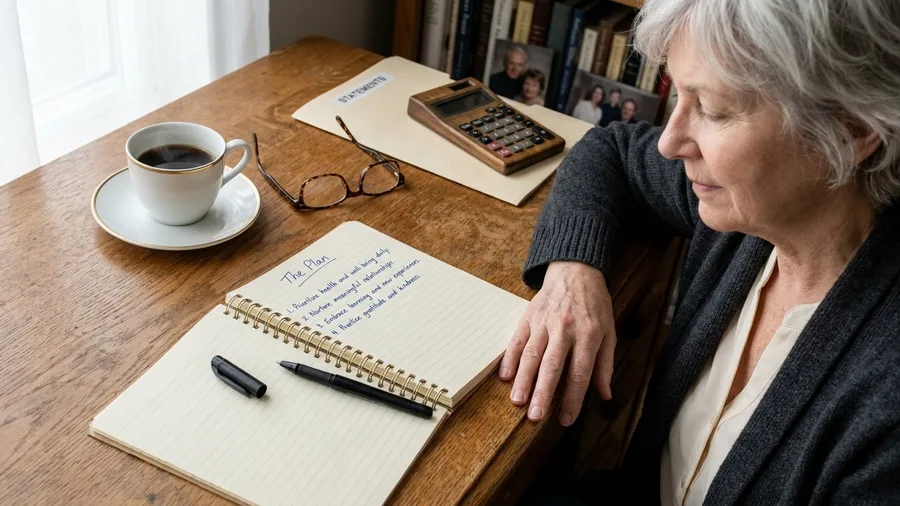
If the old beliefs were wrong, here's what I'd put in their place – and if you've been running on the wrong ones for a decade, I'll show you how to switch without starting over.
Belief one: the number is only the starting line, and the first piece of work is a written plan converting the pile into steady monthly income. Belief two: the plan exists to make bad market years boring, so the drop response is written in advance – guardrail rules set, both spouses in the room when that part gets built. Belief three: the tax bill is negotiable, but only on a schedule. Map those low-income years the minute you stop working, know when the first one expires, and work them every spring with a skilled tax professional. Belief four: purpose, people and experience planned with the same rigor as the withdrawals.
You don't need a clean slate if you've been running on different beliefs. I've watched people shift into this way of thinking well into retirement, with most of what they already owned still working.
How to Set Guardrails You Can Actually Follow
A guardrail only counts if you can follow it at 7am on a bad Tuesday, so let me put real numbers on the one I use. Take the household at $3.2 million with a $130,000 target. The lower guardrail sits at $110,000 – what you can spend through a rough stretch without endangering the plan. The upper sits at $150,000, roughly what's genuinely safe when markets cooperate.
Inside those limits you check portfolio risk monthly and do a full reset of the band once a year. The signals that trigger a change are the ones you wrote down in advance, not the headline you read at breakfast.
Then write two rules on a single sheet of paper. What exactly happens at the lower guardrail – which spending pauses, which income source fills in. And what the upper guardrail actually permits you to do, because permission is the hard part for most people at this level.
One catch: set and test the band against a simulated bad year before a real drop. Never renegotiate it in the middle of one. If you're setting these rules solo, sit with your spouse and write the numbers side by side first.
Your Guardrail Setup Checklist
-
Write the target annual spend. Example household: $130,000.
-
Set the lower and upper guardrails. Example: $110,000 lower, $150,000 upper on $3.2M.
-
Schedule the monthly risk check.
-
Schedule the annual band reset.
-
Write the two rules: lower guardrail and upper guardrail, exactly what happens.
-
Test both rules against a simulated bad year.
Run a Lifeboat Drill Before the Next Drop
How do you make a drop boring? You rehearse it before it happens, the way a ship's crew runs a drill in calm water, so nobody is learning under panic.
A lifeboat drill starts with a scenario written down in advance: a specific decline, a specific duration, a specific portfolio value at the bottom. Vague is useless. "A 30% decline over 14 months, ending around $2.3 million" is a drill you can actually run. From there the drill forces the decisions. What income stays identical? What gets cut first? What gets bought? Who is told what, and when? Each gets a written answer.
The rule inside the rule is both spouses in the room and a written record. Otherwise the plan gets renegotiated mid-crisis when nobody remembers what was agreed. Set a follow-up date to compare what actually happened against the rehearsal, and adjust whatever you broke.
The point is that the drop doesn't decide anything. You decided it months earlier, in daylight, with the numbers in front of you.
Already Retired and Too Cautious? Loosen in Steps
If you've been over-cautious for years, the correction doesn't require moving money around wildly. It starts with the written income floor, because that turns a higher spend into a boundary rather than a guess.
Loosen in this order: experiences with a health deadline first, then help to family while they still need it, then the discretionary extras. Test a higher spending level for a full year before committing to it, and know in advance what would send you back. Without those two pieces – the test period and the return condition – a higher spend will feel reckless and you'll quietly revert.
Most of these households don't need their assets rebuilt. They need a different set of rules around what they already own, and that can start well into retirement.
The one I remember most had been retired for years before she allowed herself to spend what the plan clearly supported. Nothing needed fixing except the rules.
Frequently Asked Questions
Do I need $3 million to benefit from these beliefs?
No, but the advice shifts with the level. Foundation and comfortable households benefit most from nailing down a written income floor and sequencing accounts. Abundant households get the biggest lift from taxes, survivor planning, and permission to spend.
How often should the guardrail band be reviewed?
Check plan risk monthly and reset the band annually. The specific signals that trigger a change should be written down in advance, not decided in the moment.
What if my spending is already above my sustainable band?
Then the overcaution advice doesn't apply to you. Your first move is to bring spending inside the band and figure out what changed. This isn't permission to spend more; it's permission for the household that's already under-spending.
Can I run a lifeboat drill on my own?
Yes. Write the scenario, answer the four questions, and set a follow-up date. Share the written answers with your spouse. What's harder on your own is honesty about what you'll actually do at the bottom.
How late in retirement can I make this shift?
I've watched people make it well into retirement with most of what they own still working. The assets usually don't need rebuilding; the beliefs and rules around them do.
The Order I'd Run the First 90 Days
Here's the verdict. Once you're at $3 million and above, nearly everybody has sufficient money. What decides the outcome isn't the balance but the belief system behind the decisions.
First 90 days: write the income plan that turns the pile into a steady monthly figure. Second, write the drop response before you need it. Third, map the tax window with a tax professional, with its expiry dates. The life-design conversation sits alongside, not after.
The household that should start somewhere else is one whose spending already sits above what the plan sustains. For them the first step is bringing it down, not loosening up.
And if you're already retired and over-cautious, you can make this shift now. You don't need to rebuild what you own. You need a different set of rules around it.
Start With the Written Income Number
Pick up a pen and write your target monthly income on a single sheet. That one number is the first belief in this article, and it's the one you can act on tonight.

Hello there! I’m Jesse Joe, the author and editor behind SolganGenius. I’m thrilled you’ve stopped by, and I can’t wait to share with you the essence of what this platform is all about.
I’m a writer, social media enthusiast, and a firm believer in the power of words. I’ve always been fascinated by how a simple phrase or slogan can capture an emotion, convey a message, and even change perspectives. Learn More