You've seen the headline: 18% of American households are millionaires. Sounds impressive, right? But then you ask the obvious question—does that include the house? And the answer changes everything.
Because a million dollars in home equity and a million dollars in a brokerage account are two very different things when you're trying to figure out how much income you can actually live on. One you can spend without selling the roof over your head. The other you can't touch unless you downsize or take on a loan.
So how many retirees really have $1 million in investments, excluding their primary residence? The short answer: roughly one in five. About 20% to 25% of retiree households have crossed that seven-figure mark in investable assets, according to data from the Federal Reserve's Survey of Consumer Finances. If you narrow it to retirement accounts alone—401(k)s and IRAs—the number drops to about 3%.
But those numbers come with caveats. Wealth is scattered across accounts, surveys miss the top end, and markets swing. By the end of this article, you'll know exactly what the statistics mean, how to check your own two net worth figures, and how to translate your portfolio into an income you can actually spend.
| Measure | Share | What it includes | What it tells you |
|---|---|---|---|
| Households with $1M+ net worth | 18% | Home equity, investments, everything | Broad wealth, but not spendable income |
| Households with $1M+ excluding home | 8–10% | Investments and other assets, no primary residence | Closer to investable wealth across all ages |
| Retirees with $1M+ in investable assets | 20–25% | Brokerage, savings, retirement accounts, minus home | About one in five retirees have $1M outside the house |
| Retirees with $1M+ in retirement accounts alone | ~3% | 401(k)s and IRAs only | Most people don't hit $1M in a single account type |
The 18% Millionaire Headline Counts Home Equity
It does. The 18% figure is a net worth number, which means everything you own minus everything you owe, and your house is sitting right there in the middle of it.
The Federal Reserve's Survey of Consumer Finances is the source behind most of these headlines, and it counts home equity alongside checking accounts, 401(k)s, cars, and small businesses. Nothing sneaky about it. It's just a broad measure.
But look at the median and the story changes fast. Median household net worth in the US is about $192,000. Strip out home equity and that median falls to roughly $57,900. That's the gap between a real cushion and almost nothing.
So the headline isn't wrong. Net worth is a legitimate way to measure wealth. It just answers a different question than the one you're probably asking, which is how much income your portfolio can actually produce. That's investable wealth, and it's a smaller slice of the pie.
Once you take housing out, the share of millionaire households drops to roughly 8% to 10% of the population. Still millions of people, but about half the headline. Among retirees specifically it climbs back to around one in five, simply because they've had decades to save and let compounding work.
The Home Dominates Most Families' Net Worth
Because for most families outside the top percentiles, the house is the single biggest thing they own, often half or more of total net worth. Count it and you can cross the million-dollar line without much sitting in the bank.
That ratio flips as wealth climbs. For families with $2 million or more, home equity tends to shrink to about 20% to 30% of total wealth. The rest is financial assets that throw off income. That's the real reason the top 10% look so different from the middle.
Home equity is genuine wealth, to be clear. You can sell, downsize, or look into a reverse mortgage if you're older and need the cash. But it isn't a liquid income stream unless you actually tap it. And plenty of retirees have no intention of selling the house they've lived in for thirty years.
There's a catch people miss. A house carries costs that eat into the wealth it represents: property taxes, insurance, maintenance, and the reality that you still need somewhere to live after you sell. Downsize from a $600,000 home to a $400,000 one and you've freed up $200,000, not $600,000.
So when you're planning income, the investable number is the one that matters most. The home number is worth knowing, but it's a different conversation.
💡 PRO TIP
Two numbers, not one
Your net worth including your home tells you your overall wealth. Your net worth excluding your home tells you what you can actually spend. Keep both, but use the second one for retirement income planning.
Same $1 Million, Very Different Retirement Income
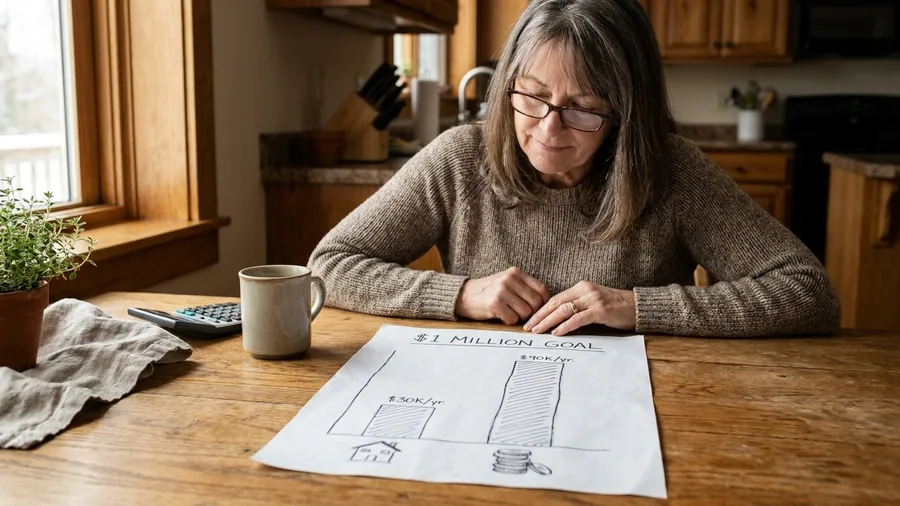
It can produce roughly four times as much income if the million is mostly portfolio rather than mostly house. Same headline number, wildly different life.
Take Person A: a $200,000 home plus an $800,000 portfolio. Now Person B: an $800,000 home and $200,000 in investments. On paper both are millionaires.
Run a 4.7% withdrawal rate, a common rule of thumb for sustainable retirement income, and Person A pulls nearly $38,000 a year, much like creating your own salary from a portfolio. Person B gets a little over $9,000. That's the whole difference in one sentence.
This is why separating investable assets from home equity matters so much. The $1 million tag alone tells you nothing about what kind of life you can afford. The composition of the million does.
One caveat worth flagging. These are pre-tax numbers, and taxes will take a bite, especially from traditional 401(k)s and IRAs. But the relative gap between A and B holds up no matter how you slice it.
Keep Two Net Worth Statements
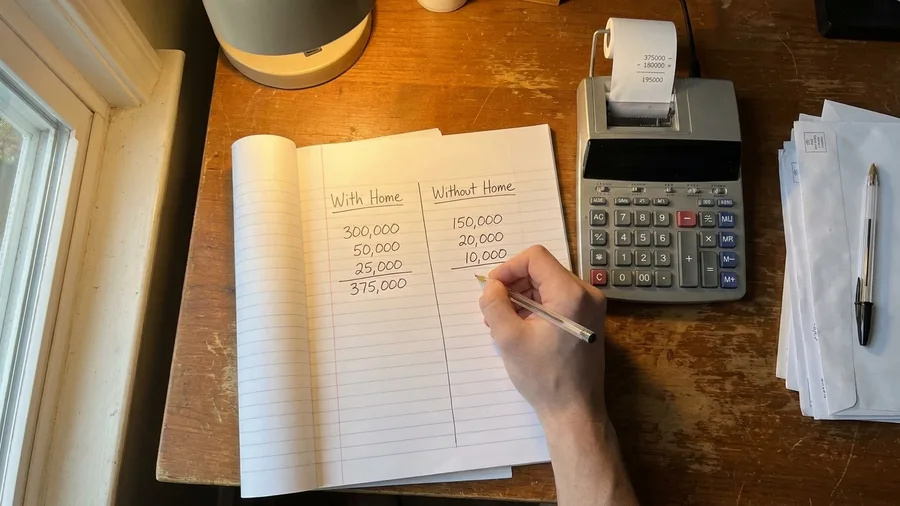
Use the one that excludes your home, because that's the figure that translates into withdrawable retirement income. But don't throw away the including-home number either.
Keep both. One statement that counts your home value and one that doesn't. The second is your spendable wealth, and it tells you the income you can realistically draw once you stop working.
The including-home figure still earns its place. It matters for overall wealth, for decisions about downsizing or aging in place, and for whatever you plan to leave behind. It's just not the line you build a monthly budget from.
Here's how to actually do it. Pull your latest balances from every account, add them up, and jot that number down as Statement A. Then add a realistic home value minus any mortgage and write that down as Statement B. Update both on the same day each quarter so the comparison stays honest.
This isn't about ignoring your house. It's about knowing which assets can generate income without you having to sell where you live. For most retirees, that distinction decides the lifestyle.
Retiree Investable Wealth Peaks Far Below $1 Million
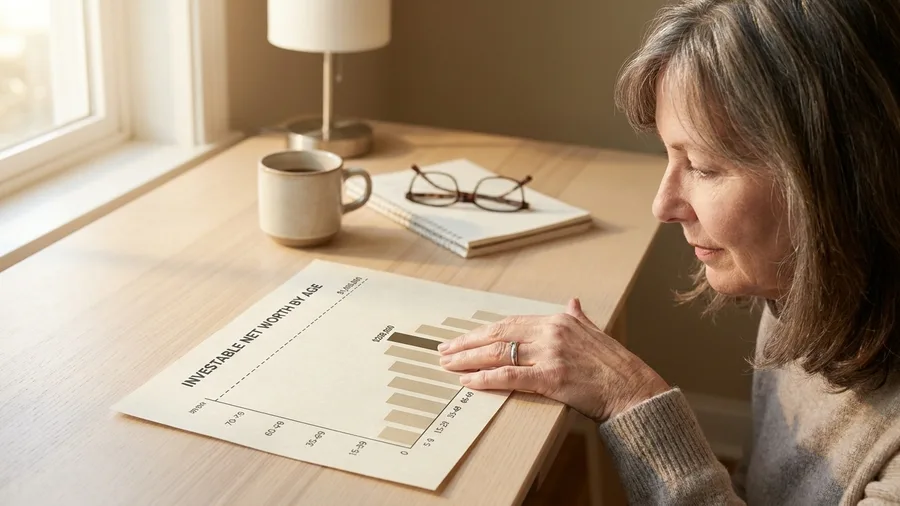
For people aged 65 to 69, median investable net worth hits a peak of roughly $238,000. Half of that age group has less outside their home, half has more.
The upper end spreads out fast. The 75th percentile sits around $784,000, and the 90th percentile reaches about $2.3 million. So the typical retiree is nowhere near seven figures in investable assets, even though the top tenth clearly is.
That puts $1 million in a specific place. It's above the 75th percentile but well short of the 90th. In plain terms, it lands you in the top quarter of retirees, not the top 10%.
Worth being precise about what's counted here. These figures exclude the primary residence and include brokerage accounts, retirement accounts, savings, and other financial assets. So a retiree with a paid-off house and $238,000 in a 401(k) and an IRA is sitting right at the middle of the pack.
The numbers come from the Survey of Consumer Finances, which is the most reliable picture we have of household wealth, even with the gaps surveys always carry. If you want to know where you stand, compare your own investable total to those percentile lines rather than to the headline.
About one in five retirees has $1 million in investable assets outside the home. That's roughly the 78th percentile.
— What the data shows
Based on Federal Reserve Survey of Consumer Finances data
The 75th Percentile Is $500K to $800K
Roughly speaking, $500,000 to nearly $800,000 is what the 75th percentile of investable assets looks like across age groups once the primary residence is stripped out.
That 75th percentile is the top quarter of households, and it moves as people age: lower for younger households still building, higher for those in their peak earning and early retirement years, then flattening out. The 90th percentile tells a very different story. There, the figure is at least $2 million for nearly all age groups. So the distance between the 75th and 90th is not a small step. It's a cliff.
That single fact explains why $1 million sits in an odd spot for most ages. Look at the ladder like this. At the 75th percentile you're at roughly $500,000 to nearly $800,000. At the 90th you're at $2 million or more. A cool million on that scale is above the 75th rung but below the 90th.
Which is exactly why the same $1 million gets called the 78th percentile most of the time. It's a useful benchmark, and it puts you comfortably in the top quarter of households.
But it's not the top of the heap. Plenty of retirees have more. And plenty have less, which is the part that gets lost when a headline just says 'millionaire' and moves on.
$1 Million Lands Around the 78th Percentile
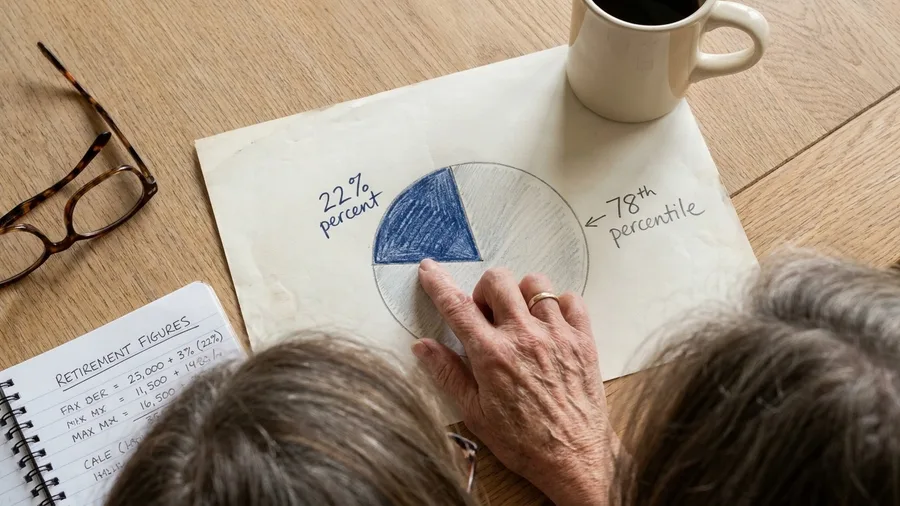
About one in five retirees has $1 million or more outside the home, which is why that level reads as roughly the 78th percentile for many age groups.
Put the numbers side by side and it gets concrete. Around 22% of households in the relevant age brackets hold $1 million or more excluding the primary residence. So you're not looking at a rare club. You're looking at a solid fifth of retirees.
What does the 78th percentile actually mean in human terms? You're in the top quarter. You're above the vast majority of households once the house is taken out of the math. But you're not in the top 10%, where the figures jump past $2 million.
Here's the part that surprises people. If a retiree has $1 million in investable assets, that person is not unusual among their peers. Millions of households have crossed that threshold. The median is much lower, sure, but the upper tail is thicker than the headlines suggest.
So $1 million outside the home is a genuine milestone. It's just a common one, not a rare one, and knowing that should take some of the sting out of the comparison game.
Retirement Accounts Alone Show Only About 3%
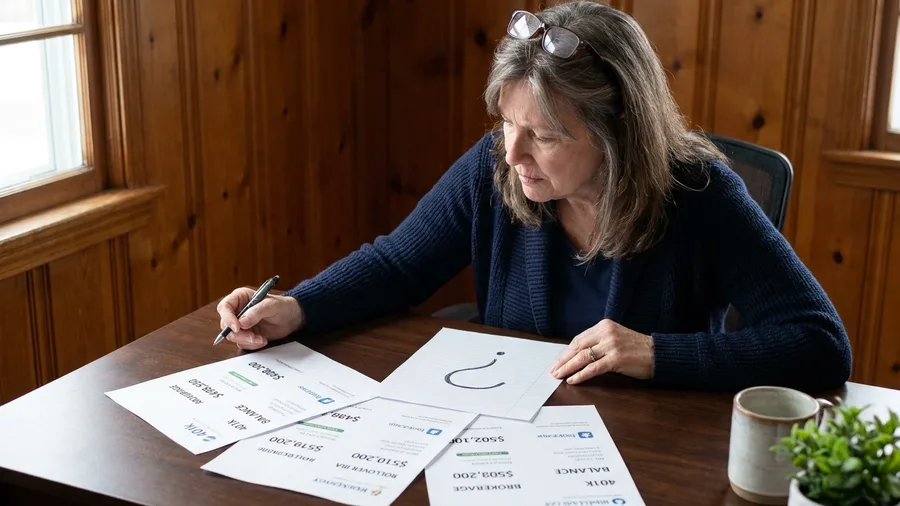
Only about 3% of retirees have $1 million or more in retirement accounts alone, which is a much smaller share than the one-in-five you get when you count all investable assets.
That 3% figure sounds alarming until you see what's causing it. Say you've got $500,000 at one brokerage and another $500,000 at another. You do hold $1 million in investable assets. But neither firm's records show you as a millionaire, because each one only sees its own half.
Even if both accounts sat at the same institution, they wouldn't be combined unless you actually consolidated them. Nothing forces that to happen.
So the 3% is almost certainly an undercount. It reflects how scattered retirement money is across old 401(k)s, rollover IRAs, and legacy accounts from jobs you left decades ago, not any shortfall in real wealth.
Which raises the obvious question: if the 3% is too low, what is the true number? Probably higher than 3% and lower than 22%. Nobody knows exactly, and the reason nobody knows is the subject of the next few years of your financial life, whether you like it or not.
How wealth is counted vs. how it's actually held
What surveys capture
- Individual account balances reported by each institution
- Self-reported net worth from surveys
- Top-coded values for the ultra-wealthy
- Assets that are easily valued
What reality looks like
- Multiple accounts at different brokerages
- Forgotten 401(k)s from old employers
- Illiquid assets like businesses and collectibles
- Pensions, life insurance cash value, crypto
Wealth Is Fragmented Across Many Accounts
Counting millionaires is hard because there's no central place where anyone's assets are all added up, and no institution is required to report your net worth.
Think about what a typical retiree actually holds. A 401(k) from a former employer. An IRA. A brokerage account. A bank account. A high-yield savings account. Some cash. An old pension. Maybe a trust. A small business. A crypto wallet. Each one sits with a different custodian, and none of them talk to each other.
Here's the bit most people miss. Unlike your wages, which get reported to the IRS on a W-2 or 1099, there's no line on your tax return that asks you to list your net worth. Tax returns capture fragments, like interest, dividends, and required minimum distributions, but not the full picture.
So even someone who wanted to report their exact situation would have to gather statements from every institution. Most people don't bother. They give their best guess. And that guess might be off by thousands of dollars.
That gap between a guess and a real total is exactly why the survey numbers are so noisy, and it's why the next thing worth understanding is how those survey numbers actually get built.
Surveys Miss Top Wealth and Illiquid Assets
Survey numbers are the best estimate available, not a precise count, because they lean on self-reporting, lose resolution at the very top, and struggle with anything hard to price.
Start with the wealthy. High-net-worth households often won't give an exact value. They might say 'over $30 million' rather than specify.
That practice is called top-coding. It protects privacy, but it means the survey records a billionaire the same as someone sitting just above the threshold, and you lose all the detail between them.
Then there are the assets that don't have a clean price tag. Private business equity. Collectibles. Non-primary real estate. Pensions. Life insurance cash value. Crypto. How do you value a pension on a survey form? Or a closely held small business? There's no consistent way to do it, so these items just add noise to the totals.
The result is that the survey figures are estimates, not gospel. They're the best we have, and they're worth trusting directionally. But when a headline quotes a single number, it's worth remembering how much estimation sits behind it.
People Have Reasons to Under-Report Wealth
Some do, and the reasons are more practical than dishonest. Safety, taxes and plain personal discretion all push people toward keeping their money quiet, and a survey answer is one more place where quiet is easier than candid.
Think about who is on the other end of that phone. Nobody wants to tell a stranger their net worth, even when the survey is anonymous and the caller is polite. That instinct alone drags the reported numbers down a notch.
Here is the deeper issue, though. No official body has ever asked most people to total every account across every institution. Not once. So even a willing participant is usually guessing.
Picture the exercise. You have a checking account, a savings account, an old 401(k) from two jobs ago, a brokerage account, maybe a pension statement in a drawer. Could you produce an exact figure in five minutes? Probably not. You would estimate, and estimates tend to come in low rather than high.
So the published wealth figures are likely skewed downward. The real share of millionaire households is probably a little higher than reported, though not dramatically so. Treat the statistics as a floor, not a ceiling.
The practical takeaway is simple: don't measure yourself against a number that is itself an underestimate of an estimate. Use the figures to understand the shape of the distribution, then work from your own statements.
Timing and Market Swings Distort the Count
It does, and that is exactly why the headline figures feel off when you compare them to your own balance. Markets move constantly, while the wealth data is collected every three years.
Take the Survey of Consumer Finances. It is the backbone of almost every millionaire statistic you have seen, and it is published long after the year it describes. By the time those numbers reach a headline, the portfolios behind them have already shifted.
A portfolio worth $1.2 million in the survey year might sit at $900,000 today, or the reverse. Nothing about the person changed. The market did.
That matters more than it sounds, because the seven-figure line is a thin slice of the distribution. A few percent of movement in either direction pushes people across it and back. Net worth swings year to year around that line, and a single snapshot cannot capture the wobble.
So when a table tells you that you are above or below the cutoff, remember you are comparing today's balance to a photograph taken years ago. The picture may not match the account you are looking at right now.
Don't get too hung up on the precise percentages. The trends are the useful part. Whether the middle of the distribution is drifting up or down tells you far more than whether you personally cleared a round number in one particular quarter.
⚠️ COMMON MISTAKE
Don't compare your guess to a survey
If you're estimating your net worth from memory, you're likely missing accounts. Take the time to gather every statement before you compare yourself to any statistic.
Check for a Forgotten 401(k)
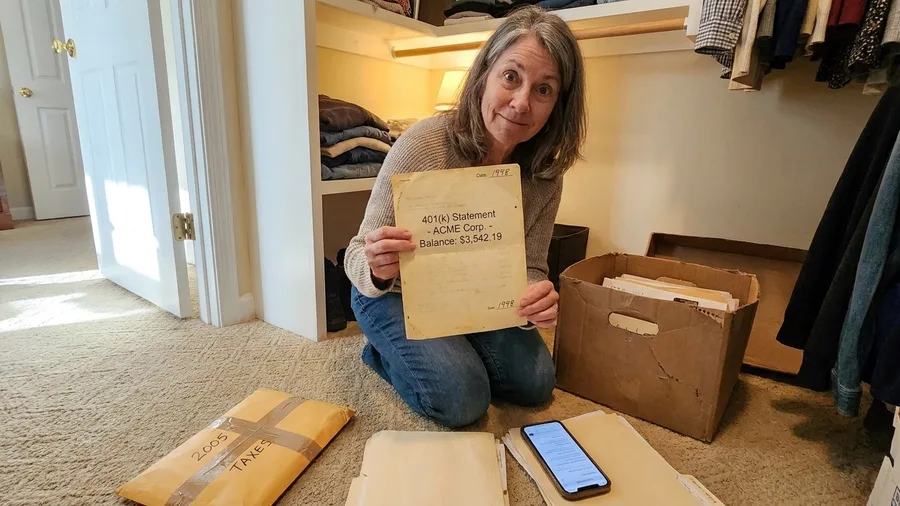
You might, and it is worth a few hours to find out. There are roughly 132 million US households, and an estimated 32 million forgotten or untouched 401(k)s sit out there holding over $2 trillion in assets combined.
That is a lot of money belonging to people who simply lost track of it. Job changes, mergers, address moves, a plan administrator who switched recordkeepers, and suddenly a statement stops arriving.
So before you compare your balances to any statistic, check old employer plans first. Dig through old files, call former HR departments, and search the National Registry of Unclaimed Retirement Benefits. If a plan changed names, search under the old one too.
Finding an old account can change your net worth picture significantly. A $40,000 balance you forgot about is not life-changing on its own, but it moves you up the distribution more than most people expect.
It is worth a few hours of effort. That forgotten account might be the difference between being a millionaire and not, at least on paper.
Set a reminder to repeat the search every few years, since plans keep consolidating and old accounts keep surfacing.
One Survey Underpins Most Wealth Figures
Almost all of them trace back to one place: the Federal Reserve's Survey of Consumer Finances. When you see a chart about median net worth or the share of millionaire households, that is almost certainly where the underlying numbers came from.
It runs every three years and surveys somewhere between 4,000 and 6,500 households. That is a small sample for a country this size, which is why the design matters so much.
The survey deliberately over-samples wealthier households, because wealth is concentrated at the top and a random sample would catch too few of them to say anything reliable. It then weights the responses to represent about 132 million households.
The breadth is impressive. It covers checking accounts, retirement accounts, mortgages, small businesses, and even car values. Everything gets counted, which is part of why it is treated as the gold standard for US wealth research.
But here is the caveat that matters most: it is a survey, not a census. It depends on self-reporting and statistical adjustment. The result is a careful, well-built estimate, and an estimate all the same.
So when you see a precise-looking percentage, remember it carries a margin of error. The direction is trustworthy. The decimals are not.
The Survey of Consumer Finances — The Fine Print
🧾 Reporting gap
No central asset registry; tax returns never list net worth
🔍 Missing accounts
~32 million forgotten 401(k)s holding over $2 trillion
📈 How to read a percentile
90th = top 10%; 75th means 3 in 4 fall below
🏡 The line that shifts the story
Include the home: ~18% of households are millionaires. Exclude it: ~8-10%
Use it this way
Trust the ranking, ignore the decimals. And for 401(k)s left behind at old jobs, check the Labor Department's abandoned plan database, since one account can move you a whole percentile.
A Million Buys Different Lives by Location
Further than you probably think in some places, and much less far in others, because a million dollars is not a fixed quantity in practice. It is a number that gets translated into daily life by whatever things cost where you live.
In the rural Midwest, $1 million might mean a spacious home and real breathing room in the budget. In San Francisco, the same amount might mean a modest apartment and living paycheck to paycheck. Same figure, two entirely different lives.
It is not just within the US. Holding 5.9 million Philippine pesos or 8.9 million Indian rupees sounds like a fortune, but it converts to roughly $100,000. The currency illusion makes the number look bigger than the purchasing power behind it.
Economists call this relative income, or positional goods. What matters is not only the raw balance but what it buys compared with the people around you. A million in a neighborhood of two-million-dollar homes feels modest. In a town where homes sell for $150,000, it feels like security for life.
That is why comparisons across regions and countries can mislead. Your number needs to be judged against your own cost of living, not someone else's headline.
The Big Picture in Four Numbers
Here's the whole picture in four numbers. Around 18% of US households are millionaires if you count home equity. Strip the house out, and it drops to roughly 8% to 10% of everybody.
Among retirees, about 20% to 25% have $1 million in investable assets outside the home. But only about 3% carry that much in retirement accounts alone, which tells you a lot about how much wealth sits in taxable brokerages, business stakes and other places.
That last gap is the one people miss. Someone with a $400,000 401(k) and a $600,000 brokerage account would show up in the 3% crowd as a no, and in the investable crowd as a yes. Same person, two very different headlines.
Treat all four as estimates, not headcounts. They come from survey data weighted to the wider population, so they're close enough to show where you stand and loose enough that nobody should be reading them as an exact tally.
If you take one thing from this whole exercise, take this: the answer to whether you're behind depends entirely on which of those four numbers you were comparing yourself to, and most people have been looking at the wrong one.
📈 How to track your net worth
Quarterly check-in
Do a quick review every three months to track progress without overreacting to market noise.
Annual deep dive
Once a year, update every account, asset, and debt for a full year-over-year comparison.
Keep statements
Save your annual net worth statements to see progress over time.
Use the excluding-home figure
This number shows the income you can generate if you plan to stay in your home.
Track Net Worth Quarterly and Annually
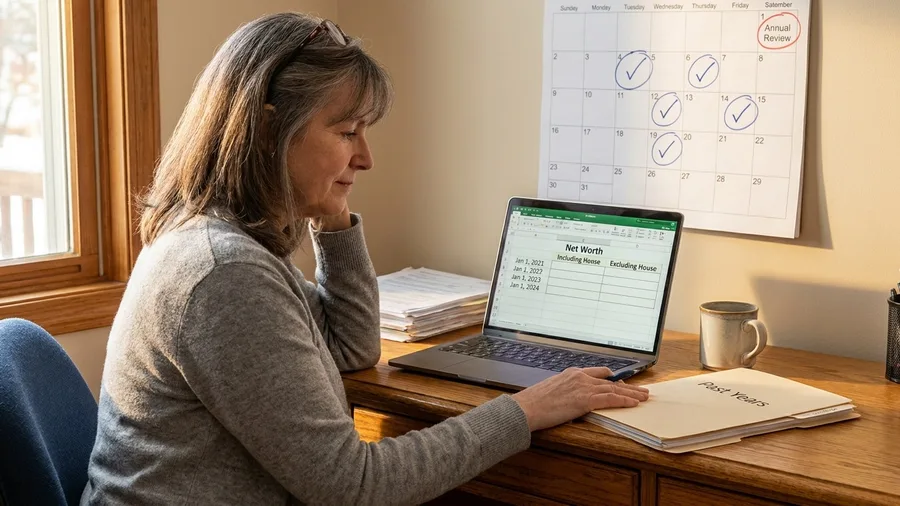
Track it quarterly and then take one full annual deep dive, keeping both versions every time: the net worth including your home and the one without it.
Quarterly is the sweet spot. Once every three months, sit down and update your numbers, and you get a clear read on progress without spiraling every time the market has a bad week.
A quarter is long enough for real movement to show and short enough that you remember what you changed. Do it the same month every time so the comparison stays honest.
Then once a year, go through everything: every account, every asset, every debt. Compare it against last year's page and you'll see progress that felt invisible month to month.
Keep those annual statements somewhere you'll find them. There's real value in pulling out a sheet from five years ago and seeing the gap you closed without noticing.
The excluding-home figure matters most if you plan to age in place. It's the number that shows the income your portfolio can actually generate while you stay put, since the house won't be funding your groceries.
So quarterly for the pulse, annually for the full picture, and both columns every time.
Stop Fixating on $1 Million
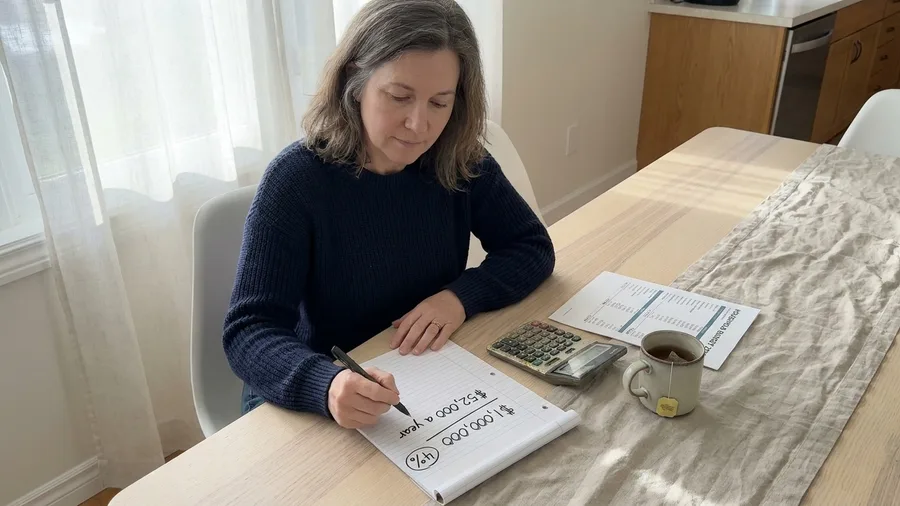
Your number is whatever produces the income your lifestyle needs, which might be well above a million or comfortably below it.
Start from the spending side. Add up what a normal year actually costs you, then translate that into a portfolio size using a withdrawal rate you're comfortable with: 3.5% if you want to be careful, 4% as a middle ground, 4.7% if you're willing to accept more variance.
The percentages matter more than they look. A $2 million portfolio at 3.5% generates $70,000 a year. A $1 million portfolio at 4.7% generates $47,000. Different assets, different income, different lives.
Which one supports your lifestyle? That's the question worth asking, and it's a much better one than whether you crossed some round number on a statement.
Here's the flip side people forget. Chase $1 million when your spending needs $70,000 a year and you'll retire with a plan that doesn't work. Overshoot to $2 million when $45,000 covers you and you worked years you didn't have to.
So work backward. Figure out the income, pick a withdrawal rate you can sleep with, and let the portfolio target fall out of the math. If you're not sure which rate fits your situation, a fee-only planner can run the scenarios in an afternoon.
Income is the goal. The asset total is just the tool that gets you there.
Control Savings, Spending, and Diversification
You can't control daily markets, but you can control how much you save, how you spend it and how well your investments are diversified, and those three do most of the work.
Expect your investable assets to cross above and dip below seven figures in different years. That's normal, not a signal that something broke. A bad quarter can knock a headline number down while your actual plan is right on track.
So judge yourself on the levers. Are you saving a meaningful share of income? Is your spending roughly where you want it? Is your money spread across enough different holdings that one bad bet doesn't sink you?
Those are answerable questions, and you can act on all three this month. Market direction isn't one of them.
One practical note: keep contributing on a schedule regardless of what the market is doing. Automating the transfer removes the temptation to wait for a better moment, and better moments are only obvious afterward.
Markets will rise and fall. What matters is that the direction of your progress stays up, and that's decided by the choices you make, not the ones the market makes.
Location and Health Care Change Your Number
Your location swings what $1 million is actually worth, and by a wide margin. The same $1 million that feels generous in Ohio can feel tight in California, because what you're really buying is a lifestyle, and lifestyles are priced locally.
A million in the Midwest is very different from a million in New York City. Rent, groceries, property taxes, insurance, even a haircut come with a local price tag, and those tags add up over a 25- or 30-year retirement. So the balance in your account tells you less than the income that balance has to cover where you actually live.
That's why cost of living should adjust your income target, not just your portfolio balance. If your spending pattern needs $60,000 a year in Ohio, the same life in a high-cost metro might need $90,000 – and suddenly your $1 million is stretched thin. Run the numbers for your specific location before you decide your number is enough.
Health care can move the spending side just as hard. Medicare premiums, out-of-pocket costs, and long-term care can eat into a budget fast, and those costs don't look the same everywhere. Factor them in before you declare victory.
The fix is simple. Price out your actual town, add a realistic health care line, and see what income the math demands. If the gap is uncomfortable, a cheaper location or a bigger cushion is a decision you can still make.
The Real Goal Is Lifestyle Freedom
The real takeaway from all these millionaire numbers is simpler than the numbers themselves: freedom, not a seven-figure line. Everything else is context.
So before you take any headline at face value, ask what it counts. That 18% figure includes the house, which means a lot of those millionaires have most of their wealth in walls and a roof. And that 3% figure only looks at retirement accounts, so it misses brokerage accounts, savings, and everything else outside a 401(k). Neither one tells the full story, and neither one is a verdict on you.
Which means you should measure yourself against your own goals, not against a threshold someone picked because it sounds round. The goal was never crossing a magic seven-figure line. It's what your investable assets can actually do for you once you stop working.
Picture two people with the same $800,000 portfolio. One has a paid-off $200,000 house and a modest lifestyle; at a 4.7% withdrawal rate that's nearly $38,000 a year, plus no mortgage. The other still owes on an $800,000 home and pulls a little over $9,000 from the portfolio. Same headline wealth, completely different lives.
A concrete next step: write down what your ideal month costs, then divide your investable assets by that annual figure. That ratio is your real retirement number, and it's far more useful than a million-dollar marker.
The people who feel secure in retirement usually aren't the ones who hit a number. They're the ones who know what their money buys them, month to month, and built the life they actually wanted.
Frequently Asked Questions
Does the 18% millionaire statistic include home equity?
Yes. The 18% figure from the Federal Reserve's Survey of Consumer Finances includes home equity along with all other assets. It's a net worth measure, not an investable wealth measure.
What percentage of retirees have $1 million in investments excluding their home?
About 20% to 25% of retiree households have $1 million or more in investable assets outside their primary residence. That's roughly one in five, or around the 78th percentile.
How many retirees have $1 million in a 401(k) or IRA alone?
Only about 3% of retirees have $1 million or more in retirement accounts alone. But this is likely an undercount because people often have multiple accounts across different institutions that aren't combined in the data.
Why is it so hard to count how many millionaires there are?
Wealth is fragmented across many accounts and institutions, there's no central reporting requirement, and surveys rely on self-reporting. Wealthy households often underreport or refuse to give exact values.
How often should I track my net worth?
Quarterly check-ins give you a clear view of progress without overreacting to market noise. Once a year, do a full deep dive updating all accounts, assets, and debts for a year-over-year comparison.
Your two numbers tell the story headlines can't
Here's the decision rule: check your own two net worth figures—one including your home, one excluding it. Then compare the excluding-home portfolio's sustainable after-tax income with your expected spending. That's the number that matters.
The percentile is context, not a verdict. Whether you're in the top 20% or the top 10% doesn't change what you need to live the life you want. Use the statistics to orient yourself, then focus on your own goals.
So the next time you see a headline about millionaires, ask what's included and what's excluded. And more importantly, ask what that wealth can do for someone's life. In the end, it's not about the number. It's about freedom, security, and the life you want to live.
Check your own two numbers
Pull your latest statements and calculate your net worth both ways. The excluding-home figure is your true income potential.

Hello there! I’m Jesse Joe, the author and editor behind SolganGenius. I’m thrilled you’ve stopped by, and I can’t wait to share with you the essence of what this platform is all about.
I’m a writer, social media enthusiast, and a firm believer in the power of words. I’ve always been fascinated by how a simple phrase or slogan can capture an emotion, convey a message, and even change perspectives. Learn More