You probably think you know what Medicare covers. Doctor visits, hospital stays, maybe a flu shot. But the program also pays for things that make people say, 'Wait, really?'
I've seen it firsthand. A client once asked if Medicare would cover the special shoes she needed for her diabetic foot. She assumed it was a hard no. It wasn't.
The rules are full of odd corners, and they change every year. In 2024 and 2025, some big ones are shifting, especially around drug costs and mental health.
Here are nine services that surprise almost everyone, plus five new things for 2024 and beyond. Some are straightforward. Others come with fine print you need to know before you book.
Quick Tips Before You Start
Grab the Official Guide
The Medicare & You handbook lists everything covered for the year. Download it or ask for a paper copy.
Call Your Plan First
Before any appointment, ask the plan if the service is covered and what you'll owe.
Check Provider Enrollment
Make sure your doctor or therapist accepts Medicare assignment to avoid surprise bills.
Get It in Writing
Note the representative's name and date, or ask for an email confirmation.
1. Mental health coverage broadens for 2024
Unlike the drug-cost changes, which are brand new, mental health care was already inside Medicare – and 2024 just widens the door. The program now covers intensive outpatient programs and lets you see marriage and family therapists plus a broader range of counselors, so the help you can actually book looks a lot more like real life.
So what counts as 'intensive outpatient'? It's a structured program for someone who needs more than a weekly talk session but doesn't need to be in a hospital – think several visits a week with group and individual sessions woven together. That middle layer between office visits and inpatient care is exactly where a lot of families get stuck, and now it's a covered setting.
Here's the catch, and it's a real one: the setting and the provider type decide what gets paid. A licensed clinical social worker may well be covered while a pastoral counselor may not be. Before you book, ask two things – 'Do you accept Medicare, and will you bill this as mental health treatment?' That one phone call can save you hundreds of dollars and a nasty surprise.
💡 Tip: Ask if the therapist is a participating Medicare provider. If not, you may be responsible for the full cost.
| Feature | Original Medicare | Medicare Advantage |
|---|---|---|
| Mental health therapy | Covered, including intensive outpatient programs | Covered, but may need prior authorization |
| Part D drug cap | $8,000 in 2024, $2,000 in 2025 | Same cap, but plans can differ |
| Insulin | $35 per 30-day supply | $35 per 30-day supply |
| Telehealth | Expanded through 2024 | Covered, but network rules apply |
| Hearing aids | Not covered | Some plans offer extra benefits |
| Foot care | Covered for diabetes-related problems | Covered, but may need referral |
| Chiropractic | Covered for spinal manipulation | Covered, but network restrictions |
| Acupuncture | Only for lower back pain | Check plan-specific coverage |
| Glasses after cataract surgery | One pair of standard frames | Varies by plan |
| Foreign travel | Not covered outside US territories | Emergency coverage may apply |
2. Part D caps drug costs and insulin at $35
The biggest cost news in years sits in Part D. In 2024, once your out-of-pocket spending on covered drugs reaches $8,000, you pay nothing for the rest of the year – a true cap, not a temporary discount – and in 2025 that cap drops to $2,000.
Walk through it with real numbers. If your combined cost-sharing runs about $1,350 a month, you'll hit $8,000 sometime in June. From July through December, your covered drugs cost $0. That's the difference between budgeting for the whole year and budgeting for half of it.
Insulin gets its own rule: $35 total per 30-day supply, no deductible, and it's mandatory for all Part D plans starting 2024 after an optional savings program in 2021. Read that carefully – it's per 30-day supply, not per pen or box, so a plan quoting you $35 on a single pen isn't the same promise.
The catch: the cap only applies to covered Part D drugs, so check your plan's drug list and the current Medicare & You guide before you count on a figure, because these rules can shift.
💡 Tip: Keep a running total of your drug costs. Once you approach $8,000, ask your plan for a breakdown.
The numbers that hit your wallet
3. Vaccines stay covered and telehealth rules shift
That same 'check the fine print' habit carries straight over to vaccines, where the news is actually reassuring. Flu, hepatitis, pneumococcal and coronavirus shots stay covered with no cost-sharing, exactly as before.
The newer piece is COVID antivirals like Paxlovid: from 2025 Medicare must cover them, but which drugs and exactly how is still being worked out, so don't assume it's automatic yet.
Telehealth is the moving target. Expanded visits continue through 2024, but rules change for the following year, and coverage depends on where you are and what the visit is for. Check the current Medicare & You guide and your plan rather than guessing.
4. Hearing, vision, foot, spine and acupuncture have narrow rules
Picture the morning you realize the TV has crept up to volume forty and you're still leaning forward – that's when the hearing questions start. Medicare covers one diagnostic hearing exam a year if a doctor orders it to check a medical problem. Hearing aids and the fitting exams that go with them are not covered.
Vision follows the same logic. A glaucoma screening every 12 months is covered for people at high risk, but a routine eye exam for glasses or contacts is not. It's coverage aimed at disease, not at everyday aids.
Feet get more generous treatment. Medicare pays for diabetes-related foot problems, lower-leg nerve damage, limb-loss risk and medically necessary injury care, plus conditions like hammer toe, bunion deformity and heel spurs – the kind of thing that makes walking miserable.
Chiropractic is covered only for spinal manipulation to correct a subluxation, and acupuncture only for lower back pain – not allergies, not skin conditions, not general wellbeing. Here's the practical move: ask your doctor for the exact diagnosis and the exact service name, then call your plan and ask whether that specific service is covered before you go.
💡 Tip: Ask for the diagnosis code and the procedure code. That's what the billing office uses to check coverage.
⚠️ COMMON MISTAKE
Don't assume 'covered' means 'free'
Even covered services can carry a 20% coinsurance under Original Medicare. Always ask what you'll owe after Medicare pays.
5. Weight-loss surgery is covered when medically justified
If those narrow rules feel like Medicare only pays for disease, weight-loss surgery is the proof that it does – obesity counts as a disease, and bariatric procedures like gastric bypass and laparoscopic banding can be covered when they're medically justified.
The whole game is that phrase. Your doctor has to document that your health is at risk and that other weight-loss methods haven't worked, so the surgery is treating a condition, not trimming a waistline.
Before you schedule anything, confirm the hospital and surgeon participate in Medicare, and ask for the exact procedure name, the diagnosis code and whether prior authorization is required. This is a big step, so get the plan's answer in writing before you commit.
What to confirm before any procedure
6. Smoking-cessation counseling covers eight visits a year
The answer is up to eight face-to-face counseling visits in a 12-month period. Not phone calls, not a quitline chat, not an app. Actual visits, in person, with a trained professional.
That's eight chances to sit down with someone who knows how to help you stop, and it's built into the benefit whether or not you ever use it. Smoking is still the leading cause of preventable disease, so this isn't a small thing. The catch is in the paperwork, not the coverage. The visits have to be with a provider who is enrolled in Medicare, and they have to be billed correctly.
Before you book, ask the counselor's office two plain questions: do you accept Medicare, and will you bill this as smoking cessation counseling? If they hesitate on either one, keep looking. The benefit exists but it only reaches you if the billing is right.
Then track your window. The clock starts from your first visit, not from January, so write that date down somewhere you'll see it. A quick example: your first visit is in March, which means your eight visits run through the following February. If you use three and drift off, you don't carry five into next spring.
If you've never used any of this, you haven't lost anything yet, and starting now is as simple as calling your doctor and asking for a referral to a quit-smoking counselor.
💡 Tip: Ask if the visits are covered as preventive, which often means no copay.
Smoking cessation benefit: the fine print
📝 Who orders it
Doctor referral needed
🚫 What if you use 3 and stop
5 visits forfeited
📵 Visits that don't count
Phone, app, quitline
☎️ First step
Call your doctor for a counselor referral
The exact question to ask
Will you bill this as smoking cessation counseling under Medicare?
7. One pair of standard glasses follows cataract surgery
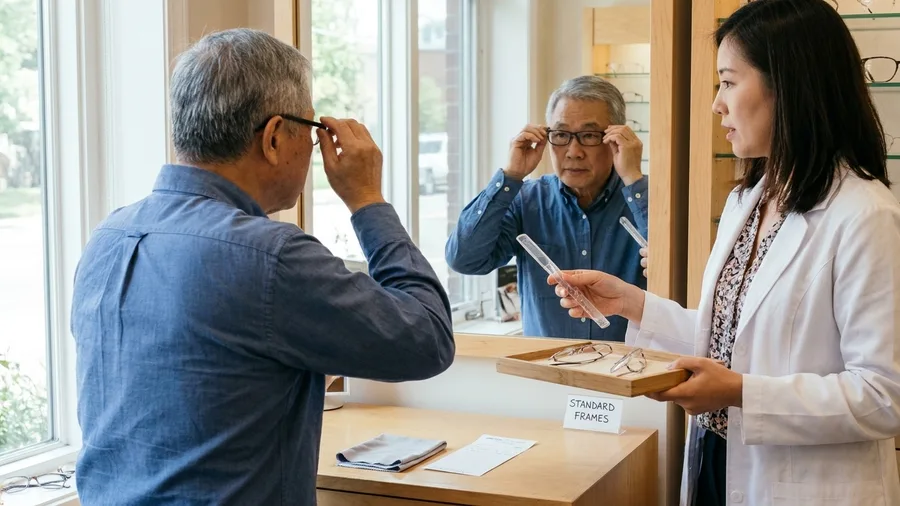
Unlike counseling, which you have to actively ask for, this next one often arrives without anyone mentioning it, and it comes with a very specific limit. After cataract surgery, Medicare covers one pair of ordinary eyeglasses with a standard frame. Designer frames? Not covered. Those are on you.
The surgery itself is covered, and so are the basics of getting your sight back. What isn't covered is upgrading the lens implant during surgery for close or distance correction. That's a separate choice, and you'd pay for it. The glasses benefit kicks in when the surgery changes your vision and you still need correction afterward, which is common.
Here's the practical sequence. After surgery, ask the surgeon's office who bills the glasses benefit, because it isn't always obvious. Ask for the standard-frame rule in writing before you order anything, so a nice pair of frames doesn't turn into a surprise bill.
And if your cataract surgery was years ago rather than months, ask your plan whether the benefit is still available for that eye. It might be. One phone call answers it.
💡 Tip: Choose a standard frame from the approved list to avoid extra cost.
8. STI screening and counseling are covered
We've been walking through benefits that come with tight rules attached, and this one is the same story with a topic people rarely bring up at the pharmacy counter. Medicare covers screening and counseling for sexually transmitted infections, specifically chlamydia, gonorrhea, syphilis and hepatitis B.
The reason that matters is simple: people over 65 remain sexually active, so this benefit isn't only for younger patients. Your doctor can order the tests if you have a concern, and the counseling is part of the package rather than an extra.
There's one question worth asking at the desk, and it's about how the test is ordered. Ask whether it's being billed as screening or diagnostic, because that distinction can change what you pay. Screening often comes at no cost to you, while diagnostic testing may carry a copay.
Use a lab that participates with Medicare, and ask what the counseling visit actually includes. Think of it as a conversation with your doctor, not a lecture.
9. Medicare covers US territories but not foreign travel
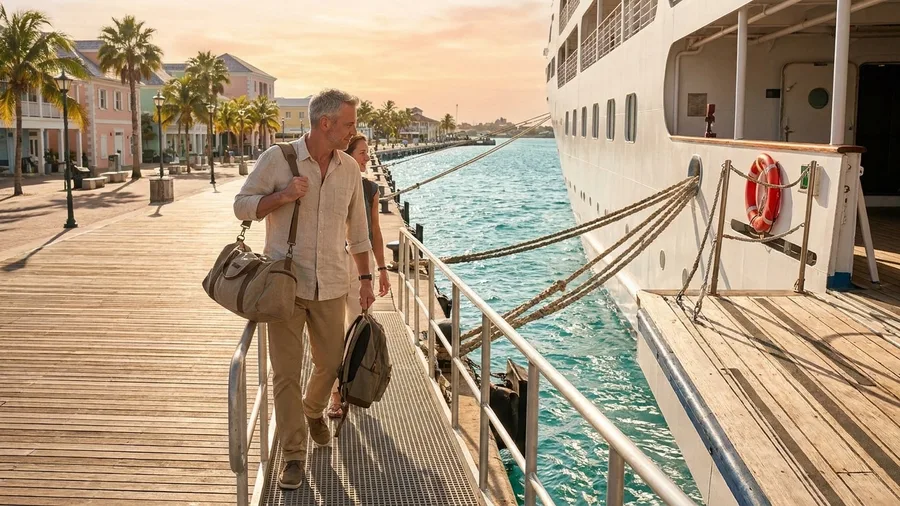
Picture the moment: you're on a cruise in the Caribbean, you slip on a wet deck, and the ship's doctor is stitching your arm while someone asks about your insurance. That's the moment to know this rule cold, because Medicare stops at the water's edge.
The covered map is the 50 states, the District of Columbia, Puerto Rico, the US Virgin Islands, the Northern Mariana Islands and American Samoa. That's the whole list. A trip to Canada or Mexico, or a cruise that docks anywhere else, falls outside it, and Medicare won't pick up the bill.
Territories and foreign travel get confused constantly, so keep them separate in your head. If you're heading abroad, look at travel insurance or a Medicare Advantage plan that includes foreign emergency coverage before you pack. And even inside the covered area, Advantage plans can have network rules, so check your specific plan rather than assuming.
A quick example makes it concrete. A week in Puerto Rico sits inside the list, so your coverage travels with you. The same week in Jamaica doesn't, and a hospital visit there could cost you thousands out of pocket. Same sunshine, very different answer.
One phone call to your plan before you book the trip settles it.
💡 Tip: Before any international trip, call your plan and ask about foreign coverage. If none, buy travel insurance.
How to check one service before you book it
You've read through the list, and now you're staring at a specific appointment wondering whether it's covered for you. Here's how to get a real answer instead of guessing.
Start with your doctor. Ask for the exact diagnosis and the exact name of the service or test. That's your foundation, and it's what every call after this is built on. Vague questions get vague answers.
Then call your plan. Ask for the coverage rule for that diagnosis and service, and ask whether prior authorization is needed. Before you hang up, either have them email you the answer or write down the representative's name and the date. If something goes wrong later, that note is worth more than a memory of a phone call.
Next, call the provider's billing office. They know the codes they'll use and can tell you what to expect on your side. They do this every day.
For the official word, go to the current Medicare & You guide and your plan's Evidence of Coverage. Those are the documents that decide disputes, so keep them handy.
Free screenings still leave some cost-sharing
Covered and free are two different words, and Medicare keeps them in separate rooms. That distinction is the whole ballgame here.
Preventive services are where you get the break. A glaucoma screening every 12 months for someone at high risk, for instance, typically comes with no cost-sharing at all. Medicare is paying you to catch trouble early, so it picks up the tab.
Diagnostic is the other word. The moment a test is ordered to investigate a symptom you already have, the mood changes. Under Original Medicare, diagnostic tests and treatments usually leave you with the standard 20% coinsurance, with no cap on what that adds up to.
So picture the same eye clinic, two visits. One is the annual glaucoma screening, free. The other is a diagnostic eye exam for a specific problem you noticed, and that one may carry a copay. Same building, different bill, and it all hinges on why the test was ordered.
That gives you two questions to ask before you book anything. First: is this preventive or diagnostic? Second: what will I owe after Medicare or my plan pays?
If you're in a Medicare Advantage plan, add a third check, because copays and network rules can differ from Original Medicare. Call the plan and get the number before the appointment, not after. A two-minute call beats a surprise envelope.
Original Medicare vs Medicare Advantage
Original Medicare
- Nationwide coverage
- No networks or referrals
- 20% coinsurance after deductible
- May need Medigap for gaps
Medicare Advantage
- Often lower premiums
- May include extra benefits
- Networks and prior authorization
- Copays vary by plan
Frequently Asked Questions
Does Medicare cover marriage and family therapy?
Yes, starting in 2024, Medicare covers marriage and family therapists and other counseling types. Make sure the therapist is enrolled with Medicare and bills the service as mental health care.
Is insulin really $35 per month?
Yes, under Part D, a 30-day supply of insulin costs $35 total, with no deductible. This is mandatory for all Part D plans starting in 2024. It's per 30-day supply, not per pen or box.
Will Medicare pay for hearing aids?
No, hearing aids and fitting exams are not covered. However, Medicare covers one diagnostic hearing exam per year if a doctor orders it to check for a medical problem.
Does Medicare cover glasses after cataract surgery?
Yes, one pair of standard-frame eyeglasses after each cataract surgery is covered. Designer frames are not covered, and you may need to pay extra for upgraded lenses.
Is acupuncture covered for anything?
Only for lower back pain. Other conditions like allergies or skin issues are not covered.
Does Medicare work in Puerto Rico?
Yes, Medicare covers Puerto Rico, the US Virgin Islands, the Northern Mariana Islands, and American Samoa, in addition to the 50 states and DC. It does not cover foreign countries.
The fine print that decides your bill
Most of these services are covered only when they're tied to a specific diagnosis, and the plan type decides the networks, prior authorization, and copays.
Original Medicare gives you broad choice but comes with 20% coinsurance. Medicare Advantage plans may offer extra benefits but often have networks and copays.
Your first action: get the exact service name and diagnosis code from your doctor, then confirm in writing with your plan before you book. That one step saves you from surprise bills.
Check Your Plan Before You Book
Call your plan today and ask about the specific service you need. Get the answer in writing, and keep it with your Medicare & You guide.

Hello there! I’m Jesse Joe, the author and editor behind SolganGenius. I’m thrilled you’ve stopped by, and I can’t wait to share with you the essence of what this platform is all about.
I’m a writer, social media enthusiast, and a firm believer in the power of words. I’ve always been fascinated by how a simple phrase or slogan can capture an emotion, convey a message, and even change perspectives. Learn More