Turning 55 isn't just another birthday. It's the year two things finally line up: access to your retirement money and the health to actually use it.
Most people assume early retirement means waiting until 59½ or 62 and hoping their knees hold out. But there's an IRS provision that changes the math at 55, and it's called the rule of 55.
It lets you pull money from your current employer's 401(k) or 403(b) without the 10% early-withdrawal penalty, provided you part ways with that employer during or after the calendar year in which you hit 55. Ordinary income tax still applies, but that penalty disappears.
The catch is that the rule has conditions, trade-offs, and a few ways to accidentally cancel it. This article walks through the 12 things that matter most, from plan rules to health insurance to tax brackets. By the end, you'll know whether 55 is your window or just a number.
Quick Tips Before You Start
Call HR first
Ask your plan administrator whether partial withdrawals are allowed after you leave.
Don't roll to an IRA
Moving your 401(k) to an IRA cancels the rule of 55 penalty exception.
Run a 30-year test
Use a free Monte Carlo tool to see if your plan survives a long retirement.
Price health insurance
Get quotes before you leave, because COBRA and marketplace plans are not cheap.
Mark your separation year
The rule applies only if you leave in or after the calendar year you turn 55.
1. 55 Lines Up Money Access With Your Best Health
Simple: it's the first age where you can reach your retirement money without the penalty and still have the body to enjoy it. Those two things rarely line up again.
At 45 you might have the money, but the 10% penalty makes pulling it out feel like paying a fee to touch your own savings. At 65 you can take it freely, but the long trips and the hiking and the late nights are already harder than they used to be. At 55, both are still in reach.
Split your thinking in two. On the money side, the rule of 55 can open your current 401(k) without the 10% early-withdrawal hit if you part ways with that employer during or after the calendar year in which you hit 55. On the health side, nothing opens automatically. Energy can slide without warning, and the rule itself still requires you to actually leave the job.
If you're burned out at 55 and your plan allows withdrawals, this is the year to sit down with the real numbers. Wait a year and you may still have the access, but you may not have the knees.
💡 Tip: Write down your top three retirement goals that require physical energy. If they all need to happen before 70, that's your case for 55.
💡 PRO TIP
The calendar year matters
If you turn 55 in November, you can leave in January of that same year and still qualify. The rule looks at the year you turn 55, not your exact birthday.
2. Leaving in Your 55th Year Waives the 10% Penalty
Picture the Friday you hand in your notice at 56, your paperwork is done, and you're wondering whether you can start drawing on the 401(k) next month without the penalty. That's exactly the moment the rule of 55 is built for.
It applies to your current employer's 401(k) or 403(b), and only if you part ways with that employer during or after the calendar year in which you hit 55. Retiring, quitting, or getting laid off all count. The rule doesn't care why you left, just when.
What it does is narrow: the 10% early-withdrawal penalty that normally applies before 59 1/2 goes away. Ordinary income tax still lands on every dollar you pull out, so a $30,000 withdrawal isn't $30,000 in your pocket. Run the tax hit before you count that money.
💡 Tip: If you leave in the year you turn 54 and wait until the next year to withdraw, you may still qualify because the separation happened before the year you turn 55. Check with a tax pro first.
| Feature | Rule of 55 | 72(t)/SEP |
|---|---|---|
| Eligible accounts | Current employer's 401(k) or 403(b) | IRAs and some employer plans |
| Trigger | Leave the job in or after the year you turn 55 | Any age, but must set up a fixed schedule |
| Withdrawal flexibility | Withdraw as needed, no set amount | Fixed schedule, cannot be changed |
| Duration | Until you roll the money to an IRA | At least five years or until age 59½ |
| Taxes | Ordinary income tax; 10% penalty waived | Ordinary income tax; 10% penalty waived if rules followed |
3. Keeping the Money in the Plan Preserves the Rule
The fastest way to lose the rule of 55 is to move the money. Roll that 401(k) into an IRA and the exception is gone, and you're back to the 10% penalty unless you set up 72(t) payments.
It also only reaches your current employer's plan. Old 401(k)s from previous jobs don't qualify, even if you're well past 55. Some plans let you roll old accounts into your current one, but that has to happen before you leave the employer, not after.
Then there's the withdrawal question. Not every plan allows partial withdrawals after you separate. Some make you take a lump sum or move everything out, which can dump a huge tax bill on you in one year. So call HR or the plan administrator and ask directly: "If I leave at 55, can I take partial withdrawals from the plan?"
Get that answer in writing. A friendly verbal yes from a rep won't hold up when six figures are on the line.
If the plan says no, the rule of 55 is useless to you, and you'll need a different bridge to get from leaving work to age 59 1/2.
💡 Tip: Ask for the summary plan description. The withdrawal rules are in there, and you can read them before you give notice.
4. An IRA Uses 72(t) and a Fixed Five-Year Schedule
There's another penalty exception, and it's called 72(t), also known as substantially equal periodic payments or SEP.
The catch is that it has to be a fixed schedule. You take payments at a set amount on a set rhythm, and they must continue for at least five years, and not change once you start. Break the schedule and the IRS can hit you with penalties on every withdrawal you've already taken.
The formulas are picky, so talk to a CPA or planner who has set these up before. Before you commit, weigh it against leaving the money in your current 401(k) under the rule of 55, where you're not locked into a fixed amount for five years.
5. The 55-to-65 Decade Is Your Most Active Window
The 72(t) route locks you into a fixed schedule, but the clock is working the other way too. Money is only half the picture, and the years from 55 to 65 frequently bring the most active, capable stretch of retirement you'll get.
You're likely at your strongest and most energetic. If you want to travel, spend time with family, take on passion projects, or start a business, this is the window where those plans are actually realistic.
The retirement spending smile explains why: people spend more early on travel and experiences, spending declines in the middle, then rises later with health care. The trip you'd love at 58 is a different trip than the one you could manage at 75.
What the 55-to-65 window gives you
Use it now
- Travel that requires hiking, walking, and energy
- Time with grandchildren while they're young
- Starting a small business or passion project
- Taking a gap year while health is on your side
Waiting can cost
- Health issues that limit long trips
- Energy levels that drop after 65
- Family time lost to work schedules
- Projects that never get started
6. Retiring Early Costs Compounding and Stretches the Payout
Access is only half the story. The other half is what that access costs you, because every dollar you pull out at 55 is a dollar that stops working for you.
Working longer usually means more money accumulated and more years of compounding. Consider $100,000 earning 6% across 10 years. It nearly doubles, all without you adding another cent. Leave that money alone and it quietly grows; withdraw it early and it stops compounding the moment it leaves the account. That difference is a real opportunity cost, and it's easy to underestimate when you're focused on the freedom of leaving.
Retiring early also stretches the timeline. A portfolio built for 20 years of retirement now has to last 30 to 40 years instead. The math changes from 'Will I have enough?' to 'Will it last long enough?'
Here's a quick illustration. Say there's $600,000 in the 401(k), you withdraw $30,000 a year, and the horizon is 30 years. That's $900,000 in withdrawals before any growth. The portfolio has to earn its keep just to survive.
Run these numbers with realistic assumptions before you give notice, not after. Knowing the cost doesn't mean you can't retire at 55. It means you make the choice with your eyes open instead of guessing.
💡 Tip: Use a free Monte Carlo tool like Bolden to see how often your plan succeeds under different market returns.
7. A Real Budget Adds Inflation, Property Costs, Health Care
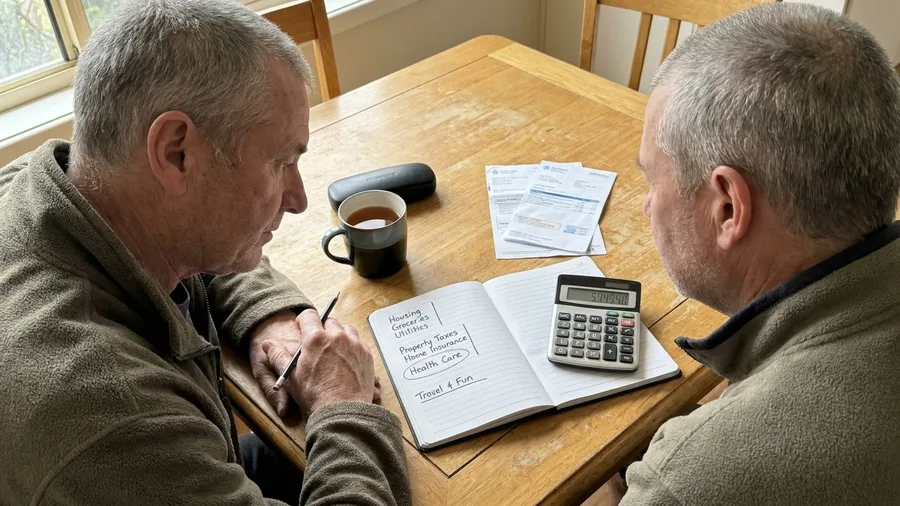
Start with the obvious: housing, transportation, groceries, utilities, and everything else you already pay for every month. Write it all down, because this is the base your early retirement runs on. Then add the lines people skip – and it's those skipped lines that blow up a retirement budget.
Even with the mortgage paid off, the house still costs money. Property taxes and home insurance don't vanish just because you own the place, and over 20 or 30 years of retirement those two lines alone add up to a serious number.
Adjust the whole budget upward for inflation. A dollar today buys less in 20 years, so if you frame your expenses in today's dollars and forget to grow them, your plan looks comfortable when it isn't. Health care goes on the list too, along with possible long-term care and a real travel or fun budget. That last one matters more than people think, because the go-go years are the whole point of retiring early.
Add it all up and set the total against your income sources. The gap is what you have to bridge – and that gap is your actual retirement number, not the one you guessed at the kitchen table.
Bridge Budget — At a Glance
🏠 401(k) withdrawal
$30,000/yr = 5% of $600,000
🚗 Qualifying plan
Current employer only; IRA rollover voids it
🩺 Health care timing
Bridge premiums out of pocket to Medicare at 65
✈️ Tax hit
Ordinary income tax due; 10% penalty waived
📈 Inflation buffer
Grow each line 3%/yr for 30-40 years
Example
$60,000 budget – $30,000 from the 401(k) = $30,000 from taxable, Roth, and HSA.
8. Bridge Income Must Cover Health Insurance Until Medicare
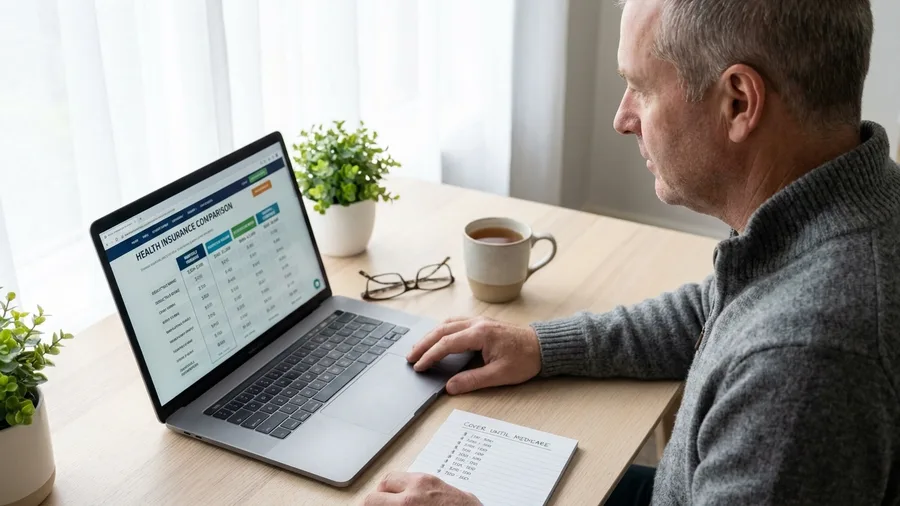
That gap is where the bridge comes in. Once you leave the job, the employer health coverage ends, and Medicare is still a decade away at 55. That gap is often the biggest surprise in an early retirement budget.
Roth accounts, tax-advantaged brokerage accounts, and an HSA can bridge your income until Social Security and Medicare start. An HSA is especially useful because it's triple tax-advantaged if you use it for qualified medical expenses.
To size the gap, use Vanguard's health-care cost estimator. It gives you a realistic range for premiums and out-of-pocket costs based on your age and health.
For the full plan, run a Monte Carlo simulation with a free-to-try tool like Bolden. It shows you the probability your money lasts, not just a single guess.
💡 Tip: Check whether your employer plan allows you to keep coverage through COBRA and what the monthly premium would be. It's often higher than a marketplace plan.
⚠️ COMMON MISTAKE
Don't forget the health-care gap
Leaving at 55 means a decade without employer coverage and before Medicare. Price marketplace plans and dental and vision before you set your budget.
9. A Long Retirement May Need 80/20 or 85/15 Stocks
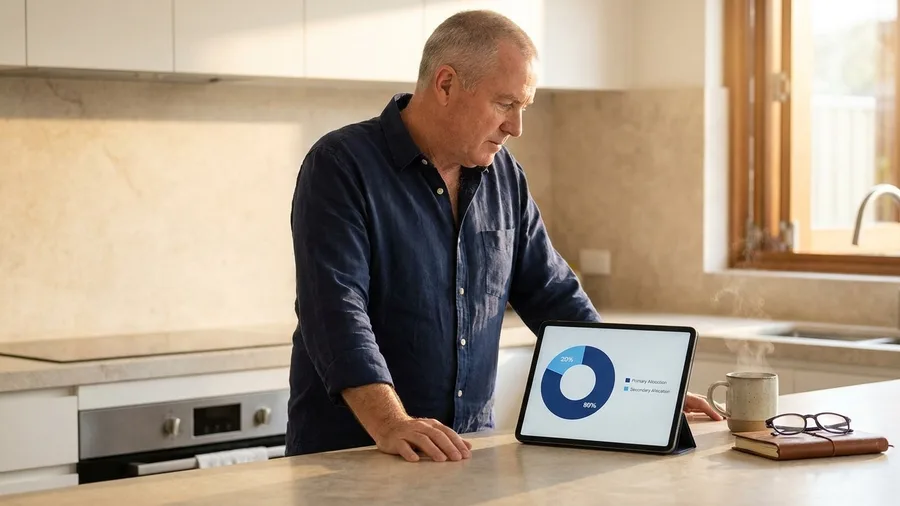
All of this changes what the portfolio itself has to do. The conventional advice is to shift more money into bonds or fixed income as retirement nears, but that yields much lower returns.
To keep a 30- to 40-year portfolio going while staying ahead of inflation, you may need 80/20 or 85/15 stocks to bonds instead of the classic 50/50. That's a big shift from what most people expect, and it's the price of a long horizon.
The bigger stock allocation isn't free. It adds greater risk, and a bad market early in retirement can do real damage if you're selling stocks to fund withdrawals.
A common approach is to keep one or two years of spending in cash or short-term bonds so you don't have to sell stocks in a downturn. That way a bad year early on doesn't force you to sell at the worst moment.
So the long horizon pulls in two directions at once: more stocks to last, less forced selling to survive. Your job is to hold both truths at the same time.
Common myths about retiring at 55
10. 401(k) Withdrawals Fill Brackets and Crowd Out Roth Room
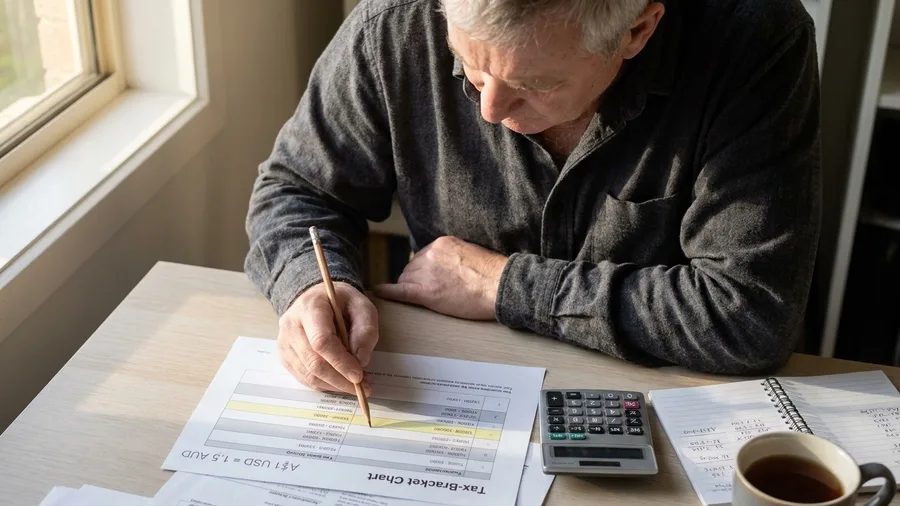
Withdrawals count as ordinary income, which affects more than just your tax bill.
Early retirees often use low-income years to convert pre-tax dollars to Roth. In a typical example, income dips at age 64, and the person can convert just enough to fill the first bracket without spilling into the next.
But substantial 401(k) withdrawals can bump you into a higher bracket and limit how much room you have for those Roth conversions. That's the trade-off: money to live on today versus tax-free growth later.
Plan the withdrawal amount with your bracket in mind, not just your checking account.
11. Rule of 55 Is a Bridge, Not a Lock
The 72(t) route locks you into a fixed schedule you can't touch. The rule of 55 asks nothing of the kind. There's no required withdrawal amount and no timetable to follow. You pull what you need, when you need it, and skip a year entirely if your bank account allows it.
You do have to leave the current job to switch it on, but that's where the obligation ends. Take twelve months off, drop to part-time, start a small business, or go back to work somewhere else later. The rule doesn't care. It's a bridge, not a retirement contract.
That matters because the window is short. Money you can reach without a penalty during a stretch when your body and stamina still allow the lifestyle you want is worth more than the same money at 65. Check your plan document for partial withdrawal terms before you count on it.
12. Plan Rules and the Math Come Before the Paycheck
Picture the moment the email goes out: resignation drafted, date picked, a countdown running in your head. That's precisely the moment to slow down and make two calls instead of one.
Start with HR or your plan administrator. Ask, plainly, whether the plan allows partial withdrawals and how they're processed. Get the answer in writing, because front-line staff sometimes give the general version rather than your plan's version.
Then run the numbers before you give up the paycheck. Your budget, health-care costs, taxes, and a Monte Carlo simulation that shows how the portfolio holds up across thousands of market paths. If the math only works in a good year, it doesn't work.
And put time and health in the same spreadsheet as the money. You can recover a bad return. You can't make more years. Treat all of this as education, then let a CPA or financial planner look at your actual situation and tell you honestly whether 55 is realistic.
💡 Tip: Bring three questions to your HR call: Can I take partial withdrawals? What are the fees? Can I roll old 401(k)s into this plan before I leave?
Frequently Asked Questions
Can I use the rule of 55 if I quit instead of retire?
Yes. The rule applies if you leave the job in or after the year you turn 55, whether you retire, quit, or are laid off. The reason for leaving doesn't matter.
What happens if I roll my 401(k) to an IRA at 55?
The rule of 55 no longer applies once the money is in an IRA. You'd lose the penalty exception and would need to use 72(t) or wait until 59½.
Does the rule of 55 apply to my old 401(k) from a previous job?
No. Only your current employer's 401(k) or 403(b) qualifies. Old 401(k)s from prior jobs don't, unless you roll them into your current plan before you leave.
Do I still pay taxes on withdrawals under the rule of 55?
Yes. You pay ordinary income tax on every withdrawal. Only the 10% early-withdrawal penalty is waived.
Can I use the rule of 55 and then go back to work?
Yes. The rule doesn't require you to stop working forever. You can take time off, work part-time, start a business, or return to a full-time job later.
What if my plan doesn't allow partial withdrawals?
Then the rule of 55 won't help you take money out gradually. You'd need to look at 72(t), a different plan, or waiting until 59½.
The decision rule for leaving at 55
Use the rule of 55 only when three things are true: your plan allows partial withdrawals, your budget survives a 30- to 40-year horizon, and your health-insurance bridge is funded.
If any of those is missing, wait, use 72(t), or work part-time until the gap closes. Retiring at 55 is a calculated choice, not a leap.
There's always a way to earn more cash. There's no way to earn more time. Make the call with the numbers in front of you.
Check your plan before you give notice
Call your plan administrator today and ask whether partial withdrawals are allowed. That one answer decides whether the rule of 55 is your bridge or a dead end.

Hello there! I’m Jesse Joe, the author and editor behind SolganGenius. I’m thrilled you’ve stopped by, and I can’t wait to share with you the essence of what this platform is all about.
I’m a writer, social media enthusiast, and a firm believer in the power of words. I’ve always been fascinated by how a simple phrase or slogan can capture an emotion, convey a message, and even change perspectives. Learn More