How much can you hand your kids or grandkids before the IRS wants a form back? That is the question worth settling before you write another check.
Picture the year as it usually happens: a cash gift to an adult child, another to a grandchild, then a tuition bill paid straight to the school and a hospital bill paid straight to the hospital. The checks clear, so it feels finished. It isn't. Gift tax isn't one number to memorize. It's a sequence of buckets plus a filing question, and the amount and the conditions live in current IRS sources, not in anyone's memory.
The aim is narrow and real: help your family without accidentally creating a gift-tax filing problem, even if you have never heard of Form 709. Read this before your next transfer and again at tax prep, and each gift becomes a bucket you check rather than a surprise you explain.
| Bucket | What it covers | What to verify | Official source |
|---|---|---|---|
| Annual exclusion | Cash gifts to one person in one calendar year | The current per-recipient limit and which calendar year the gift falls in | IRS Gift Tax page |
| Lifetime exemption | Gifts above the annual exclusion amount | How the exemption is used and reported | Current IRS Instructions for Form 709 |
| Direct tuition and medical | Payments made straight to a school or hospital | Whether the payment qualifies as a direct payment rather than a reimbursement | IRS Gift Tax page and Form 709 instructions |
| Form 709 | The gift tax return itself | Whether your gift requires filing and the current deadline | Current IRS Instructions for Form 709 |
| Records | Proof of what you gave, to whom, and when | Date, recipient, amount, asset, transfer method, purpose | Your tax preparer and IRS guidance |
| Professional help | Property, loans, business interests, state residency, large exemption questions | Whether the situation has moved past simple cash | A CPA or estate attorney |
The Annual Exclusion Is the First Bucket
The amount you can give each family member without gift tax is set by the annual exclusion, and the current IRS Gift Tax page is where that number lives. Pull it from the source, not from a figure someone quoted at a family dinner three years ago.
The annual exclusion is the first IRS term to look up, and it comes with two moving parts worth understanding before any check goes out. One is the recipient: who counts as a person for the exclusion. The other is the calendar year: which year the gift actually lands in, because a transfer dated December 31 and one dated January 2 are different questions.
Run it as a per-person check, not a family total. Take the case of a parent who writes one cash gift to an adult child and another to a grandchild in the same calendar year. That is two recipient-year pairs, each with its own exclusion check. It is not one pooled pot the parent divides however they like. The grandchild's gift does not eat into the adult child's room, and the adult child's gift does not shrink the grandchild's.
Change either variable and you rerun the source. A new person (a new grandchild, a daughter-in-law, a niece) or a new calendar year means the question resets and you check the IRS figure fresh. Reusing last year's number because it is what you remember is exactly how people drift out of step with the rules.
One more boundary. The IRS page is the starting authority, but state tax rules are separate. If the giver lives somewhere with its own gift or estate provisions, the state tax authority where they live is the second place to check.
⚠️ COMMON MISTAKE
The calendar year changes the answer
A gift given in December and a gift given the following January are two different calendar-year events. Before you assume you are under the limit, confirm which year each transfer actually posted to the recipient's account.
The Lifetime Exemption Is the Backstop
A gift bigger than the routine per-person amount does not vanish and does not automatically trigger a tax bill. It bumps into the lifetime exemption, which sits behind the annual exclusion as a backstop, with its controlling details in the current IRS instructions.
Here is the shape of it. Suppose the same parent gives the adult child a cash gift larger than the annual-exclusion amount in one calendar year. The portion that exceeds the exclusion does not just evaporate. It goes against the lifetime exemption, and that is the point where a Form 709 reporting check enters the conversation under the current IRS instructions.
Reporting question, not a tax invoice. That distinction matters, because plenty of people hear the word exemption, assume a bill is coming, and either panic or ignore the whole thing. Neither helps. What actually happens depends on the instructions, and the instructions are the authority.
Do not run the numbers from memory. How the lifetime exemption is used and reported belongs to the Form 709 instructions, not to a figure recalled from an article or a conversation. Read the current version before you decide what to do.
One thing the writer got wrong early on: treating a large gift as a one-time event. Using the lifetime exemption builds a cumulative record across years. Each use stacks on the ones before it, which means the running total matters. Do not carry it in your head. Keep records year over year and let a preparer or the IRS instructions confirm where you stand.
Direct Payments Need Their Own Check
You may be able to pay a school or hospital bill directly without it counting against your gift limit the same way a cash gift does, but that treatment is a category to verify, not a loophole to assume. The current IRS conditions and limits decide whether a direct payment is treated differently from an ordinary gift.
The detail that triggers the separate check is the route the money takes. A parent sends a tuition bill payment straight to the school and a medical bill payment straight to the hospital in the same calendar year. Paying the provider directly is the fact that sends you to the instructions rather than the annual-exclusion math.
Reimbursing the family is not the same as paying the provider. Writing your adult child a check after they have already paid the tuition is a cash gift on paper, and treating it as identical to a direct payment without confirming the current IRS instructions can put you in the wrong bucket. Confirm before you assume the two are interchangeable.
Keep the evidence. A receipt or invoice naming the school or the medical provider is the core document here, and it should sit in the same file as the rest of the year's gift records. A cancelled check to a hospital with no invoice leaves a gap you will be filling from memory later.
The article prints no dollar limit and no condition for direct payments, because those live in the source. Check the IRS Gift Tax page and the current Form 709 instructions for direct-payment conditions before you write the check, not after.
🧾 Before you move the money
Identify the bucket
Decide whether the transfer is a routine cash gift, a larger gift, or a direct payment to a school or hospital.
Check the current IRS source
Look up the current figure or condition on the IRS Gift Tax page or in the Form 709 instructions before you transfer.
Confirm the calendar year
Note which year the gift posts to the recipient's account, because the year changes the exclusion check.
Make the transfer
Send the money directly to the recipient or the provider and keep the confirmation.
Record the gift
Write down the date, recipient, amount, asset, transfer method, and purpose in a file you can find later.
Review at tax prep
Bring the gift file to your preparer so the Form 709 question gets answered before the return is filed.
Form 709 May Be the Missing Step
Any gift that may not fit inside the annual exclusion sends you to Form 709, the gift tax return most people have never heard of, and the current IRS Instructions for Form 709 are what settle whether you actually have to file.
The form is not a tax bill and it is not a penalty. It is a reporting question, and the instructions tell you when the answer is yes. That matters because the filing triggers live in the instructions, not in a rule of thumb someone repeats at a birthday dinner. A number you half-remember from a decade ago is not a threshold, and it is not proof of anything. Read the instructions that are posted now, for the year the gift was made.
Run the example. A parent gives the adult child a cash gift larger than the routine per-person amount, and also pays a tuition bill straight to the school, all inside one calendar year. Either fact on its own is enough to send you into the instructions with a real question instead of a guess. You file only if the instructions say to file. Not because a forum said so, and not because the amount felt large.
Start at the IRS Gift Tax page, pull the current Instructions for Form 709 from the IRS, and check the state tax authority where the giver lives if a state question is in play. If a return is filed, keep a copy with the gift records. That copy belongs in the calendar-year file, and it becomes the record of how much of the lifetime exemption has already been used.
Records Make the Gift Defensible
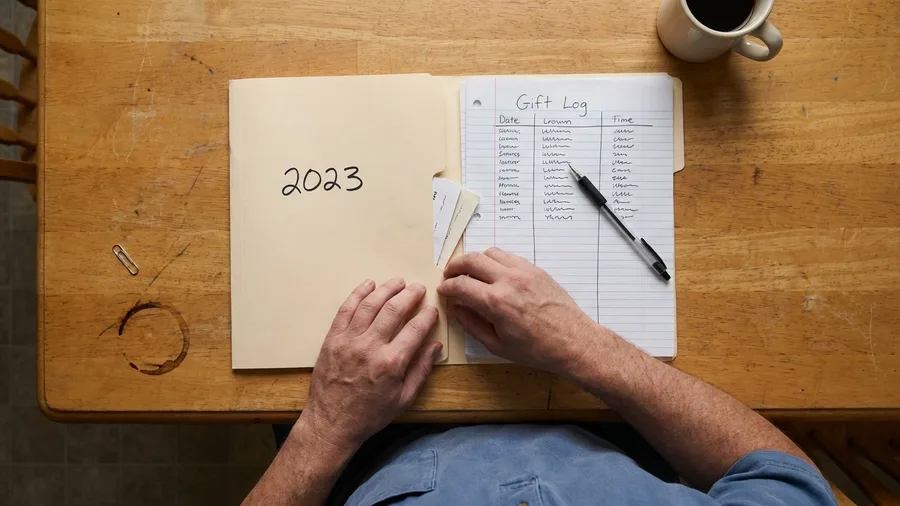
Every gift needs its own record, because whether Form 709 applies comes down to facts you can prove, not facts you remember.
One line per gift, and six things on that line: the date, who received it, the amount, what the asset was and what it was worth, how it moved (check, transfer, direct payment), and why it was given. A direct payment to a school or a hospital gets the invoice or receipt attached, with the provider's name right there on it. A cash gift to the adult child and one to the grandchild are two lines, not one generous blur.
File it by calendar year. Tie the folder to any Form 709 copy for the same year, and put a second look on the calendar for whenever the giver's tax return gets prepared. That is the moment a stray question surfaces while there is still time to answer it. If the giver is married and the gift is being split, keep the spouse's consent or the split documentation in that same folder, not in a drawer somewhere else.
How long to keep it all is not something to guess at. Ask the tax preparer, or follow IRS guidance, and keep it at least as long as they say. A scanned copy in one folder counts. The whole system costs an evening the first year and about two minutes per gift after that.
Keep it self-directed vs. call a pro
Can stay self-directed
- Simple cash gifts with complete records
- Gifts well under the annual exclusion
- Direct payments with the provider invoice kept
- A file you can hand to your preparer at tax time
Call a CPA or estate attorney
- Real estate, stock, or business interests
- Loans to family or forgiveness of a loan
- State-residency questions about gift rules
- Large gifts that raise a lifetime exemption question
Ask a Pro Before the Number Gets Big
Stop and call someone the moment the gift stops being cash, or the number gets near the exemption.
The triggers are specific: real estate, stock, business interests, a loan to a family member, a question about which state the giver actually lives in, or a gift large enough to raise a lifetime-exemption question. Those are the cases where a CPA or an estate attorney earns the fee, because the answer depends on numbers only they can see. Filings prepared without a fresh look are where repeated retiree tax return mistakes tend to hide. Clean records on a plain cash gift can stay self-directed and get a look at tax prep. A house cannot.
Bring the file. The gift records, any draft Form 709, the state-residency facts, and the documents on the asset itself. Walk in with that and the meeting is short.
One line worth knowing before the call: tax preparation is not legal estate planning. A CPA can prepare the return and advise on filing. An estate attorney handles the estate-planning and legal side. For state-residency questions, the state tax authority where the giver lives is the source to check, alongside that professional. Call before the transfer, not after the money has already moved and the question has hardened into a fact.
💡 PRO TIP
One file per calendar year
Label a folder with the calendar year and put every gift record, provider invoice, and Form 709 copy inside it. When your preparer asks about gifts, you hand over one folder instead of reconstructing a year from memory.
Frequently Asked Questions
How much can I give each family member without gift tax?
The annual exclusion is the first bucket to check, and it is a per-person, per-year amount. Check the current figure on the IRS Gift Tax page before you transfer, because the figure changes and last year's number is not this year's answer. Each recipient in each calendar year is its own check.
What happens if my gift is bigger than the annual amount?
The excess goes against your lifetime exemption and may need to be reported on Form 709. That is a reporting question, not an automatic tax bill. The current IRS Instructions for Form 709 explain how the exemption is used and reported, and they are the authority to read.
Can I pay school or hospital bills without using my gift limit?
Direct payments to a school or hospital are their own category, and you need to confirm the current conditions in the IRS Gift Tax page and the Form 709 instructions. Paying the provider directly is not the same as reimbursing the family, and the invoice or receipt naming the provider is the core evidence to keep.
What form might I need to file?
Form 709 is the gift tax return. The current IRS Instructions for Form 709 explain which gifts require it and what the deadline is. Get the current version from the IRS, file only if the instructions say so, and keep a copy with your gift records.
What should I keep after I give money?
For each gift, record the date, recipient, amount, asset and value, transfer method, and purpose. Tie the record to the calendar year, keep any Form 709 copy in the same file, and if you are married and splitting a gift, keep the consent or split documentation there too.
When should I stop DIY-ing this?
When the gift involves real estate, stock, business interests, loans, state-residency questions, or a large exemption question. Those are the situations where a CPA or estate attorney earns the fee. Simple cash gifts with complete records can stay self-directed and get reviewed at tax prep.
Check the Source, Then Move the Money
Before money moves, go to the current IRS Gift Tax page and the current IRS Instructions for Form 709. Those two sources settle the annual exclusion, the lifetime exemption, the direct-payment conditions, and whether a return is due for the calendar year you are in. Retirees who keep filing the same way often miss credits worth claiming, so know the tax breaks retirees forget too. If your state has its own provisions, check the state tax authority where you live.
The rule stays simple. Routine cash gifts with complete records can be handled on your own and reviewed at tax prep. Anything involving property, loans, business interests, state-residency questions, or a large exemption question goes to a CPA or estate attorney before the transfer.
So the parent with two cash gifts, a tuition payment, and a hospital payment stops assuming the cleared checks settle the matter. Each one gets its bucket checked and its receipt or invoice kept. That is how the filing problem gets avoided: identify the bucket, verify the source, keep the record, and hand off the complicated part early.
Before you write the check
Open the IRS Gift Tax page right now, look up the current annual exclusion, and start a calendar-year folder for your gift records. It takes ten minutes and saves the scramble at tax time.

Hello there! I’m Jesse Joe, the author and editor behind SolganGenius. I’m thrilled you’ve stopped by, and I can’t wait to share with you the essence of what this platform is all about.
I’m a writer, social media enthusiast, and a firm believer in the power of words. I’ve always been fascinated by how a simple phrase or slogan can capture an emotion, convey a message, and even change perspectives. Learn More