The break-even chart was the go-to tool for Social Security for years. Then the Social Security Administration pulled its own calculator over worries it was leading people to bad filing decisions.
That should tell you something. There are as many as 700 different filing strategies worth testing, and a single line on a graph is not one of them.
Let's meet Pat. Pat earned $90,000 in their last working year, has no spouse benefit to count, and is deciding when to turn on benefits. The numbers are simple: $2,238 a month at 62, $3,198 at 67, and $3,966 at 70.
If Pat lives to 84, claiming at 62 delivers about $615,000 in total. But that is $71,957 less than claiming at 67, and roughly $94,600 less than waiting until 70.
So why would anyone file at 62? Because the chart has assumptions baked in, and plenty of real lives break them. Here are seven situations where early filing wins.
Quick Tips Before You Start
Run your own numbers
Get your benefit estimates at 62, 67, and 70 from your SSA statement before you compare anything.
Be honest about health
Use a doctor-informed planning age, not a vague hunch, when you estimate how long benefits will pay out.
Check spousal and survivor rules
If you are married, confirm with SSA how your filing affects your spouse's benefit and any survivor amount.
Look at your whole balance sheet
Your portfolio, pension, and future taxes all change whether claiming at 62 actually leaves you ahead.
Estimate provisional income
Add up income that counts toward Social Security taxation so you know how much of your benefit may be taxable.
1. The Break-Even Chart Is Only a Starting Point
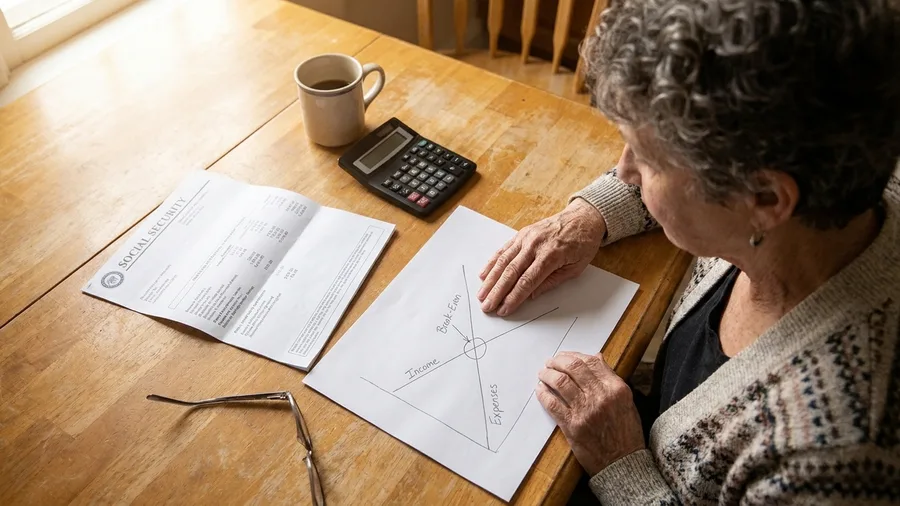
That number is real, but it rests on a pile of assumptions you never agreed to. The break-even chart was the old default for these decisions, yet the Social Security Administration pulled its own calculator over worries it was pushing people into poor filing choices. With as many as 700 filing strategies to test, a single line on a chart was never going to settle it.
Take Pat, who last earned $90,000. Pat's benefit is $2,238 a month at 62, $3,198 at 67 and $3,966 at 70. Claim at 62 and, with no cost-of-living adjustment and a planning age of 84, Pat collects about $615,000 in total, which leaves $71,957 less than claiming at 67 and roughly $94,600 less than claiming at 70.
Now stress-test it, one assumption at a time. Drop Pat's planning age from 84 to 81 and claiming at 67 wins. Drop it to 78 and 62 and 67 come out nearly identical, with 65 the best point in that example. Add cost-of-living adjustments back in at a planning age of 84 and the 62-versus-67 gap widens to about $168,000, while 62 versus 70 becomes roughly $246,000.
So what planning age do you use? If you reach 62 in reasonably good health with no family history of early death, use at least 84. That is the actuarial figure, and it is the one most people get wrong by planning too short. The real call takes three inputs: the break-even math, your own circumstances, and any other benefits your filing turns on. Context helps, too – the average US retirement age is 62, about two-thirds of retirees claim before full retirement age, and each year of delay raises your benefit by roughly 8%. If your savings aren't earning anywhere near 8%, delaying deserves a hard look.
💡 Tip: If your investments are returning well below 8%, delaying Social Security is effectively a guaranteed 8% annual raise. That's hard to beat.
| Claim age | Monthly benefit | Total received by 84 | Difference from claiming at 62 |
|---|---|---|---|
| 62 | $2,238 | $615,000 | — |
| 67 | $3,198 | $686,957 | +$71,957 |
| 70 | $3,966 | $709,600 | +$94,600 |
2. Poor Health Can Make Early Filing the Better Bet
Then the whole calculation bends, and this is the reason that matters most.
A higher monthly payment from waiting is only worth something if you live long enough to collect it. If your own health or your family history says you're unlikely to pass your break-even age, claiming early makes sure you get more of what you paid in.
Pat's numbers show how fast the verdict moves. At a planning age of 81, claiming at 67 wins. At 78, claiming at 62 and 67 land nearly identical, and 65 becomes the example optimum.
When health is poor, swap the 84 figure for a shorter planning age your doctor's input supports. Don't default to the actuarial table built around a healthy 62-year-old. And don't guess in either direction. The goal isn't predicting your lifespan perfectly. It's matching your filing age to a realistic estimate, then revisiting it as your health changes.
⚠️ COMMON MISTAKE
Don't Plan to the Average
The average life expectancy at birth is around 79, but if you've already reached 62, your life expectancy is longer—roughly 22 more years, to age 84. Planning to 79 can push you toward claiming early when waiting would have paid more.
3. Early Benefits Buy Time and Keep Savings Invested
Take less each month so you can enjoy retirement sooner and leave your savings invested. That's the trade, and it's one of the two most common reasons people give for filing early.
The enjoyment argument is straightforward. During the first part of retirement, people typically have the greatest energy and clarity to travel, chase hobbies or spend time with family. Money is meant to be enjoyed, and early benefits can fund experiences while you can fully take part in them, even if that means a smaller check and less comfort later.
The invested-savings argument is the practical one. If your other assets stay invested, claiming Social Security early lets them grow longer before you touch them. That advantage is strongest for singles with no dependents relying on their benefit.
Here's the rough math with Pat. Taking $2,238 a month for five years comes to about $134,000. At 67, Pat would get $3,198 a month, which is $960 more each month. The question is whether that extra monthly amount eventually overtakes the cash you took early.
Now the catch. The keep-savings-invested advantage vanishes if the benefit just raises your spending, or if you don't actually leave the portfolio alone. Pull the money out anyway and you've given up the larger check for nothing.
Personal finance is personal. A simple break-even chart is a starting point, not a verdict on your retirement.
— What financial planners keep repeating
4. A Spousal Benefit Can Start When You File
For married couples, all of that gets more complicated, because your filing decision isn't only yours anymore.
A spousal benefit can be up to 50% of the worker's full retirement age benefit, and a lower-earning or non-working spouse often can't access it until the worker files. So filing early can switch on household income that would otherwise sit locked away for years.
The trade-off is that filing early reduces both your monthly amount and your spouse's. You're swapping a larger later check for earlier household cash. This makes the most sense when there's a large earnings gap, or when a lower earner's own delayed benefit would never exceed half of the higher earner's benefit, because then delaying the lower earner's benefit buys very little.
Confirm spousal eligibility and timing with the Social Security Administration before you count on it. Not every spouse qualifies automatically, and the rules are specific.
💡 Tip: If one spouse earned much less, run the numbers on filing early for the lower earner while the higher earner delays. The combination often beats both filing at the same time.
5. A Survivor Switch Can Make Early Filing Compelling
There's a morning many couples reach: one spouse is sitting in a specialist's office, holding a diagnosis, and the filing question suddenly stops being theoretical.
The idea here is a switch. The lower earner files early on their own record, collecting something while both spouses are alive. When the higher earner dies, the survivor steps up to the survivor benefit, which is based on the higher earner's record.
This is the strongest early-filing case when the higher earner has a serious health issue. If the higher earner has a short life expectancy, turning on the lower earner's benefit early, collecting it while both are alive, then switching to the larger survivor amount later is close to a no-brainer.
It still requires weighing health and finances and timing the switch. And the survivor benefit isn't simply a copy of the higher earner's check in every case, so confirm the actual survivor amount with SSA before you rely on it.
The warning: if the higher earner lives longer than expected, the early-filing spouse may be locked into a smaller own benefit for longer. This is a hedge, not a sure thing.
When Early Filing Wins vs. When Waiting Wins
File at 62 when…
- Your health or family history suggests a shorter lifespan
- A spousal or survivor strategy needs the cash flow now
- A market drop makes selling investments costly
- Future income will push your benefit into higher taxes later
Wait past 62 when…
- You're in good health with no family history of early death
- Your savings aren't earning close to 8% a year
- You don't need the money to cover current expenses
- You want the largest possible survivor benefit for your spouse
6. Market Drops and Future Taxes Can Favor Claiming Now
Health is something you live inside; this next trigger comes from outside, and it shows up without warning. If you're drawing down a nest egg and haven't started Social Security, a steep market decline can be the moment to turn the benefit on. Recall the financial crisis or the days after 9/11, when stocks fell more than 50%. Filing then can spare you from selling beaten-down assets for groceries, giving the portfolio room to recover.
The tax side is quieter but just as real. Provisional income decides how much of your benefit is taxable, and above certain thresholds up to 85% can be pulled into the tax base. If that income is low today but pensions, annuities, or required minimum distributions after age 73 are on the horizon, claiming early can keep more of the check in your pocket.
Here's the catch, and it's a big one: this is still market timing and tax forecasting. Use it when the decline is real and the future income is genuinely likely, not as a bet that a crash is coming or a guess about what Congress does next.
Before filing on this reason alone, estimate your provisional income and confirm the treatment with the IRS or the SSA.
📋 Your Pre-Filing Checklist
Pull your SSA statement
Log in to your my Social Security account and print your benefit estimates at 62, 67, and 70.
Set a planning age
Use 84 if you're healthy with no family history of early death; use a shorter, doctor-informed age if not.
Check spousal and survivor rules
Call SSA and ask how your filing affects your spouse's benefit and any survivor amount.
Estimate provisional income
Add up the income that counts toward Social Security taxation so you know how much of your benefit may be taxable.
Compare the totals
Run the three scenarios side by side with your real numbers, not the generic chart.
7. A Cash Crunch Is a Valid Reason, With Caution
And when the markets and the tax math both say wait, life sometimes overrides all of it. If you need the money now, that is a real reason, and Social Security exists as a safety net. Unexpected medical bills, helping support a relative, or lacking sufficient savings to cover daily costs are all familiar cases. Turning the benefit on can give you the stability you need, and using it when you need it most is entirely acceptable.
The distinction that matters is a one-time bill versus an ongoing income gap. A temporary crunch may not justify a permanent cut to your monthly check. Say a $9,000 dental bill lands and your age-62 benefit is $2,238 a month versus $3,198 at 67. Covering that bill from savings or a short-term loan and leaving the benefit to grow often comes out ahead over twenty years, while a permanent monthly shortfall is a different animal.
Don't decide from fear or speculation, either. Lay out every option and remember that what fits your neighbor may not fit you – personal finance really is personal.
Before you file, put your estimates at 62, 67, and 70 side by side, work in any spousal or survivor effects, and confirm the numbers with the SSA. Then decide.
Medicare Timing Around Age 65
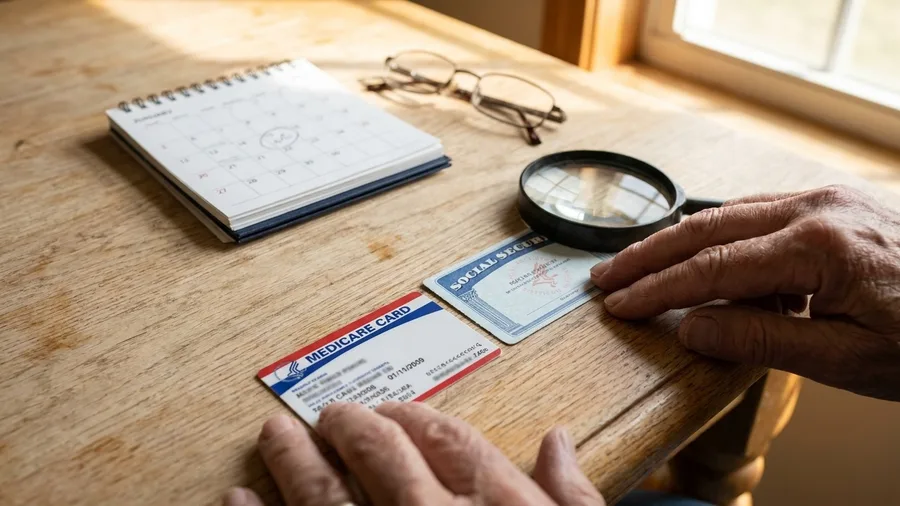
One thing filing at 62 does not do is enroll you in Medicare. That is separate, and it comes with its own window.
The distinction matters because what you pay for health coverage in your early 60s changes the net value of an early benefit. If you're buying private insurance until 65, the premiums can wipe out the appeal of a bigger monthly check, so run the two side by side rather than assuming more cash is better.
When 65 arrives, sign up on time. Late enrollment can leave gaps in coverage and add penalties, and income-related premium adjustments can push up your Part B and Part D costs if your income is high.
Check the current rules with Medicare or the SSA before you assume the age-62 benefit settles your health-cost questions. Rules change, and the penalties can follow you for years.
Frequently Asked Questions
Can I switch from early benefits to a higher benefit later?
Not on your own record. Once you file early, your monthly amount is reduced permanently. The main exception is a survivor benefit, which can replace your own benefit if your spouse dies and their benefit is higher.
How much can I earn while collecting at 62?
If you claim before full retirement age and keep working, the earnings test can temporarily reduce your benefit if your income exceeds the annual limit. The reduction isn't lost forever; it's recalculated when you reach full retirement age. Check the current limits with SSA.
Does filing at 62 affect my spouse's benefit?
Yes. A spousal benefit can be up to 50% of the worker's full retirement age benefit, and filing early reduces both the worker's amount and the spousal amount. Confirm the specifics with SSA before you file.
What if I file at 62 and later regret it?
You can withdraw your application within 12 months of filing and repay any benefits received, then file again later. After that window, you can suspend your benefit at full retirement age to earn delayed credits, but the early reduction stays with you.
Is Social Security taxed if I claim at 62?
It can be. Up to 85% of your benefit may be taxable depending on your provisional income. If you have low income now but expect pensions or required minimum distributions later, claiming early can keep more of your benefit untaxed.
Sorting the Seven: When 62 Actually Wins
Here's the rule of thumb. Age 62 is the better bet when your health or family history points to a shorter life, when a spouse or survivor strategy needs the cash flow, when a market drop or a tax window makes now unusually valuable, or when you genuinely need the money.
Otherwise, the larger check from waiting deserves serious weight. That's especially true if you're healthy, if your savings aren't earning much, and if no one else depends on your benefit.
Before you decide, pull your SSA statement and test your own 62, 67, and 70 numbers. No one-size-fits-all answer exists, and the choice that suits someone else may not suit you.
Run Your Own 62/67/70 Numbers
Pull up your SSA statement and compare the three totals. If you're married, check the spousal and survivor effects before you file.

Hello there! I’m Jesse Joe, the author and editor behind SolganGenius. I’m thrilled you’ve stopped by, and I can’t wait to share with you the essence of what this platform is all about.
I’m a writer, social media enthusiast, and a firm believer in the power of words. I’ve always been fascinated by how a simple phrase or slogan can capture an emotion, convey a message, and even change perspectives. Learn More