Retirement is a modern invention. It started in the 1930s with Social Security, got refined by pensions, and then the 401(k) rewired everything.
But now the system meant to protect you may be holding you back. Buried inside many 401(k) plans is a feature that's rarely advertised: a self-directed brokerage account. It gives you more investment control and flexibility without moving a dollar out of your plan.
Most people don't know it exists. Even fewer know if their plan has it. By the end of this article, you'll know how to check, what it changes, and the honest reasons to leave it shut.
| What changes | Standard 401(k) menu | Self-directed brokerage window |
|---|---|---|
| Investment choices | 20 to 25 funds, roughly half target-date | ETFs, managed portfolios, tactical strategies |
| Control over manager | No — you pick from the list | Yes — you choose the strategy |
| Risk management | Only by shifting to conservative funds | Professional management and defensive moves |
| Fees | Recordkeeping fee built into the plan | Trading and custodial fees set by the provider |
| Tax treatment and match | Unchanged | Unchanged — money stays inside the 401(k) |
Retirement is a 1930s invention, not a tradition
Retirement, the way you picture it, is younger than the telephone. It didn't exist before the 1930s. People worked until they died or their bodies quit.
The idea started in Germany, and it wasn't born out of kindness for the elderly. It was a way to push older army officers out of the ranks and make room for younger ones. A state pension gave them a reason to go quietly.
That approach crossed the Atlantic and landed in the U.S. with Social Security in the 1930s. Suddenly there was a thing called a retirement age, and a check attached to it. Once the concept was loose, industry and life spans were changing fast, and someone had to decide what to do with older workers. That someone turned out to be governments first, then employers.
Here's why the history matters more than it seems. According to the Social Security Administration, the program has been altered many times since its start – benefit formulas, the retirement age, the tax treatment, the cost-of-living adjustments. Retirement has been re-engineered three times in one lifetime: pensions, then the 401(k), and now whatever's coming next. The rules you inherited aren't natural or permanent. They're a design choice, and designs get revised.
So if the rules changed three times around you already, they can change again. The useful question isn't whether the system will be stable. It's whether your money is arranged to survive the next redesign.
Social Security assumed many workers would die first
– it was never meant to fund a thirty-year retirement. When the program was built, life expectancy sat well below the age you could collect.
That's the part most people miss. The arithmetic of the era assumed a large share of workers would never claim a penny. They'd pay in their working life and die before the payouts began. That's how the math balanced.
Now people live longer. Someone who stops working at 62 or 65 can spend 25 or 30 years collecting, and a system designed around much shorter retirements starts to strain. The answers floating around – later claiming ages, adjusted formulas – are all attempts to reconcile a 1930s design with modern life spans.
Which brings the lesson home: Social Security was never designed to be the whole paycheck. It was a floor under retirement, not the house. That's why your plan at work matters so much – it's the part that's actually meant to carry the weight.
And the structure of the whole system comes down to what replaced the pension. That's where the story picks up.
Pensions paid for loyalty, not investing skill
From the 1950s through the 1970s, retirement looked like a gold watch and a guaranteed check. Corporate pensions were the norm, and you didn't choose a thing.
The image sticks: forty years at the company, a farewell party, a watch, and income for life. You put in your time, and you got a pension check plus a Social Security check. The employee carried no investment risk and never had to turn a balance into a paycheck.
Why did the arrangement exist? Postwar industry and growing corporations needed to take care of a booming workforce. The baby boom generation was entering the labor force, and pensions were part of the deal. If you showed up and did your job, you had mailbox money coming in for the rest of your life.
The social logic was clear: pensions paid for loyalty, not investing skill. There was no skill required. That's exactly what made it comfortable. It's also what made it fragile – the promise depended entirely on the company staying solvent for forty years and beyond. When companies merged, moved or went under, the guarantee went with them.
So the risk didn't disappear in the pension era. It was just invisible, sitting on a corporate balance sheet instead of in your account. The next era made it visible.
The 1980s handed you the controls and the risk
The 1980s put the controls in your hands – and the risk that comes with them. The 401(k) arrived, and control shifted from companies to individuals.
What actually transferred? Three things. How much to save. How to invest it. And, the part people forget, how to turn that pile of money into income later. The burden of funding and investing moved from the company's balance sheet to your living room.
On paper, that's empowerment. Decades later, plenty of savers feel something closer to the opposite – boxed in by a short menu and a pile of paperwork. A plan sold as freedom can feel like a cage when you can't find a way out of it.
Take the typical example: a 52-year-old with $310,000 in the plan, contributing 8% of pay, with a 4% employer match, choosing among 22 funds. That's a real menu, but it's also a fence. About half of those funds are probably target-date versions, and the rest are broad categories. If you want a specific sector, a small-cap or an international tilt, you're out of luck inside that list.
That's exactly why a hidden option buried inside many of these plans matters. If you don't like the menu, sometimes you can leave it. But that's only the first question.
Here's the second: the plan still depends on you showing up in the first place.
💡 PRO TIP
The one question that unlocks everything
Ask HR or your plan administrator in writing: 'Does our plan offer a self-directed brokerage account, and which contribution types can go into it?' Until they answer, nothing else in this article applies.
A 401(k) only works if you keep opting in
Because nobody signs you up. A pension enrolled you the day you were hired, and Social Security simply took its cut from your paycheck. The 401(k) hands you the paperwork and waits for you to raise your hand.
That is the whole shift in one sentence, and it explains a lot of the anxiety people carry about retirement accounts. You are not just saving. You are running a small program that used to run itself.
The long tail of that is quieter than it sounds. Someone who never gets around to enrolling does not lose a little – they lose every year they stayed out. No contributions, no employer match, no compounding on money that was never there.
Take the saver at 52 with $310,000 sitting in a 22-fund menu. Eight percent deferral, four percent match. Skip eighteen months of that at a $95,000 salary and you have left roughly $17,100 of your own money and about $5,700 of match on the table – plus whatever those dollars would have earned for the next fifteen years. None of it comes back.
And even the ones who do enroll usually get no investment education with the keys. You get a stack of fund names, a target-date option with a year in it, and a login. That is not training.
So treat it like a program with a heartbeat rather than a box you ticked once. Check your deferral rate every raise, confirm the match is actually landing, and look at the balance at least twice a year. Keeping the hand up is the entire job.
The menu versus the window
A 20-to-25 fund menu protects the employer, not you
Your plan offers a short list of funds because a short list is easier for your employer to stand behind, not because it is the best list for you.
A typical menu runs 20 to 25 investments, and roughly half of those are target-date funds. That is not a coincidence or a rounding error. Target-date funds are designed to be set-and-forget, which means most employees can pick one, never touch it again, and the employer's job is done. The remaining dozen or so options round out the basics: a few index funds, a couple of actively managed ones, maybe a stable value fund. Enough to look complete. Not enough to be complete.
The real reason for the short list is liability. Every fund on that menu is a fund the employer has to vet, monitor, and defend if someone sues over poor performance or a bad default. Offer 22 well-documented choices and you've managed the risk. Offer 2,000 and you've created a full-time compliance job plus a target on your back. So the menu is built to protect the plan sponsor, not to widen your opportunity.
Here is what that means in practice. You can't bring in your own money manager. You can't direct the plan into a strategy you designed or a sector you believe in. You pick from the list, or you pick a target-date fund and let it ride.
For a lot of savers, that starts to feel like a trap rather than a path to freedom. The door is locked, the key is with HR, and nobody mentioned there might be another way out. There is, and it starts with understanding what the menu actually is: a liability shield dressed up as a benefit.
The brokerage window lets you leave the menu
A self-directed brokerage account, usually shortened to SDBA, is a built-in feature of many 401(k) plans that opens a full brokerage platform inside your existing account.
It's rarely advertised. It's rarely explained at enrollment. Most people find out about it by accident, usually from a coworker or a financial advisor who asks the right question. But it's there in a lot of plans, sitting quietly behind the fund menu like a door you walked past a hundred times without noticing.
What it does is simple: it lets you step outside the preset list and into a real brokerage environment. That means ETFs. Professionally managed portfolios. Tactical management. Defensive strategies you can actually implement. The kind of moves that a 22-fund menu simply doesn't allow, because those funds weren't built for it.
Here's what does not change. Your tax advantages stay exactly where they are. Your employer match keeps flowing in. Your plan protections, the ones that shield the account from creditors and keep the recordkeeping clean, all stay put. No dollar leaves your 401(k). The money just moves into a different room inside the same house.
That's the part people miss. The SDBA isn't an exit from the plan. It's a door inside it. Same account, same tax treatment, same match, but access to a much wider set of tools. Discovering it feels a bit like finding a secret door in a building you thought you knew. The question is whether you're ready to walk through it.
Broader access buys diversification and real risk management
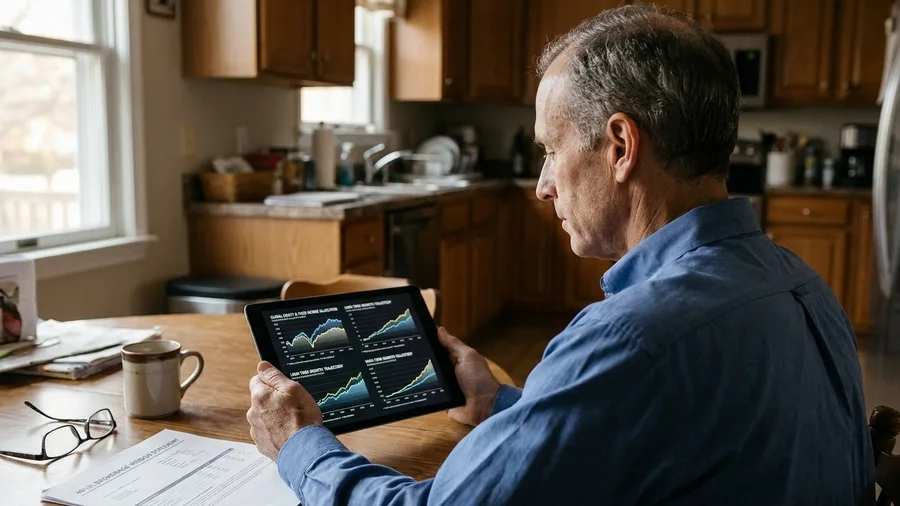
The extra choice inside a brokerage window buys you real diversification and actual risk management, not just a longer list of tickers to scroll through.
In a standard 401(k), your only risk lever is moving into more conservative funds. That's it. If you want to reduce risk, you shift from stocks to bonds. If you want growth, you shift the other way. There's no tool for managing risk in a more nuanced way, no way to hedge, no way to build a portfolio that responds to conditions rather than just sitting in a fixed allocation.
A brokerage window changes that. You get access to professionally managed portfolios, which matters more than it sounds, because the biggest enemy of retirement returns is usually the saver's own emotions. People tend to sell after a drop and buy after a run, which is exactly backwards. Professional management takes that decision out of the moment, and the moment is when most mistakes happen.
Younger investors gain the most from this. A 30-year-old with a wide fund set can build a growth-oriented portfolio inside a tax-advantaged plan, letting decades of compounding work on a more aggressive mix than a standard menu allows. That's not a small thing. It's the difference between a savings plan and a wealth-building engine.
The reframe is worth sitting with. A standard 401(k) is designed to get you to retirement. A brokerage window gives you the tools to shape what that retirement looks like.
First, confirm your plan actually has one
Not every plan offers an SDBA, so the first move is a direct question to HR or your plan administrator before you do any planning at all.
Availability is plan by plan, and it's genuinely mixed. Plenty of large employers have it. Plenty don't. Two people working at similar-sized companies can have completely different access, and there's no way to know from the outside which camp you're in. Assumptions here are expensive, because everything else in this decision depends on the answer.
Ask in writing. An email to HR or the plan administrator that says something like, "Does our 401(k) offer a self-directed brokerage account, and if so, could you send the fee disclosure and the list of eligible contribution types?" That last part matters. Plans differ on which contribution types, pre-tax, Roth, employer match, can actually go into the window. Some plans let all three in. Some restrict it. You want the answer on paper before anything moves.
The roster of plans known to offer it keeps growing, so a no today isn't necessarily a permanent no. Employers add features, providers change, and a question you asked two years ago might get a different answer now. Worth re-asking if it's been a while.
But the order is the point. Nothing else in this whole decision applies until the option is confirmed. Check first, plan second.
Is the window worth it?
Worth exploring
- Your plan menu is thin or expensive
- You want access to ETFs and managed portfolios
- You will maintain an allocation and rebalance
- You understand the fee structure
Probably skip
- Your plan already offers cheap broad index funds
- Your balance is small enough that per-trade fees bite
- You won't monitor or rebalance
- You're unsure which contribution types can move
Fees and fit can erase the advantage
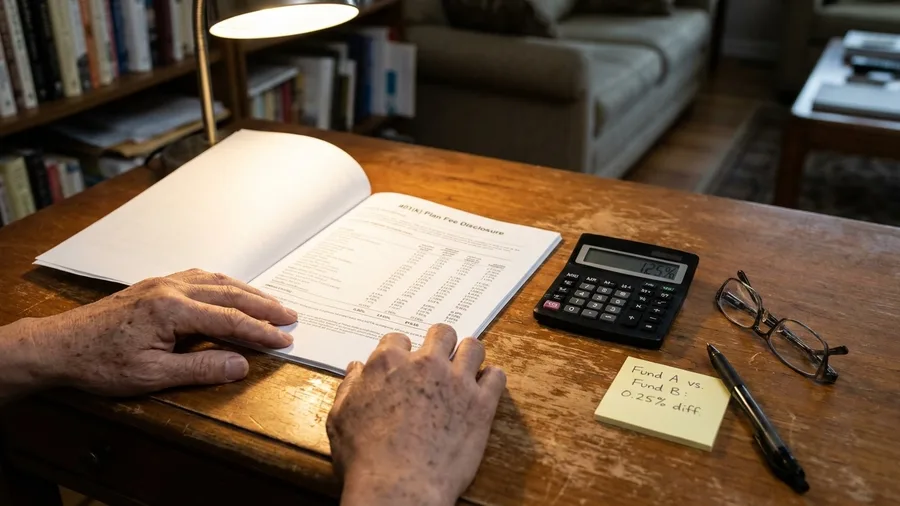
The window can be a bad deal if the provider charges trading or custodial fees that outrun the savings, or if the funds inside it don't fit your goals and timeline.
Some SDBA providers charge a small trading fee per transaction, or a custodial fee for holding the account, or both. They're usually modest, but they add up, and they can quietly eat the advantage you were hoping to capture. A saver who trades frequently inside the window, or who picks funds with their own expense ratios on top of the platform fee, can end up worse off than someone who just picked a target-date fund and left it alone.
Then there's fit. Not every fund on the platform suits your goals or your timeline. A leveraged ETF or a sector bet might look appealing in a good year, but if it doesn't match where you are and when you need the money, it's not an upgrade. It's a complication. More choice without a method is not an improvement. It's just more ways to make a mistake.
So run the comparison before you move anything. Pull the plan's own fee documents, usually available from HR or the plan administrator, and look at what the window costs against what the plan's existing recordkeeping already costs. Add in the expense ratios of the funds you're considering. If the numbers don't work, leave the door shut. The window is a tool, not an obligation, and knowing when not to use it is part of using it well.
Many people open the window and never use it
Turning the feature on and never touching it again is the most common outcome of all, and it costs you nothing but it earns you nothing either.
There's a cluster of savers at the big logistics employers who know this pattern well. UPS, FedEx, DHL, the names you'd expect to offer a deep benefits package, all carry the brokerage window. So people who work there tend to end up with the option whether or not they went looking for it.
Here's what tends to happen next. They arrive already activated, walked through the setup screens by someone helpful, and then the account just sits there. Not because they lost interest exactly, but because they opened it, looked at a universe of thousands of choices, and thought: now what?
That's the honest trap. A full menu doesn't produce action. It produces a shrug. When your old plan gave you 22 funds, at least the decision was small. Now there's no obvious first move, so no move gets made.
And the cost of that stall is real. An open window holding cash, or still parked in the plan's default fund, does no work at all. It's not growing any faster than it did before. It's not diversified any better. You did the paperwork and bought yourself a slightly more complicated statement.
The fix isn't more research. It's picking one thing to move and moving it this month. Two hundred dollars into something you understand beats a year of staring at a long list of funds.
Where the stall shows up
The share of savers who open the window but never use it
Opening it is easy; running it is the work
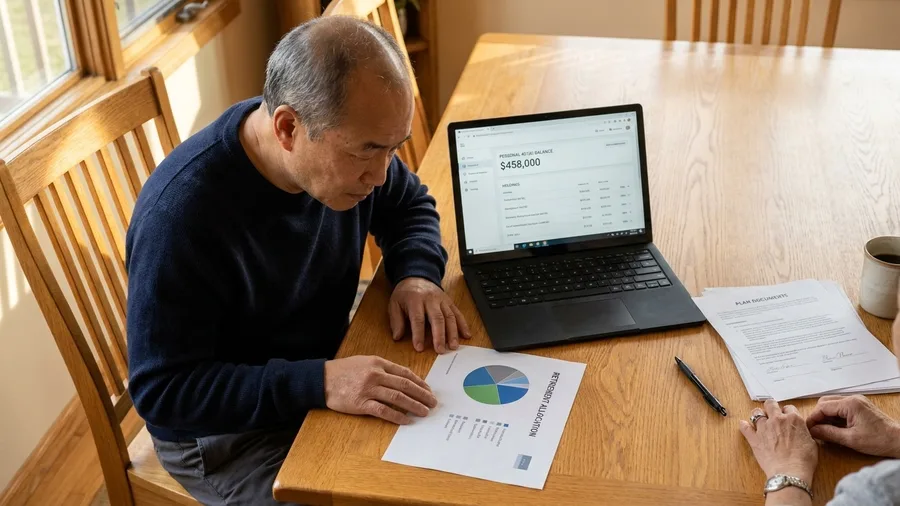
Opening the window takes a phone call; making it earn its keep takes a plan you actually follow.
The sequence is short and not especially dramatic. A first conversation to walk through what's available and whether it fits your situation. Activation, which varies by plan and isn't always the smooth click-through you'd hope for; some setups ask for paperwork and a signature. Then the real step: building the allocation.
That last part is where people go wrong. Picking a few funds that look good in isolation isn't a plan. You want to build a total retirement picture from the whole universe available to you: your core holdings, what each one is doing in the mix, how they behave together when the market turns. A fund that's brilliant on its own can wreck a portfolio if it duplicates something you already own.
Then comes the ongoing job, which nobody advertises. Staying between your guardrails. Not ripping everything up the first time markets get shaky, because they will, and that's exactly the moment the plan earns its keep.
Having the account is half the job. Executing it correctly is the half that pays. The window is a door, not a strategy, and it doesn't do the thinking for you.
Your match, your contributions, and what can move
The money in that window stays inside your 401(k), so it's your plan's rules that govern it, not the brokerage's.
That's the part people miss. The brokerage provider might run the account, but your employer's plan document sets the terms. Same tax treatment as the rest of the plan, same recordkeeping, and yes, the employer match is still part of that world.
Now, plans differ on the details here, and you can't assume. Some let you direct pre-tax dollars into the window. Some allow Roth. Some let the match follow. Others hold the match back and keep it in the core menu, or restrict certain contribution types entirely. The plan administrator is the one who confirms which for your specific plan, so ask them in writing before you move a dollar.
The match itself is still calculated on your payroll deferrals, which means your deferral rate has to be right for the match to keep flowing. If you're at 8% with a 4% match, moving money around inside the plan doesn't change that calculation. But dropping your rate to free up cash would.
One more thing worth knowing before you commit: the window is a feature of that employer's plan. It doesn't travel with you. Change jobs and you'll want to ask what happens to those positions, because the answer isn't always the same.
SDBA, IRA, or taxable: where each dollar goes
No, the window isn't automatically better than rolling money into an IRA. What matters is the order you do things in.
First, capture the full employer match. That's the cheapest money you'll ever get and nothing else on this list beats it. If your plan matches 4% and you're deferring 8%, you're already capturing it, and that stays true whether or not you touch the window. Only after the match is handled does the question of what belongs in the window make sense.
So where does each dollar go? An IRA wins on breadth. No plan menu, no employer restrictions, whatever funds you like. But no employer match follows the money out the door, and once it's in an IRA it's yours to manage with no plan protections behind it. The 401(k) window gives you a wider menu while keeping the match, the recordkeeping and the plan's structure. Taxable accounts come last, after the tax-advantaged options are full.
The trap to watch for is overlap. Holding the same index fund in your 401(k) core menu, in the window, and in an IRA, and calling that diversification. It isn't. It's one position wearing three hats, and it'll move as one when markets do.
For anything involving taxes or a rollover, talk to a tax professional or read the plan's official documents. Those are the sources that actually apply to your situation.
Frequently Asked Questions
What is a self-directed brokerage account in a 401(k)?
It's an optional feature inside some 401(k) plans that lets you invest beyond the plan's preset fund menu. You get access to a full brokerage platform—ETFs, managed portfolios, tactical strategies—while keeping the same tax treatment and employer match.
How do I find out if my plan has one?
Ask HR or your plan administrator directly, ideally in writing. Availability is plan by plan, and the roster of plans offering it keeps growing. Until you confirm, nothing else matters.
Does money in the brokerage window lose 401(k) protections?
No. Dollars in the window stay inside the 401(k). You keep the same tax advantages, employer match, and plan recordkeeping and protections. The brokerage is just a different door into the same account.
What fees should I watch for?
Some SDBA providers charge trading or custodial fees. Compare those against your plan's existing recordkeeping cost using the plan's fee documents. If the numbers don't work, leave the window closed.
Why do people open the window and never use it?
A full universe of choices can cause paralysis. Many people activate the account, see all the options, and freeze. The fix is a short conversation with a fiduciary to build a plan, not more browsing.
Is the window better than rolling into an IRA?
Not always. Capture your full employer match first. An IRA offers a broader menu with no plan limits, but you lose the match. Watch for holding the same fund in both places and calling it diversification.
The decision rule for your brokerage window
Activate and fund the window if your plan's menu is genuinely thin and you will maintain an allocation. Leave it closed if your plan already offers cheap broad index funds, your balance is small enough that per-trade fees bite, or nobody will rebalance.
Run the same test on your own numbers: menu quality, fee drag, and your willingness to stay involved. The window is a tool, not a mandate.
Your first move: one call to the plan administrator asking whether an SDBA exists and which contribution types can go into it. Do that before anything else.
Check your plan today
Call your plan administrator and ask if your 401(k) has a self-directed brokerage window. That one question decides everything.

Hello there! I’m Jesse Joe, the author and editor behind SolganGenius. I’m thrilled you’ve stopped by, and I can’t wait to share with you the essence of what this platform is all about.
I’m a writer, social media enthusiast, and a firm believer in the power of words. I’ve always been fascinated by how a simple phrase or slogan can capture an emotion, convey a message, and even change perspectives. Learn More