On a Friday at 7:14 in the morning, in Toledo, Ohio, while the coffee is still brewing, a pharmacy technician opens her banking app and transfers precisely $50. Same time, every payday. She has done it for 14 months without missing once, and she has never mentioned it to anyone.
She takes home $2,380 a month. Every savings calculator you have ever opened would call that too little to bother with. And yet, by month 14, she had three full months of survival expenses sitting in an account she never touches.
There is a rule buried in that number. It has three moving parts, and once you see them, you will understand why percentage plans keep dying on people with real paychecks. The math is not the interesting part. The reason it holds up is.
By the end, you will know exactly what to do tonight, and why it will still be working in month five when everything else you have tried has quit.
Percentage Plans Assume Leftovers You Don't Have
Percentage savings plans keep failing you because they were built on an assumption your life doesn't meet: that a predictable surplus shows up at the end of every month and your only job is to catch it before it slips away. Save 20% of your income. Save 10%. Save three to six months of expenses. The percentage changes. The assumption underneath never does.
So ask the question the plan never answers. Twenty percent of what, exactly?
By the time rent, the car payment, the insurance bill and the groceries have all spoken, 20% of nothing is still a number. It's just a number that happens to equal zero. The formula didn't fail. It was never describing your month in the first place.
If you've ever entered your real numbers into a savings calculator, seen it promise an 11-year finish line, and quietly shut the tab, that wasn't weakness. That was a rational response to guidance that wasn't designed for your paycheck. A calculator projecting an 11-year runway is really telling you the plan says nothing about next Friday.
Here's the reframe worth keeping. A percentage is a demand that scales with a surplus you don't control. A fixed $50 unit doesn't care whether the surplus exists this month. It's small enough to survive a bad pay period and concrete enough to count toward something, which is exactly why it keeps working after the percentage math has given up.
The plan was mismatched to the paycheck. You just happened to be holding it when it broke, so self-blame is the wrong diagnosis. The fit was wrong, not you.
Small Shocks Are Normal and Paychecks Move
This is urgent for anyone on a modest or irregular paycheck because small emergencies are common and your income itself moves, so a plan that assumes a calm surplus was written for someone else's life.
This isn't a hypothetical hitting a thin slice of people. The Federal Reserve's household survey has found for years that nearly four in 10 adults couldn't cover a $400 emergency with cash. Bankrate's numbers land even harder: less than half of us could absorb a $1,000 surprise without borrowing. Those are the ordinary knocks, not catastrophes.
And the paycheck isn't a calm, predictable thing either. Economists at the J.P. Morgan Chase Institute discovered that for lower-income households, income swings by double-digit percentages from month to month. Not a small wobble. A real swing. So you're trying to plan against emergencies while the ground under the plan is moving.
That combination is why percentage plans come apart. When your income moves, a fixed percentage of it moves right along with it, and some months the demand lands on a week when there is nothing left to give. A plan that assumes a stable surplus simply isn't written for your life.
A fixed $50 brick is the same size on a good month and a tight one. It doesn't read your balance and quietly adjust itself upward. It's small enough that a swing doesn't cancel it, and that predictability is the whole point. The brick stays put while the paycheck moves.
| What changes | $50 brick rule | Big monthly target |
|---|---|---|
| Monthly commitment | $50 every other Friday | $500 every month |
| First month result | $50 moved automatically | $500 moved, feels great |
| When hours get cut | Wall stays exactly as tall | Plan misses and dies of shame |
| Catch-up demand after a miss | None—next brick is $50 | $1,000, which is impossible |
| Where it stands at 14 months | Three months of survival banked | Third restart, account near zero |
Precision Is Not the Same as Poverty
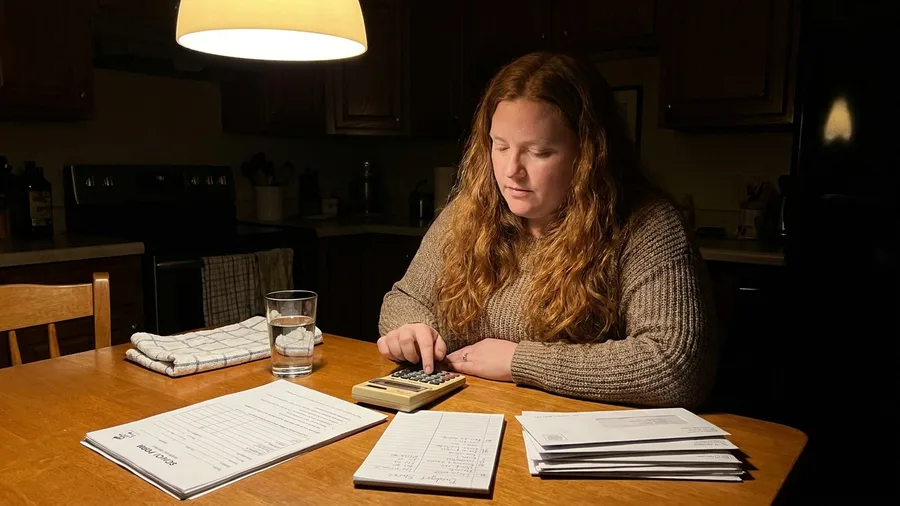
It feels like precision, not poverty: every dollar is assigned before it arrives, so a $65 form means rebuilding the whole month rather than reaching for spare cash.
Take the pharmacy technician. She's 33, 11 years into the job, and takes home $2,380 a month on a biweekly pay schedule. Her financial life isn't reckless. Every dollar has a job before the money lands, and every month is a landing she has to stick.
One Tuesday night, at 11:52 p.m., she sat at the kitchen table working the math on a $65 school field trip form. She rearranged the figures like she was squeezing oversized furniture into a cramped room. Sixty-five dollars, and it took restructuring the entire month.
That was the night she said the thing out loud. Miss one paycheck and everything falls. Not a dramatic fear. A plain description of the math.
This is what a no-slack life actually looks like. It isn't overspending or a discipline problem. It's a budget with zero give, where a field trip form is a crisis and the car making a new sound is its own specific kind of dread. Calling that a spending problem misses the point entirely. Nothing was wasted. It was all already spent.
The Tile Setter Asks What Is My Tile
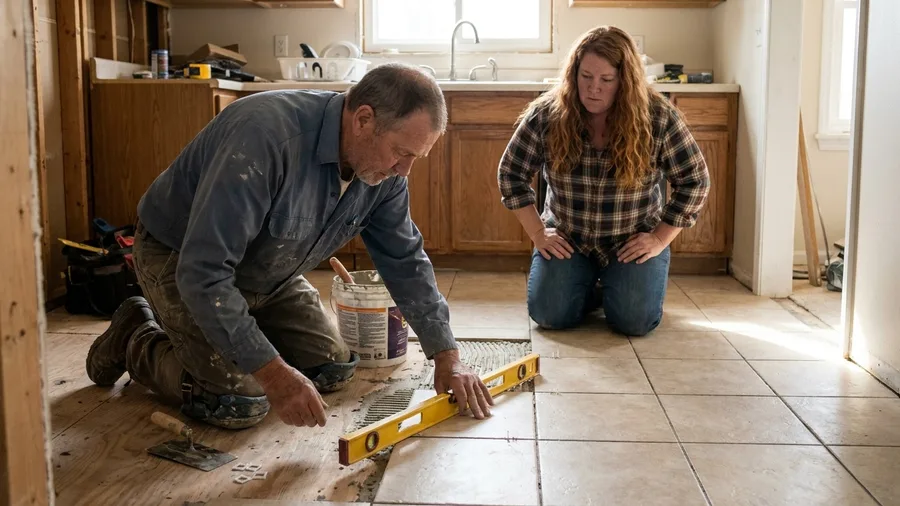
The brick idea came from a tile setter, not a bank or an app: her uncle Sal, who set tile for 31 years and answered the whole problem with a single question.
Kitchens, lobbies, and one hotel pool he never stopped bragging about. She once asked how he could stand working on floors that took months to complete. He looked at her like she'd asked something foolish. He never set a floor, he said. He set the next tile. The lobby was none of his business. His business was one tile, level and true, and then, only then, the one after it.
Thirty-one years of that, and behind him were acres of finished floor.
She went home and looked at the wreckage of her second failed plan. Both plans shared one outline: a huge figure at the far end and a monthly requirement in the middle. Save $500 a month, build $20,000. The target sat up there like a lobby, and she kept trying to lay the whole floor at once.
So she sat down and asked the question that built everything. What is my tile?
The answer was small and boring: $50, moved automatically, the same amount every payday. Not the whole floor. One level tile. She wrote down one brick and stopped looking at the lobby.
Big Targets Demotivate More Than They Motivate
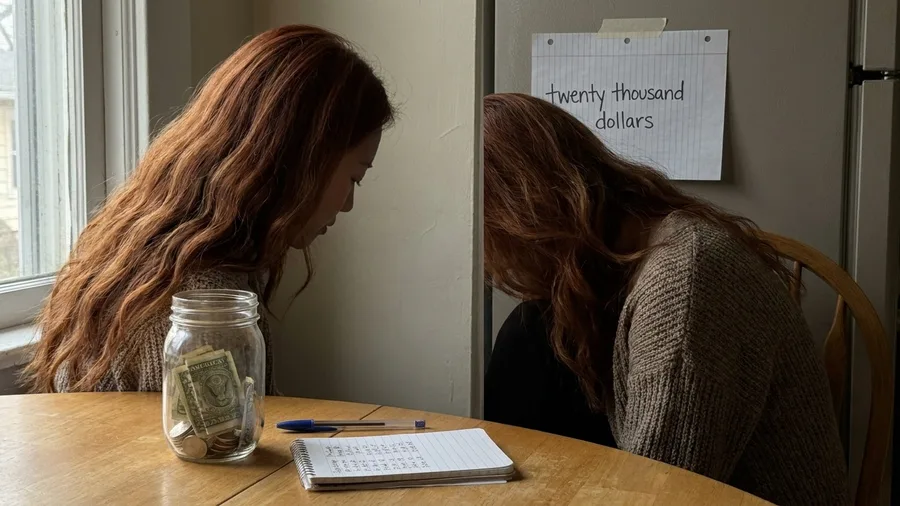
A huge savings goal makes you quit because the gap between where you are and where the plan says you should be does the talking, and it's louder than any reason to keep going.
The economist Richard Thaler made a career of documenting how the mind actually handles money. We don't hold it as a single pool. We file it into mental accounts, and we respond to big distant goals very differently from small immediate actions. That's not a flaw you can lecture yourself out of. It's how the wiring runs.
So the giant number doesn't motivate you. It works against you. Every month you glance up at $20,000 from $300, and the gap becomes the loudest voice in the room. Each new deposit just makes the distance more specific.
Big plans don't die of math. They die of the view.
A $50 brick is small enough to be a present action, not a distant judgment. You're not staring at a $20,000 gap and feeling small. You're laying one tile and it's level. The view never gets a chance to talk you out of it, because you never turn to look at it.
Here's the catch: this only works if you leave the target off the wall. Write the brick count once, then keep your eyes on the next deposit instead of the finish line.
One Automated $50 Brick Starts the Wall
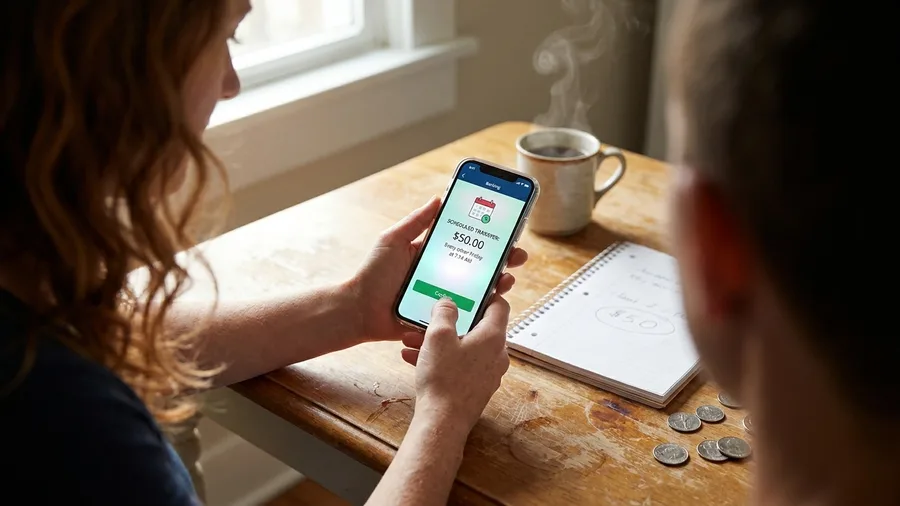
The first move is one brick: $50, and that's the sole increment in which your emergency fund may grow. Not a year of savings. Not $20,000. One brick.
To know how many bricks you need, work out your true survival number. Rent, utilities, groceries, insurance, transport, phone, and nothing else. In the Toledo example that came to $1,700 a month, which is $20,400 a year, which is 408 bricks. Write that number down exactly once, then put the paper in a drawer and leave it there.
Do not check the count daily. Checking is a way of negotiating with the plan, and the plan does not take meetings.
Now set the automation: $50 transferred biweekly at 7:14 a.m., ahead of coffee, ahead of feelings, ahead of the month getting a vote. The discipline happens once, the day you open your banking app and schedule the transfer. The machine handles every morning after that. If payday lands differently, pick the morning after it and keep it fixed.
This is not a $50-a-week challenge, and the difference matters more than it sounds. A weekly challenge is one lever and a 30-second read, and you would have quit by March. This is three parts working together: the automated payday brick, a 24-hour conversion engine that catches freed and found money, and a hard ceiling that keeps a strong month from wrecking a weak one.
One catch worth naming: irregular annual bills can quietly inflate your survival number if you let them. Take the yearly insurance premium, divide by twelve, and fold it in. Do not pad the figure for comfort. The brick count is a measurement, not a wish.
What Each Brick Actually Buys
Freed and Found Money Converts Within 24 Hours
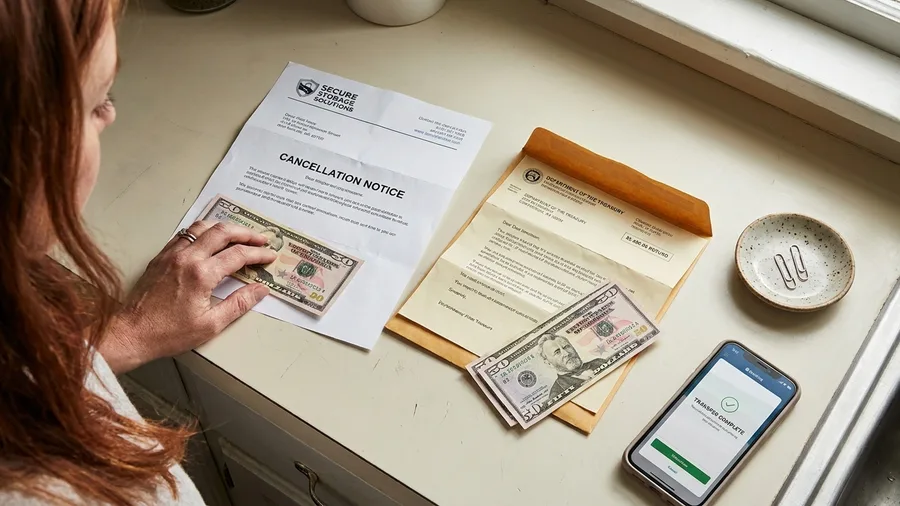
Freed or found money gets converted into bricks within 24 hours, before it has a chance to become part of the month. The payday brick is the heartbeat; the conversions are where the wall actually rises.
Start with the storage unit she had been avoiding thinking about. Canceled, it opened up $89 a month. Under the rule, money you free up doesn't dissolve back into the budget. It converts. One brick a month, laid the same day every month, with the reason attached to it, so the $89 has a name instead of a shrug.
Then the tax refund landed: $1,140. This is where most plans leak. A windfall gets mentally filed into the fun-money account, and it evaporates at double speed. The answer is to claim it fast, within a single day. Before 24 hours passed, that refund became 22 bricks, laid, counted, and moved out of temptation's reach.
The small ones count too. Picking up a shift for a co-worker's weekend became two bricks. An insurance refund nobody expects became one. Thirty-nine cents stayed in checking for the joy of it, which is the right amount of joy to take from money that has a job to do.
Here is why the pace matters. A $50 habit on its own looks slow, and it is. But when freed and found money is captured instead of absorbed, the same habit can build at something closer to a $400-a-month pace in a good stretch. Same rule, same ceiling per decision. The engine just has more fuel some months than others.
The catch: the window is doing real work, so give it a deadline you can act on. The moment a refund hits, open the app before you open anything else. If you wait until the weekend to decide, the month will have already spent it.
⚠️ COMMON MISTAKE
The Windfall Leak
Letting a refund sit in checking for a week is the same as spending half of it. Move it to bricks the same day it lands, before your brain files it under fun money.
$50 Ceiling Keeps Good Months From Killing Bad Ones
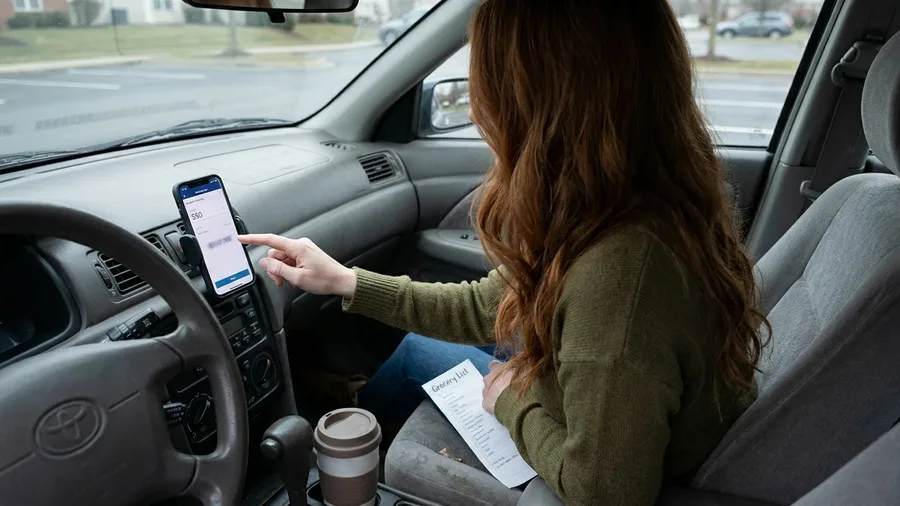
Because the $50 rule never lets you make a single savings decision bigger than $50, no good month can plant the seed of a bad one. Not $300 because you are feeling strong. Not $150 because it is bonus week. Fifty, same as always.
That might sound like it is working against you. It is not. The same ambition that puts $300 in on a strong month is the ambition that quits outright on a weak one, so know when to stop saving. The ceiling keeps things dull, and dull is the feature, not the flaw.
Compare it to a percentage plan. It misses a month, the number looks ugly against the target, and it dies of shame. The wall does not judge. It is exactly as tall as it was. The next brick is exactly $50, same as always. You lay a brick, or a few, a single call at a time, and in the months when the car makes that sound, nothing breaks.
The missed-month rule is the whole point: if you skip a month, you do not owe a catch-up. You do not recalculate anything. The wall waits, unchanged, and the next brick still costs $50.
One honest caveat. If your paycheck has genuine, stable slack in it every single month, a larger automated number can work. The ceiling is built for income that moves. If yours does not, the ceiling costs you nothing anyway, and it protects you the first time the hours get cut.
The wall just waits.
Two Ways to Handle a Good Month
Respecting the $50 ceiling
- A $1,140 tax refund becomes 22 separate $50 bricks within 24 hours, never one $1,100 move.
- An $89 storage unit you cancel converts to exactly one brick a month, no negotiation needed.
- A $380 brake repair in month 11 comes out as roughly 7.5 bricks, without breaking the wall.
- Missing a month leaves the brick count unchanged, so the next transfer is still $50 at 7:14 a.m.
The 'I'm feeling strong' contribution
- You commit $500 a month on the same paycheck that takes home $2,380, roughly double the $50 brick.
- When hours get cut, the plan asks for a $1,000 catch-up instead of letting a missed month pass.
- Two months in, the gap between the auto-transfer and the paycheck becomes a restart from near zero.
- The third restart lands near zero, because nothing in the plan was capped at $50.
$50 Is Slow, but the Panic Dies First
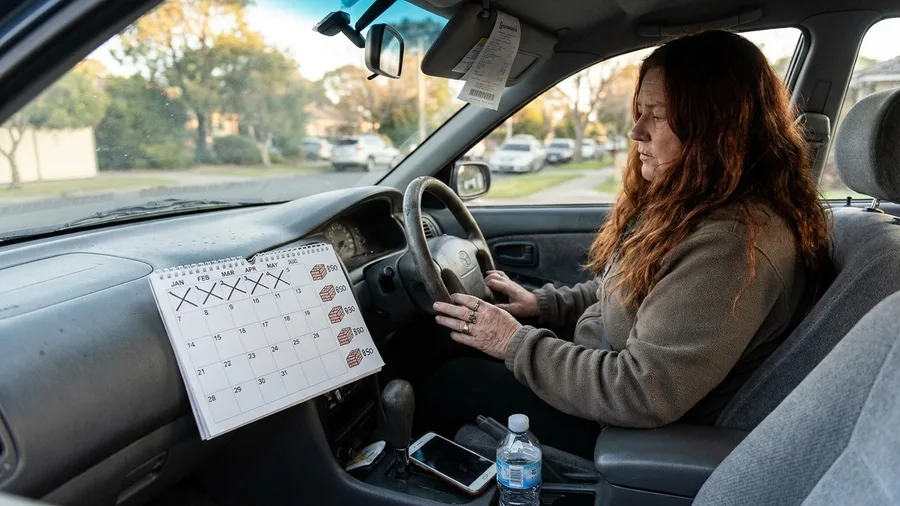
$50 is slow. The full 408 bricks take just under four years at the example pace, and there is no dressing that up. If you are only going to feel safe when the whole wall is done, you have misunderstood the habits of retired millionaires and what walls are for.
An emergency fund does not have to be finished to be working. She banked her first full month of survival, 34 bricks or $1,700, in month four. Month four is when the 11:52 p.m. math sessions stopped. Fourteen months in, she had three full months standing behind her, and the particular dread that used to live in the sound of her own car had nowhere left to sit.
Notice what changed first. Not the total, which was still small against the goal. The panic. The panic dies in the first mile, and the first mile is a lot shorter than four years.
There is a practical reason the early bricks hit harder than the math suggests. A $380 brake repair in month 11 takes about seven and a half bricks, and by then you have them. Before the wall existed, that same repair was a credit card. Same car, same noise, completely different month.
So treat every course of bricks as shelter, not as a failed completion. You do not need the whole wall to get out of the rain.
The year is the destination. The panic dies in the first mile.
The Numbers Behind the Wall
The $500 Plan Collapsed; the $50 Wall Waited
If you pick an impressive monthly number instead, you usually get an impressive two months and then a quiet stop. There is a cleaner way to see it than any argument, because it happened to two women on the same paycheck.
She had a co-worker at the same pharmacy, same years in, take-home pay within $40. Fourteen months back, over a lunch break, the two of them got talking about money, and both began saving that same week.
The co-worker did what the internet told her. She picked the impressive number: $500 a month. For two months she made it, and it felt like being a new person. Month three her hours were cut, and the plan missed. Month four, catching up meant finding $1,000, and the arithmetic mocked her. She quit without a word, the way plans die. No announcement, just a transfer that stopped happening. She began again in the spring, identical plan, identical wall, identical outcome. She is on her third restart now, and her account this morning sits near zero.
What separates these two women is not a dollar of income, and it is not effort. It is plan design. A $500 target only fits a paycheck with stable slack, and most paychecks do not have it.
The $50 wall was load-tested for a life with moving income, and it held.
If you have genuinely stable slack every month and have already proven it for a year, a bigger target can fit. The rest of us should assume the hours can move, because they can.
🧱 What the First 14 Months Actually Look Like
Month 1: Set the machine
Automate the $50 transfer for every other Friday at 7:14 a.m.
Month 4: First survival month banked
34 bricks, or $1,700, sit behind you and the midnight math stops.
Month 11: The brake repair
A $380 bill takes about 7.5 bricks off a wall holding four months, and the wall absorbs it.
Month 14: Three months of shelter
Three full months of survival are banked, and the wall is still growing.
Year 4: The full wall
408 bricks, or $20,400, complete the year of survival at the example pace.
A Real Emergency Becomes a Boring Payment
In month eleven, the fund stops being a plan and starts being a thing that pays for things. The brakes went on a Tuesday: grinding, the number you don't say out loud, $380. She stood at the shop counter, paid it, took her keys, and drove home.
It wasn't until she was turning onto her own street that she noticed what hadn't happened. Nothing. No spiral, no midnight math at the kitchen table, no moving money around to cover moving money around. Seven and a half bricks came off a wall holding four months' worth, and that wall simply took the hit.
That's the whole trick, and it's why the number on the wall matters less than what the wall does to your nervous system. A $380 hit against nothing is a crisis. A $380 hit against four months is an errand.
She told her sister it was the most expensive boring afternoon of her life. Boring is the point. The quiet isn't decoration hanging on the plan. The quiet is the deliverable, and $20,400 is just the figure that happens to produce it.
Which raises the question you're probably asking: what if the emergency is bigger than the wall? Then the seven and a half bricks go, the wall dips, and next payday it starts laying again. No restart, no shame, no third attempt from zero. That is what a wall is for.
The $50 Rule — At a Glance
💵 Unit
$50
📅 Frequency
Every other Friday
⏰ Conversion window
24 hours
🚧 Ceiling
$50 per decision
🏁 Finish line
408 bricks
The whole machine
Small unit, greedy capture, hard ceiling. That is all three moves working together.
Two Edges: Income Below Survival and Account Choice
There are two edges to this rule, and both are honest limits rather than fine print. The first: if your earnings truly fall beneath your survival line, if the arithmetic goes negative before a single brick exists, then laying bricks is not your first move.
Income is. That means benefits you've already earned, more hours, a better rate, and the harder conversations with people who can actually change the number. A savings habit does not fix an income gap, and pretending it does is exactly the kind of advice this whole method exists to avoid. Using the rule as a shame instrument on a negative budget is the one real misuse of it.
The second edge is where the bricks live. The Toledo wall sits in a high-yield savings account paying around 4%, which is roughly what these accounts paid in 2026. At that rate, a finished $20,400 wall lays about 16 of its own bricks a year without anyone lifting a finger. The wall eventually hires itself.
But rates move and tax treatment varies. Compare current account terms and any tax you might owe at the official sources rather than treating 4% as a promise, and give the compounding side its own deliberate decision instead of a guess. The rule gets you to the wall. Where you park it deserves ten minutes of real thought.
Start Tonight With Three Concrete Moves
You start tonight, before you sleep, with three moves, and none of them take longer than a coffee. First: find your real survival number, the stripped and honest one, and divide it by 50.
If rent, utilities, groceries, insurance, transport and phone come to $1,700 a month, that's 34 bricks for one month of survival, 408 for a year. Write your count down once. Then put the paper away and don't look at it again. That's not laziness; that's the ceiling doing its job, because a number you stare at becomes a number that scares you.
Second: set the automated $50 transfer as the first transaction of your pay cycle, before you go to bed. Willpower is spent by Friday afternoon. A standing transfer has never had a bad week.
Third: start your conversion list. Each subscription, fee and forgotten drip you cancel from today gets a standing destination within 24 hours. The canceled $89 storage unit becomes one brick a month; a tax refund becomes 22 bricks the day it lands. No exceptions, or the found money finds a different home.
Picture 7:14 on a Friday morning in Toledo, coffee dripping, $50 moving in the dark of a kitchen and nobody told. You don't save a year. You lay a brick.
Frequently Asked Questions
Do I have to save exactly $50, or can I pick a different amount?
The $50 amount is the unit, not a magic number. What matters is that the unit is small enough to survive a bad pay period and fixed enough to become automatic. If $50 is genuinely too much, pick $20 and recalculate your brick count. The three moves stay the same.
What if I miss a payday and can't move a brick?
Nothing breaks. That is the whole advantage over a percentage plan. The wall is exactly as tall as it was, and the next brick is still $50. You do not owe a catch-up payment. Just resume the automatic transfer when the money is there.
Where should the brick money actually sit?
A separate high-yield savings account at a bank you do not use for daily spending is the simple choice. Compare current rates and terms at official sources, and turn off instant transfers if the account lets you. The friction is a feature, not a bug.
How do I calculate my survival number if my bills change?
Add up rent, utilities, groceries, insurance, transport, and phone for a typical month. Average irregular annual bills into a monthly figure. Leave out subscriptions, dining, and anything you could cut in a true emergency. That stripped number is your survival number.
Does the $50 rule work if my income is irregular?
It works better than a percentage plan for irregular income because the unit is fixed. Set the transfer for the day after your paycheck clears, and keep a small buffer in checking so timing shifts do not cause an overdraft. If your income is consistently below survival, fix the income first.
What do I do when I finish all 408 bricks?
Define the finish line from your own survival number, keep the emergency fund separate from spending goals, and redirect new bricks to the next target—debt payoff, investing, or a replacement fund. Do not loosen the $50 ceiling just because the count is complete.
The Brick You Lay Tonight Is the One That Counts
The $50 rule does not ask you to feel optimistic about your finances. It asks you to do one small thing before you go to sleep: calculate your survival number, divide it by 50, and schedule the first $50 transfer for the day your next paycheck clears.
That first brick is not impressive. It is not supposed to be. What keeps the plan alive after the first month is the conversion list and the ceiling. Every freed dollar gets a destination within 24 hours, and no savings decision ever gets bigger than $50.
The wall will be exactly as tall as it was after a bad month, and the next brick will still cost $50. That is how quiet savings actually gets built.
Lay Your First Brick Tonight
Open your banking app now, set a recurring $50 transfer for the day after your next paycheck, and write your brick count on a piece of paper. Then put the paper away.

Hello there! I’m Jesse Joe, the author and editor behind SolganGenius. I’m thrilled you’ve stopped by, and I can’t wait to share with you the essence of what this platform is all about.
I’m a writer, social media enthusiast, and a firm believer in the power of words. I’ve always been fascinated by how a simple phrase or slogan can capture an emotion, convey a message, and even change perspectives. Learn More