Hitting a million in retirement savings is supposed to make everything easier, not harder. But here's the twist: that number can turn into a burden the moment you share it with the people around you.
One casual admission at a family dinner has quietly unraveled retirements for people who did everything right. Thoughtful savers. Careful planners. The ones you would least expect to get tripped up.
This isn't about keeping secrets for the sake of it. It's about understanding what that million actually is in retirement, how quickly other people's expectations can shift once they hear it, and why the smartest move might be to tell no one.
You'll learn the exact scripts to deflect money requests and how to run your own numbers so you're never guessing about what that million can safely provide.
People hear a million and picture unlimited spending
Sharing the number changes how people see you because the word million carries a weight in this culture that has almost nothing to do with how a retirement portfolio actually works. We've been trained by two phrases: self-made millionaire and millionaire next door. Both make it sound like a finish line, a gold plaque you hang on the wall.
So when you say you retired with a million, that's the image that lands. Listeners picture you picking up every dinner tab, writing a check to bail out a nephew, booking flights whenever the mood hits. It sounds like freedom with no ceiling.
What they don't picture is the machinery underneath. The withdrawal rate. The taxes that come off the top. Inflation grinding at purchasing power for 25 or 30 years. Healthcare premiums that climb faster than everything else. A plan that has to survive three decades of uncertainty, and one really bad market at the wrong time.
Here's the part that catches people off guard: this shift happens even with people who genuinely care about you. Your grown children, your brothers and sisters, your dearest companions. They don't decide to see you differently. They just do, quietly, in the back of their minds.
You think you're sharing a fact. They hear that you're rich and set. That gap between what you said and what they heard is where the trouble starts.
Your million looks huge beside their smaller balance
Your million seems enormous to them because they're measuring it against their own balance sheet, not against a retirement plan. And the typical retiree has far less than you'd guess. Federal Reserve data puts median net worth for people aged 65 to 74 around $400,000. Your million is more than double what the middle of the pack actually holds.
Put a face on that. A friend might have about $150,000 sitting in a 401(k), or still be chipping away at a mortgage and a credit card balance. Even a relative who saved diligently could be well behind your number without ever saying so.
That comparison colors every financial conversation you have with them. To their eyes, your million is a fat cushion, a soft landing, a safety net with room to spare. To you, it's a finite engine running under strict rules, and the rules don't bend because someone's roof needs replacing.
So when they say some version of you can afford it, they're not being cruel or calculating. They're looking at your number through their own lens, comparing it to the smaller figure in their account and concluding you barely feel the cost.
That's exactly why the exact balance is worth keeping to yourself. Once someone anchors to a number, every request gets measured against it instead of against what the plan can actually give up.
⚠️ COMMON MISTAKE
The Number Changes the Relationship
Once family hears an exact figure, they start treating your money as a shared resource. The shift is subtle but real, and it happens even with people who love you.
One honest answer turned parents into the family bank
After you tell family the actual number, you quietly become the default source of financial help, and it can happen from a single honest sentence. Take Jim and Pam. They retired in their early 60s with just over $1 million spread across IRAs and a 401(k), with Social Security still coming down the road.
At a family gathering, someone asked how retirement was going. Jim shrugged and said that yeah, they'd ended up right around a million. From his side of the table, he was just answering the question. No boasting, no drama, just a fact.
But the roles shifted in that moment. Their adult child started exploring homeownership and came back with a request for a six-figure down payment. To the child, it seemed reasonable, even modest: it's only a small share of your money, so paying it wouldn't strain you at all.
That's the trap. The child was comparing the request to the total, not to the retirement plan's actual needs. A hundred thousand sounds tiny next to a million. It's also two and a half years of the roughly $40,000 a year that $1 million supports at a 4% withdrawal guideline, before taxes even come off.
Jim and Pam didn't lose a million dollars that day. They lost something quieter and harder to recover: the ability to answer a request without a family member doing mental math on their net worth first.
Once family sees plenty, saying no feels selfish
Saying no becomes hard because once family believes you have plenty, refusing the ask starts to feel less like prudence and more like greed. The arguments run through your own head, not theirs. We do have enough, so shouldn't I step in? They're struggling and we're technically millionaires, are we being selfish here?
That guilt is what pushes retirees into emotional spending. It isn't tied to any plan, any spreadsheet, any withdrawal schedule. It's tied to a feeling in your chest at the moment someone asks, and that's the most expensive way there is to make a financial decision.
It usually starts small. A little loan here, a gift there, help through a rough patch that feels like a one-time exception. And each one genuinely is small. The problem is that small choices compound for years, and the exceptions stop feeling like exceptions.
One couple turned into the go-to lender whenever a relative hit a crisis. They were quietly tightening their own budget, buying cheaper groceries, skipping things they'd planned to do, and they were afraid to admit it because everyone around them believed they were rich.
That's the real cost. The retirement structure gets chipped away from the outside in, a few thousand dollars at a time, and quiet resentment builds on both sides. You resent being asked; they resent feeling judged when you hesitate.
Friends expect you to pay and stop feeling equal
Friendships change once friends know your number, and the change is usually subtle before it's obvious. You're out to dinner and the check lands on the table, and suddenly everyone is very comfortable letting you pick it up. Nobody says it out loud. Nobody has to.
Then a group trip gets planned. Come on, you're retired. Or the other version: you've got that million, you can make it work. It's said with a smile, and underneath the smile is an assumption that your money is doing less important work than it actually is.
Some friends get a little too comfortable with your money. Others get uncomfortable with their own, and that's its own kind of distance. Money slides in an invisible scorekeeping that wasn't there before, and nobody agreed to keep score.
Here's the sharp edge. Jokes about you being the rich one are fine while they're jokes. Let them sit long enough without an offer of help attached, and somebody's feelings get bruised. Now your generosity isn't appreciated anymore. It's expected.
The friendships that survive this are the ones where nobody knows the figure. Without a number to measure, people still split the check, still pay their own way, still see you as the friend who retired early. Not the rich one.
What $1 Million Actually Means vs. What They Think
What They Picture
- Unlimited flexibility and endless cash
- You can pick up every tab
- You can bail out family whenever needed
- You can travel whenever you want
The Reality
- Roughly $40,000 a year from a 4% withdrawal
- Must cover healthcare, inflation, and repairs
- Needs to last 25–30+ years
- Requires careful tax and withdrawal planning
A million is closer to just enough than excess
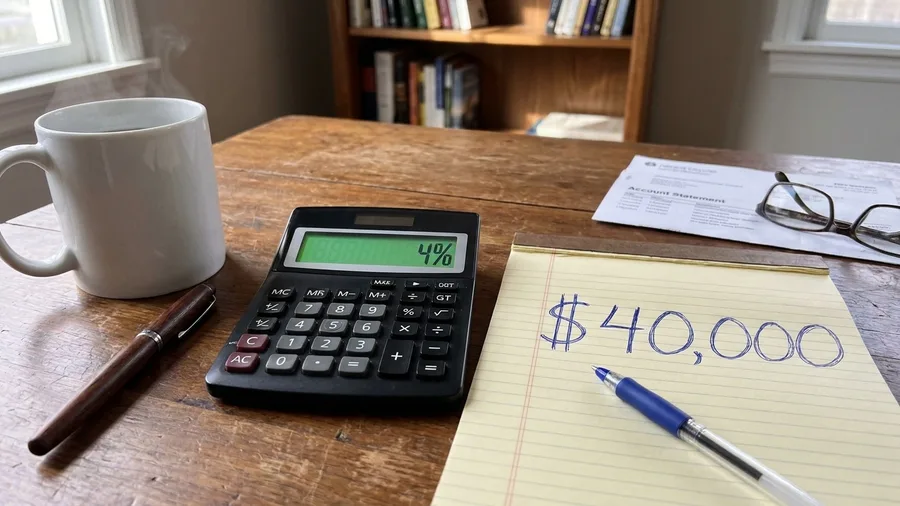
A million sounds like a finish line. In retirement it's a working number, and for most people it lands closer to just enough than to any kind of excess.
Here's the arithmetic everyone quotes. The old 4% guideline says a $1 million portfolio can throw off roughly $40,000 a year before taxes. That's it. Four percent is the whole payday.
And that $40,000 has a lot of jobs to do at once. It covers everyday living expenses, healthcare that tends to rise faster than everything else, inflation quietly eating purchasing power, the occasional new roof or furnace, and whatever generosity you actually want to build in. Four jobs on one paycheck.
Behind the scenes the money runs under strict rules. There's a withdrawal order to think through so you're not paying more tax than you need to. There's sequence-of-returns risk, which is a fancy way of saying a bad market in your first ten years does more damage than the same drop later on. And there's inflation, which doesn't take a year off because you retired.
The hardest part is what happens once you stop working. Every dollar you spend is a dollar you can't earn back with a few more years at the desk. Replace it from where? That faucet is closed.
So the engine has to keep running for 25, 30 years or more. Picture the family at that gathering hearing "a million" and imagining endless freedom, while you're quietly managing a machine that has to last three decades. Same number, very different picture.
The $1 Million Reality Check
Pension framing turns the conversation to safe income
Stop talking about the pile and start talking about the paycheck. When someone asks how the money works, the most useful thing you can say is that it functions like a pension you built yourself.
That reframing does real work. A pension pays an income. Extra withdrawals shrink the income permanently, because the money was never sitting there as a lump sum for gifts. It's the engine, not the fuel tank.
Then have the separate conversation about family help. Offer to help problem-solve, to look at a budget, to talk through options. Don't hand out lump sums. That keeps the door open without turning the portfolio into a withdrawal window.
The script for children, if it comes up: "This is our retirement income. If we spend it, we may have to go back to work or rely on you." The second half is the part that lands. It's honest, it's true, and it turns the request into a shared problem instead of a one-way ask.
What makes this framing so useful is that it isn't spin. It's an accurate description of how the money actually behaves, which means you can say it without flinching and keep saying it for years.
Small repeated yeses quietly raise the withdrawal rate
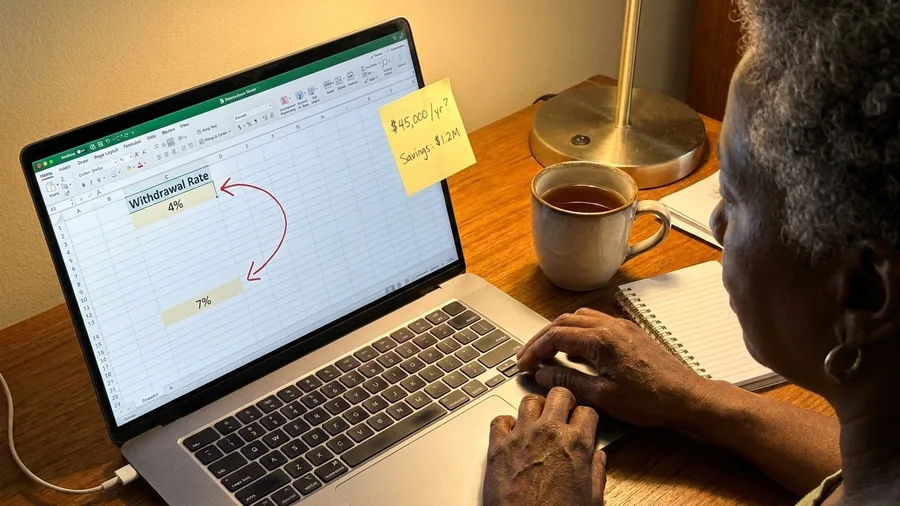
Small gifts hurt a plan because they're unplanned, they usually land in early retirement when the portfolio is most fragile, and they teach people to expect more.
For Jim and Pam it went like this. First $5,000 to help a child through a rough patch. Then $8,000 toward a down payment. Then paid family trips, one after another. Each decision felt small, emotionally reasonable, and like a one-time exception. Refusing, in the moment, felt unkind.
That's the trap. None of these asks arrives as a category called "ongoing support." They arrive as emergencies, one at a time, and each one makes sense on its own.
Then they reviewed the spending. The withdrawal rate had climbed from a safe 4% to 6% or 7%. Nobody had made a terrible decision. There had just been a lot of reasonable ones.
The good news: it didn't wreck their retirement. The bad news: it narrowed their options, and the stress of it could have been avoided entirely. That's the thing about a rising withdrawal rate. It rarely blows up the plan. It just quietly shrinks the room you have to maneuver.
⏰ How Expectations Build After You Share the Number
You Share the Figure
A casual mention at a family gathering seems harmless.
They Recalculate
Family members compare your million to their own smaller numbers and see a cushion.
Requests Begin
Small asks and bigger ones start coming, framed as a small percentage of your wealth.
Guilt Sets In
Saying no feels selfish; you start spending emotionally.
Withdrawal Rate Rises
The extra spending pushes your withdrawal rate from 4% toward 6–7%.
Privacy about the exact balance protects the plan
Your exact balance is need-to-know, and the list is shorter than you'd think. Your spouse, your financial planner and your accountant can know. That's the core group.
Your estate plan may name one trusted person, someone who needs to understand the structure if something happens to you. That's a role, not an invitation to discuss it at dinner.
Your kids, siblings and friends don't need a single number to love you or support you. They can be a full part of your life without knowing your balance. Being asked "how much do you have?" is not a request for disclosure, and you're allowed to answer something vague and move on.
This isn't lying. It's being intentional about who needs the number and when. Keep in mind what happens when a figure gets out. Expectations form around it, and once they form they're very hard to unform.
The right time for the next generation to discuss figures is when the money actually transfers, not the day you retire. Retire quietly. Let the estate plan do the talking when the moment arrives. Before word gets out, consider what to upgrade before telling anyone while you still control the information.
💡 PRO TIP
The Boundary Script
Say: 'We have a plan in place with our adviser and we're being careful with what we say yes to.' It's polite, firm, and doesn't reveal a number.
Boundaries work best before anyone expects help
The best answer to a money request is a line you've already practiced, said before anyone assumed anything. Timing is most of the work here.
If you wait until the request lands on the table, every version of no sounds like rejection. Set the boundary while it's still hypothetical and it reads as planning, not refusal.
Three lines worth memorizing. One: "We have a plan in place with our adviser, and we're being careful with what we say yes to." Two: "We're happy to help problem-solve, but we aren't in a position to be the family bank." Three: "We've structured things so we don't outlive our money, so we can't always say yes even when we want to."
Notice what all three have in common. They move the spotlight from your generosity to your plan. They remind family that the money has a job, which is funding your retirement, and that the job comes first.
Say them early, say them calmly, and repeat them without apology. The earlier the boundary goes up, the less awkward it ever becomes, because nobody has to be the villain. The plan is the reason, and the plan doesn't take it personally.
When to Say Yes, Caution, or No
- Request is built into your plan — You've already budgeted for it and it won't raise your withdrawal rate.
- It's a one-time small gift, but unplanned — Check what you'll say no to later; if it pushes your rate above 4%, think twice.
- Six-figure down payment or ongoing support — This is a lump sum that could derail your income plan. Say no.
- You feel guilty saying no — Emotional spending is a red flag. Stick to the plan.
Test every request against the plan, not the balance
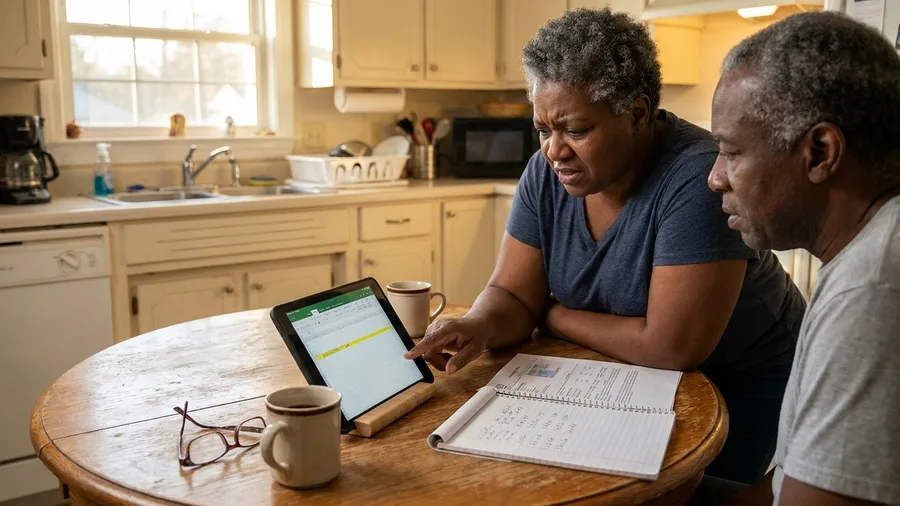
You decide whether to help by asking one question instead of another. Swap "Do we have the money?" for "Is this built into our plan?" The balance on the statement has nothing to do with it. What matters is whether the cash flow can carry the gift without breaking somewhere else.
Jim and Pam had just over a million spread across IRAs and a 401(k), and on paper a $8,000 request for a child's down payment barely dented it. That's exactly the trap. The portfolio has to fund 25 to 30 or more years of living costs, healthcare, inflation and repairs, and at a 4% withdrawal guideline it throws off roughly $40,000 a year before taxes. Take $8,000 out for someone else and you're not spending a rounding error. You're spending a fifth of a year's safe income in one afternoon.
So before you answer, ask what saying yes here means saying no to later. Maybe it means one less trip. Maybe it means a thinner cushion if a roof goes or a health scare lands. Then ask the honest follow-up: is that trade-off acceptable to you?
Here's the part people don't like hearing. If saying no is possible, there's a good chance you should. Unexpected costs show up constantly, and staying on track matters more than being the hero at the table. When spending reviews show the withdrawal rate creeping from 4% toward 6% or 7%, that's the plan quietly telling you the answer.
Run this test on every ask and the decision stops being emotional. It becomes arithmetic, and arithmetic doesn't text you back at midnight feeling guilty.
The 4% Withdrawal Rule at a Glance
💰 Portfolio
$1,000,000
📈 Withdrawal Rate
4%
💵 Annual Income
$40,000
🏦 Pre-Tax
Yes
Key Point
This income must cover all living expenses for 25–30+ years.
Silence buys relationships based on who you are
Keeping the number to yourself buys you something no financial plan can: freedom from pressure. When nobody knows the balance, nobody is doing math on your behalf at Thanksgiving. Relationships stay anchored to who you are, not what you have, and that alone is worth more than the interest on the money.
It also keeps your decisions clean. You weigh a request against the plan, not against a sense of guilt or obligation to someone who's been counting your zeros. That clarity is the whole point of privacy. It's not secrecy for its own sake. It's removing the noise that makes good people make bad calls.
The retirees who make a million last treat it as a finite resource. They don't show it off or talk it up. They protect it quietly, the way Jim and Pam learned to after that first six-figure ask turned the family bank open. And a portfolio treated that way gets the best possible chance to do what it was built for: fund 25 or 30 years of the life you actually want, not the version everyone else has planned for you.
So when the next gathering comes and someone asks how retirement's treating you, you don't owe them a number. Smile and say, "We're doing fine, thanks to our plan." Then leave it right there. The silence isn't cold. It's the reason the relationships and the money both survive.
Frequently Asked Questions
Should I tell my adult children how much I have saved for retirement?
It's generally best not to share the exact number. They don't need a dollar figure to love and support you. If you want to discuss inheritance, do it when you're transferring assets, not at retirement.
What if my family already knows my net worth?
You can still set boundaries. Use the pension-income framing: 'This is our retirement income, and if we spend it, we may have to rely on you.' It shifts the focus to the plan.
How do I say no to a family member who asks for money?
Try: 'We have a plan in place with our adviser and we're being careful with what we say yes to.' Or: 'We've structured things so we don't outlive our money, so we can't always say yes.'
Does a 4% withdrawal rate still make sense?
It's a common starting point, but your actual rate depends on your expenses, risk tolerance, and market conditions. Many retirees adjust it based on their situation.
What's the biggest risk of giving money to family in retirement?
Unplanned withdrawals can raise your withdrawal rate and deplete your portfolio faster, especially in early retirement when sequence-of-returns risk is highest.
The One Rule That Keeps Your Million Working
You've seen how sharing your number can shift relationships, invite requests, and quietly raise your withdrawal rate. The solution isn't to lie; it's to be intentional about what you disclose.
Keep the exact balance private. When someone asks about your finances, answer with the pension-income line: 'We're managing our retirement income carefully.' That's all they need to know.
Your million is an engine, not a jackpot. Protect it, and it will fund the life you actually want.
Before the Next Family Gathering, Decide Your Script
Pick the pension-income line you'll use and commit to keeping your exact balance private. Practice it once out loud tonight.

Hello there! I’m Jesse Joe, the author and editor behind SolganGenius. I’m thrilled you’ve stopped by, and I can’t wait to share with you the essence of what this platform is all about.
I’m a writer, social media enthusiast, and a firm believer in the power of words. I’ve always been fascinated by how a simple phrase or slogan can capture an emotion, convey a message, and even change perspectives. Learn More