Everyone says you need $2 million to retire. The financial media repeats it, calculators assume it, and forums treat it as the new baseline.
But how many people actually have it? The answer, according to the central bank's data and its household wealth study, is not what you expect, and it changes how you should think about your own savings. This article walks through the real numbers, what they count, and what matters more than hitting a round target.
You will see exactly how rare $2 million is, why net worth and retirement savings get mixed up, and what to do if you are closer to the middle of the pack.
How many households actually hold $2 million
About 1.8% of US households hold $2 million or more in retirement accounts and liquid assets. That is fewer than 2 in 100.
Put another way, walk into a room of 100 households and roughly two of them have the stack you keep hearing about. The other 98 do not.
You do not have to take that on faith. The figure comes from Federal Reserve data, specifically the Survey of Consumer Finances, the same dataset economists use to study wealth in this country. It is checkable, not a guess somebody repeated on a podcast until it felt true.
So here is the part that should settle your stomach a little. The claim going around is that $2 million is the new baseline, the bare minimum, the money myth inside the new retirement math you should be embarrassed to miss. The data says otherwise. It is an outlier, not a baseline. It is the top edge of the distribution, not the middle of it.
And remember what that 1.8% is counting. Retirement accounts and liquid assets only. It leaves out your home, your business, your coin collection, everything else you own. This is not a flattering definition that scoops in the house to pad the ranks. If anything, it is the strict version.
Which means the real share of households that are genuinely set on retirement money alone is smaller still than a lot of people assume, and it was never the standard you were supposed to clear.
| Retirement portfolio | Share of US households | Roughly 1 in |
|---|---|---|
| $500,000 or less | About 90–91% | 9 in 10 |
| $1 million or more | 4.7% | 20 |
| $2 million or more | 1.8% | 55 |
| $3 million or more | 0.8% | 125 |
| $5 million or more | 0.1% | 1,000 |
Net worth and retirement savings are different numbers
They contradict each other because they are measuring two different things, and most people quote one while picturing the other.
Net worth is the big bucket. It includes the equity in your house, any rentals you own, stakes in a business, taxable investing accounts, retirement accounts, and even the used cars in the driveway.
Retirement savings is the narrow bucket. That means 401(k)s, IRAs, Roth IRAs, pensions, and other liquid portfolio assets. This is the money that can actually generate income once the paychecks stop.
Here is the cleanest way to see it. Picture a household with a $1.2 million house and $800,000 invested. They have $2 million of net worth on paper, but only $800,000 of money that produces income. Same household, two very different statistics, and the gap between them is $1.2 million of roof and walls.
Why does the mix-up change your answer? Because the same family can look wealthy on one measure and perfectly modest on the other. Quote net worth and they are millionaires twice over. Quote the liquid side and they are in a far more ordinary crowd. Nothing about them changed, only the ruler.
And in retirement, only the liquid side pays the bills. The house does not mail you a check every month unless you sell it, rent it, or borrow against it, and each of those has its own cost.
So when you read a shocking number, check which ruler is being used before you let it worry you.
Only about 1 in 20 reach $1 million
It is not common. About 4.7% of US households hold $1 million or more in retirement savings, roughly 1 in 20.
Since we just drew the line between net worth and the liquid side, this is the liquid side talking. Not millionaires by total wealth, which is a much bigger group. Millionaires inside a retirement account, which is a much smaller one.
The number comes from central bank figures crunched by the Employee Benefit Research Institute, so it is a solid benchmark rather than a marketing claim.
Now hold that next to how the million-dollar mark gets talked about. It is treated as the entry ticket, the floor, the warm-up lap before the real money starts. But if only 1 in 20 households clears it, the floor is really the exception.
Here is the useful takeaway. If you have been quietly measuring yourself against a million and coming up short, understand that the people around you are mostly in the same boat. The milestone got repeated so often that people started believing it was average.
It is not. It is a fairly rare place to land, and landing near it is not a failure.
💡 PRO TIP
Check your own definition first
Before you compare yourself to any statistic, write down two numbers: your total net worth and your retirement account balances. They answer different questions, and only the second one tells you what you can spend.
The $2 million club is smaller than advertised
It counts retirement accounts, and it narrows the field more than most people realize. About 1.8% of households, fewer than 2 in 100. That bears repeating, because the claim is so common that it starts to feel like background noise.
This is the strictest, most relevant measure of retirement readiness we have. It covers retirement accounts, and it excludes homes, businesses, and other investments. No house equity propping up the total, no business valuation, no rental property doing quiet work in the background.
So ask yourself which direction that pushes the argument. The claim is that $2 million is the new normal. The narrower definition makes that claim look even more inflated, not less.
If fewer than 2 in 100 households have $2 million in retirement accounts, it cannot be the standard everyone is expected to meet. A standard that one in fifty people hits is not a standard. It is a summit.
This is the part that gets skipped when the number gets thrown around. Quoting a share of households with $2 million in retirement accounts and calling it the baseline misreads what the figure is: the far end of a curve, not the yardstick in the middle.
Retirement Wealth at a Glance
🏠 Net-worth millionaires
18% of households
💰 $1M+ in retirement accounts
4.7%
💎 $2M+ in retirement accounts
1.8%
🏆 $3M+ in retirement accounts
0.8%
🚀 $5M+ in retirement accounts
0.1%
The takeaway
The higher the balance, the dramatically smaller the group. $2 million is rare, not routine.
Every extra million puts you in a smaller group
It looks almost empty, and it thins out faster than the money grows. About 0.8% of households hold $3 million or more in retirement accounts. About 0.1%, or 1 in 1,000, hold $5 million or more.
Now look at the other end of the same curve. An estimated 90 to 91% of the population holds less than $500,000 in retirement accounts and liquid assets combined.
Read those two facts together and you can see the shape of it. The club shrinks far faster than the balance grows. Going from $2 million to $3 million adds half again to your money, but it cost you more than half the crowd you were standing in. Each extra million moves you into a dramatically smaller segment.
For you, that means the top is thinner than it looks from the middle. From where you sit, surrounded by retirement articles and confident thresholds, it feels like everyone up there is crowding into the same group. The data says that group is a rounding error.
Which is a strange kind of relief. The goal was never to join the smallest group in the room. It was to make your own number work, and for almost everyone that number sits well below the top of this curve.
Doubling from $1 million is the hardest step
Getting from zero to a million is hard. Getting from a million to two is harder, and the data proves it.
Roughly 4.7% of US households hold $1 million or more for retirement. Only 1.8% reach $2 million or more. Read those side by side and the message is blunt: most households that clear the first million never clear the second. The gap between those two groups is the widest rung on the whole ladder.
Why does it work that way? The first million usually has decades of contributions behind it. You started in your thirties, you kept adding, and compounding quietly did the heavy lifting over 25 or 30 years. The second million has to be built in a much shorter window, with retirement already in sight and less time for the math to work in your favor.
And frankly, the second million often gets pulled backward. Kids, a mortgage payoff, a health scare, a career wobble – the same years you need to save hardest are the years life tends to send bills.
That said, this does not apply to everyone. If you are 20 years out and saving aggressively, the second million can be an ordinary target rather than an exception – plenty of time, plenty of compounding, no need to sprint.
The point is to know which situation you are in. Look at your years remaining, your contribution rate and what your balance needs to grow to. Then decide whether $2 million is a realistic goal or a number you can let go of.
Where does your portfolio sit?
- $500,000 to $1 million — You are ahead of the pack. Watch withdrawal order and taxes.
- $1 million to $2 million — Solid position. The next step is tax-efficient drawdown.
- $2 million or more — Rare company. Now the risk shifts to taxes and spending discipline.
- Under $500,000 — Most households are here. Focus on savings rate and Social Security timing.
- Net worth over $1 million but little liquid — Paper wealth without income. Consider downsizing or a reverse mortgage.
Counting net worth makes millionaires look ordinary
Switch the measuring stick to total net worth and millionaires stop looking rare – but that wealth is mostly a house that pays you nothing until you sell it or borrow against it.
About 18% of US households are millionaires by total net worth. By retirement accounts, only 1.8% are. That is a tenfold difference from the same population, and it explains a lot of the confusion.
So where does the money sit? Mostly in real estate. A house is real wealth, but it produces no income unless you sell it, rent it out or take a loan against it. It is not money you can spend on groceries, and it does not pay a Medicare premium.
The recurring pattern is a household with $1 million of net worth and only $100,000 to $200,000 in retirement or liquid assets. On paper, wealthy. In monthly cash flow, squeezed the moment the paycheck stops.
a $1.2 million house plus $800,000 in retirement accounts equals $2 million of net worth, but only $800,000 of income-producing money. That $800,000 has to carry the whole retirement.
So when everyone else seems richer than the retirement data says, they may be counting their house. You are comparing two different scoreboards, and only one of them pays your bills.
Retirees are even less likely to hold millions
Narrow the lens to people already retired and the share holding $2 million drops below the household figures – the retiree percentage at that level is smaller than the overall number, and it is small.
Just about 3.2% of retirees hold $1 million or more for retirement. The share at $2 million is smaller still. No one publishes an exact figure, so be careful with anyone who quotes one to the decimal.
Why do retirees score lower? Because once the paychecks stop, the forces all point the same way. There are no new contributions, withdrawals are running, and the balance is what is left rather than what was built. Time and spending work against you.
Picture a couple who spent 30 years saving well. The moment they retire, that account flips from filling to draining, and every year of withdrawals makes the $2 million mark that much harder to hold. Few people ever get there, and some who do slide back below it.
One caveat worth carrying: these figures come from household surveys, which sample people and extrapolate. Treat any exact retiree percentage quoted elsewhere with suspicion. The direction is clear even if the decimal is fuzzy.
What matters for you is the trend, not the precision. If you are retired and nowhere near $2 million, you are in the overwhelming majority – not the exception.
Keeping $2 million is harder than reaching it
Once you have $2 million, a lot can go wrong – and most of it is quiet, structural and invisible until you look at the tax return.
Several forces start pulling at once: required minimum distributions, income tax on withdrawals, income-linked Medicare premiums, taxable Social Security, market swings and inflation. None of them feels dramatic on its own. Together they are a steady leak.
The consequence is that a balance can fall faster than the owner expects, even without extravagant spending. Retirement can run 25 to 30 years, and small leaks compound just like returns do – only in the other direction.
Say a couple starts with $2 million and draws a modest 4%, or $80,000, in year one. Add income tax on those traditional withdrawals, a Medicare surcharge once income crosses a threshold, and a bad market year, and the real draw can quietly climb well past the plan.
which accounts you draw from, in what order, and how much you convert before RMDs hit.
A target number is not a plan. The $2 million is the starting line, not the finish.
Big traditional accounts build a tax bill
How much tax you owe on withdrawals depends on how much of your money sits in traditional accounts – and the bigger that pile, the bigger the bill, whether you need the cash or not.
Traditional IRA and 401(k) money is pre-tax. The government has not yet had its share, and it will. Every dollar you pull out is taxed as ordinary income, and so is every dollar the IRS forces you to pull out.
That is what RMDs do. Required minimum distributions push taxable income onto your return whether or not you need the money. With a large balance, those forced withdrawals can tip you into a higher bracket in the very years you wanted a lower income.
Then there is IRMAA, which is an income-based surcharge on Medicare Part B and D premiums. In plain terms, a higher income two years back means a higher premium now. Check the current thresholds and the appeal route on the official Social Security and Medicare sources rather than trusting a number quoted in passing – the limits move.
Large RMDs also make more of your Social Security benefit taxable, so the hit stacks. A $2 million traditional balance is not $2 million of spendable money. Judge it after tax, not at face value.
The fix, as we will see, is to use the years before RMDs begin.
📅 The Roth conversion window, step by step
Retire
Your taxable income often drops in the first year without a paycheck.
Check 73
RMDs begin at age 73, so the years before that are your window.
Size the conversion
Convert enough to fill the bracket you are willing to pay, not more.
Pay tax from taxable money
Do not withhold from the converted amount; use cash from a taxable account.
Repeat annually
A measured conversion each year beats one big move.
Check Medicare income
Remember IRMAA looks back at earlier income, so a large conversion can raise later premiums.
The years before 73 are your tax window
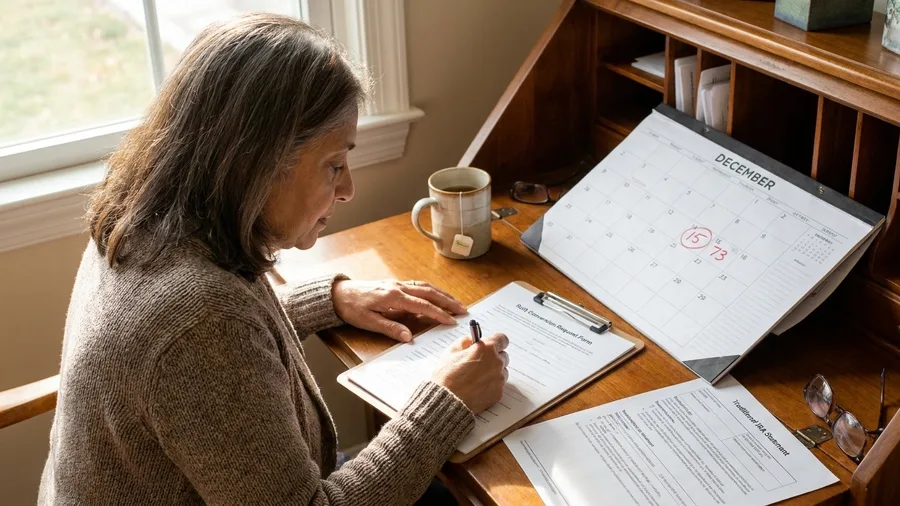
Do it by moving pre-tax money in the years between your last paycheck and age 73, when the required withdrawals start. That stretch is usually the cheapest tax window you will ever get, and most people waste it by doing nothing.
Here is why the window is open. Once you stop working, your taxable income often drops – no salary pushing you into a higher bracket. Until 73, nobody is forcing money out of your traditional accounts. You decide how much comes out and when. That control is the whole opportunity.
So how much do you convert? Size each year's conversion to stay inside the bracket you are actually willing to pay. If you are comfortable with the 22% bracket, convert up to the top of it and stop. Do not let the tax tail wag the dog and push yourself into a rate you will resent.
Now the part people forget. Medicare's income surcharge looks back at your income from two years earlier. A big conversion can quietly raise your premiums later. Check that before you finalize the number, not after.
Two mechanics trip almost everyone. First, pay the conversion tax from taxable money outside the account – if you withhold it from the converted amount, you lose the growth on that money and may owe a penalty if you are under 59 and a half. Second, repeat a measured conversion every year instead of doing one giant move. Ten smaller conversions inside your bracket beat one that spikes you into the top rate.
That is the difference between a tax bill you chose and one that chose you.
Build vs. Spend: Two Different Problems
Building the portfolio
- Contribute consistently for decades
- Focus on savings rate
- Let compounding work
- Target a number and track it
Spending the portfolio
- Plan withdrawal order and timing
- Manage taxes and RMDs
- Coordinate Social Security and Medicare
- Review once a year
The number matters less than the drawdown
It matters less than what you do with it, because two retirees with the same balance can end up living very different retirements. The gap is not the number. It is how they pull the money out.
Picture two people, both with $2 million. One draws from traditional accounts first, pays ordinary income tax on every dollar, and hits required withdrawals later with a bigger balance still sitting there. The other draws taxable money early, converts some traditional money in the low-tax years, and holds the Roth for later. Same starting line, different finishing line.
Across 25 to 30 years, that difference is not cosmetic. A well-sequenced plan can squeeze noticeably more spendable income out of the same pile – the same balance supporting a higher standard of living because less of it leaks out to tax along the way.
So what does good look like? A written order for which accounts get drawn in which years, reviewed once a year. It does not have to be complicated. It has to be written down, because a plan in your head gets abandoned the first time the market drops and you panic.
The number gets you to the door. The drawdown decides what kind of room you are standing in.
What $2 million actually pays you each year
At a 4% first-year withdrawal, $2 million pays you $80,000 before tax. That is the standard planning convention, and it gives you a starting point – not a promise.
Now start subtracting. If that money sits in traditional 401(k)s and IRAs, ordinary income tax comes off the top. At a 22% rate, that $80,000 drops to roughly $62,400 you can actually spend. And required withdrawals force a rising percentage out of the account as you age, whether you need it or not.
The order you draw from matters too. Most people take taxable accounts first, then traditional, then Roth last. Changing that sequence shifts your lifetime tax bill, sometimes by tens of thousands of dollars. It is not a detail. It is the plan.
Here is your next step. Rerun this with your real tax rate and your own Social Security estimate instead of accepting the numbers above. The math is simple – $2 million times 4%, minus what the taxman takes – but the answer has to be yours, not a rule of thumb borrowed from a stranger.
If $2 million was never in the cards
Then the target changes, and that is fine. Plenty of people retire comfortably on far less than $2 million – they just build income from different sources instead of one big pile.
Start with Social Security. Delaying your claim is the cheapest inflation-adjusted income most people can buy, and you cannot outlive it. Get your own estimate at ssa.gov rather than trusting a percentage someone quotes you. The difference between claiming at 62 and waiting can be substantial, and it is money you cannot replicate anywhere else.
Next, a partial annuity can cover your essential bills – the rent, the utilities, the groceries – so the market does not decide whether you eat. Get a quote for your age and check it against your state guaranty association limit before you sign anything. That limit is your safety net if the insurer fails.
Your house can become income too, through downsizing or a reverse mortgage. Both trade a home for cash, and neither is free money. One means leaving; the other means borrowing against equity you may have wanted to leave to your kids.
Which option fits depends on your health, your home equity, and how much you actually spend. And if none of them work, the spending cut has to happen somewhere. Better to choose it now than have it choose you.
Frequently Asked Questions
What percentage of retirees have $2 million?
No precise figure is published for retirees specifically, but it is smaller than the 1.8% of all US households that hold $2 million or more in retirement accounts. Only about 3.2% of retirees have $1 million or more, so the $2 million share is smaller still.
Is $2 million in retirement savings considered rich?
By retirement account balances, yes. It puts a household in roughly the top 2% of US households. But by total net worth, 18% of households are millionaires, so it depends on which measure you use.
How much can I withdraw from $2 million each year?
A common starting point is 4%, or $80,000 before tax in the first year. That is a planning convention, not a guarantee. Your actual spendable amount depends on taxes, RMDs, and market returns.
Do I need $2 million to retire comfortably?
No. The data shows most households retire with far less. What matters more is how you draw down what you have, when you claim Social Security, and how you manage taxes.
What is the 4% rule and is it still valid?
The 4% rule is a rough guide for first-year withdrawals, adjusted for inflation. It is a starting point for planning, not a promise. Many planners now suggest a more flexible approach based on market conditions.
The number worth acting on is the one you can count
If you have been measuring yourself against $2 million and feeling behind, the data should ease that. Only about 1.8% of US households hold that much in retirement accounts. It is a rare outcome, not a personal failing.
The number worth acting on is your countable portfolio, not your net worth. This month, total the accounts the statistic counts: your 401(k)s, IRAs, and other liquid assets. That is the figure that pays your bills.
And if you are between retirement and age 73, put the conversion window on the calendar. A measured Roth conversion each year can change what your balance is worth after tax.
Add up your countable portfolio today
Total your retirement accounts and liquid assets this week. That is the number your retirement plan should be built around.

Hello there! I’m Jesse Joe, the author and editor behind SolganGenius. I’m thrilled you’ve stopped by, and I can’t wait to share with you the essence of what this platform is all about.
I’m a writer, social media enthusiast, and a firm believer in the power of words. I’ve always been fascinated by how a simple phrase or slogan can capture an emotion, convey a message, and even change perspectives. Learn More