Find your birth year. That one number decides which set of Social Security, Medicare and tax rules hits you in 2027 — and two people doing the exact same thing can end up in completely different places because of it.
One pays nothing extra. The other faces a lifelong monthly reduction. Same income, same paperwork, different birthday.
The boundaries between the groups shifted this year with little public explanation. One birth year becomes the first ever to see a full retirement age of 67. A tax break ends at a birth-year cliff. A New Year's Day rule quietly moves people between groups. And a widow's rule can hold a check below what was promised for life.
Below you'll find the four groups, the specific 2027 change to check first for each, and the money move that matters most. Sort yourself, then read the others too — if you're married, your spouse may be in a different group, and that gap is where couples lose money.
🎯 THE SHORT ANSWER
The quick answer
Your birth year places you in one of four groups: born 1950 or earlier, 1951–54, 1955–59, or 1960–66. Each group faces a different 2027 deadline, survivor rule, or tax cliff. Find your group, then act on its first item before December 31.
How we picked the four changes
Every 2027 rule change got sorted by birth year, and only four made the cut. They earned their place for one reason: each one carries a deadline, a penalty, or a tax cliff that costs real money if you miss it. The rest are noise.
Here is how the filter worked. A rule stayed if it moved a dollar amount for a whole birth-year band, not just a handful of edge cases. A rule stayed if waiting a month or filing a form late triggered an actual charge. A rule stayed if the IRS or Medicare set a line that a birthday could put you on the wrong side of. Four survived. Those four are the ones below.
Each one answers a question you probably already have. Skip the ones that do not apply, and read the ones that do twice. If your spouse landed in a different birth year, read their group too. The gap between two birth years under one roof is where couples quietly lose the most, because each of you can be obeying a different rule on the same day.
The figures here follow Social Security, Medicare and IRS rules as they currently stand. They are a map, not a guarantee. Before you claim anything or file anything, check your own numbers with the Social Security Administration or run them past a tax preparer.
At a Glance
1. Your birth year decides; January 1 can shift it
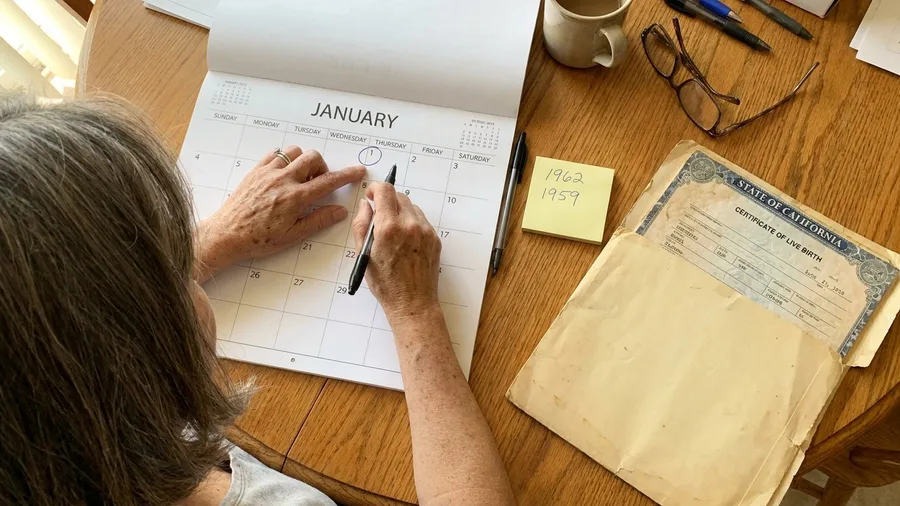
Sit down at the kitchen table with a pen and a sticky note. Before you apply a single rule in this article, write down your birth year and your spouse's birth year. That is your group.
First group: born 1950 or earlier. Second group: 1951 through 1954. Third group: 1955 through 1959. Fourth group: 1960 through 1966. Each carries its own full retirement age, its own Medicare date and its own tax phase-out lines, which is why two neighbors with identical savings can be playing by different rules.
Now the piece almost nobody has heard. Born on January 1, 1960? Social Security treats you as born in 1959. Your full retirement age is 66 years and 10 months, not 67. If your birthday falls on the first of any other month, you count as born the month before. That one-day nudge can move you back a whole band.
It sounds like trivia until you see the dollar difference. Two people with the same income face different full retirement ages, different earnings tests, different Medicare start dates and different tax phase-outs, because one birthday landed on the wrong side of a line. A person born December 31, 1959 and a person born January 1, 1960 are a day apart and 66 years and 10 months versus 67 apart on full retirement age. Run your spouse through the same check before you trust any calculator.
💡 Tip: A January 1 birthday shifts your whole timeline. Check your full retirement age on ssa.gov before you claim.
| Birth-year group | 2027 change to check first | Money move to review |
|---|---|---|
| Born 1950 or earlier | Survivor cap if spouse claimed early | Request the survivor computation in writing |
| Born 1951–1954 | First RMD lands in 2027 for 1954 births | Decide 2027 vs. April 2028 withdrawal |
| Born 1955–1959 | All past full retirement age in 2027 | Check if a spousal benefit has stopped growing |
| Born 1960–1966 | Medicare window and 67 full retirement age | Calendar Medicare and review Part D by Dec. 7 |
2. A widow's check is capped by his early claim
The survivor rule from that opening list is the one that catches more widows than any other, and it comes down to the age he claimed. If your husband claimed early, before his full retirement age, your survivor check is capped.
The rule uses whichever figure is bigger: the amount he was actually getting, or 82.5% of his full amount. Not 100%. Say his full amount would be $2,400 a month. He claimed at 62 and got about $1,800. Your survivor check is the larger of $1,800 or 82.5% of $2,400, which is $1,980. That is $420 a month less than most widows expect. If he waited to 70, the check grows to about $3,168, and you keep all of it.
There are two more edges. If he died before claiming and was already past full retirement age, the survivor benefit includes the delayed credits he earned up to the month he died. If he died before full retirement age without claiming, the survivor amount is figured from his full amount. And you never add your own check and the survivor check together, ever. You take the larger. Other widows have walked into the same survivor benefit mistakes and come out with smaller checks than they should have. Ask Social Security for the survivor computation in writing, showing which rule they used, and have that conversation at the kitchen table while you can both still sit at it.
💡 Tip: Name the likely survivor and the dollar figure they'd live on. Most couples have never said those two numbers out loud.
💡 PRO TIP
Get the survivor rule in writing
Social Security won't volunteer the calculation. Ask for the survivor computation in writing showing which rule they used. If the letter doesn't show it, request it before you accept the first payment.
3. IRA gifts, RMDs and spousal timing are traps
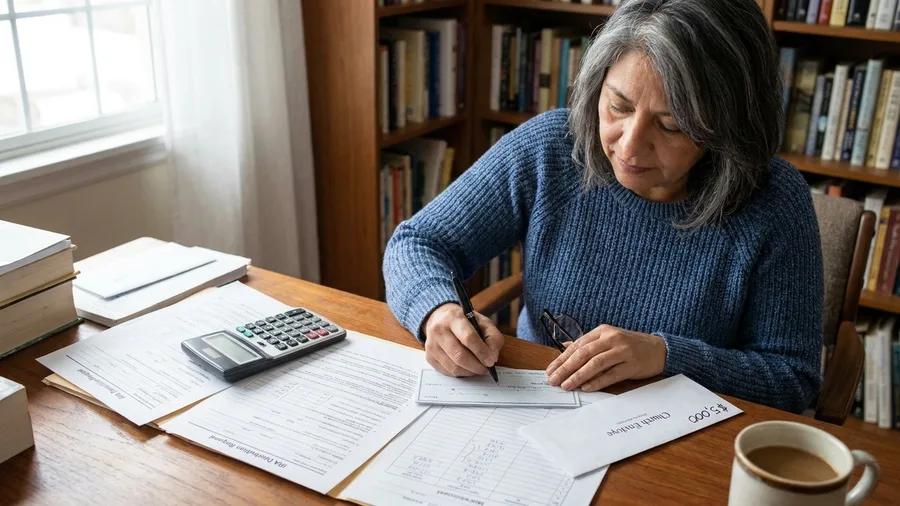
It depends on your group, and the rules are surprisingly specific.
If you are 70½ or older, you can send money straight from your IRA to a charity, a qualified charitable distribution, up to $111,000 in 2026, and it counts toward your required minimum distribution. It has to come from the IRA, not the 401(k). That matters because the $6,000 senior deduction starts shrinking above $75,000 single or $150,000 couple at 6 cents per dollar. A widow with $95,000 of income is $20,000 over and loses $1,200 of deduction. Send $20,000 from her RMD straight to charity and her income drops to $75,000, so she keeps the full $6,000.
Then the RMD trap. Born in 1954 means 2027 is your first required withdrawal year. On a $400,000 IRA that is about $15,100. Delay it to April 1, 2028 and you take two withdrawals in 2028, about $31,000. Miss one and the penalty is 25%, falling to 10% when you fix it within two years, and Form 5329 can request a waiver. The working-past-73 delay only applies to a current employer plan if you are not a 5% owner, never to your IRAs.
If you are the lower earner in a group-three marriage, your spousal benefit earns no delayed credits after full retirement age, and you cannot collect until your spouse files. Born in 1957? You turn 70 in 2027, and the check stops growing that month. If the first check looks smaller than promised, check again in January before you call.
💡 Tip: Name up to three representative payees while you're healthy. Social Security won't accept a power of attorney.
🗓️ Your 2027 deadline checklist
October 14, 2026
COLA announced; benefit notice lands in your online account in early December. Check it before your January deposit.
November 1 – December 7, 2026
Part D window. Switch on medicare.gov by December 7; the out-of-pocket cap rises to $2,400 and the deductible can go to $700.
December 15, 2026
Healthcare.gov closes. State marketplaces may run later. If you are 65 and still on a marketplace plan, move to Medicare now.
Your 65th birthday month
Seven-month initial Medicare window opens three months before you turn 65. Enroll then to avoid the 10%-per-year Part B penalty for life.
April 1, 2028
Last day to delay your first RMD if you were born in 1954. Take it by December 31, 2027 to keep one withdrawal in one tax year.
4. Medicare deadlines and 2027 claiming rules cost the most
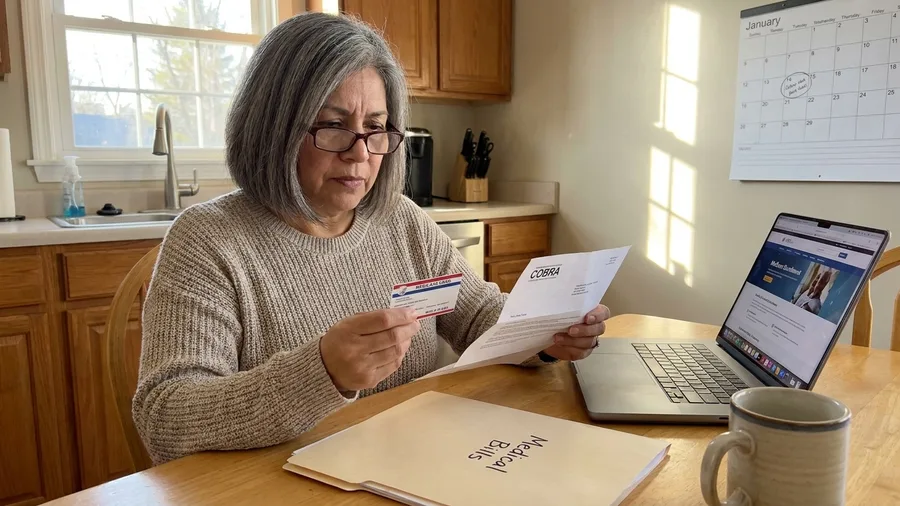
Medicare and claiming deadlines will cost this age group more than anything else on the list, because both bills arrive with a penalty attached for life. Born in 1962? You turn 65 next year. Your initial window runs 7 months: the 3 before your birthday month, the month itself, and the 3 after. Cobra does not count as coverage, and retiree coverage does not either. Once the job ends, you get 8 months to enroll in Part B, and a late Part B penalty is 10% per premium for life.
A retiree in Akron kept Cobra after leaving his tire plant and never signed up for Part B. Fourteen months later, surgery and follow-up care came to about $26,000. His Cobra plan paid only the portion Medicare would have covered, roughly a fifth. He owed about $20,800, and because his window had closed, he now pays the lifetime penalty on top.
If you have an HSA, stop contributing at least 6 months before Medicare starts, because Part A can reach back 6 months and any money you put in during those months loses its tax break, with a 6% penalty each year until it is fixed. Medigap has a 6-month window to buy with no health questions; miss it and a company can turn you down later.
Born in 1960 means you are the first whose full retirement age is exactly 67, in 2027. The 2026 earnings test is $24,480 with $1 withheld per $2; in your full-retirement-age year the limit jumps to $65,160 with $1 per $3, and only pre-birthday months count. Money withheld comes back to you later. A spousal benefit claimed at 62 is cut 35%, not 30%. Part D out-of-pocket maximum rises from $2,100 to $2,400, so check your plan by Dec. 7.
💡 Tip: Marketplace subsidies count your Social Security income. Claiming at 62 can push you over the cliff and cost more than the check brings in.
A two-birth-year couple needs one shared timeline
Two birth years in one household means two rulebooks running on the same calendar. Picture a husband born in 1954 and a wife born in 1962. He's in the first RMD group; she isn't close. That gap is common, and it's exactly where careful planning earns its keep.
Start with his required withdrawal. Born in 1954, his first RMD year is 2027, and on a $400,000 IRA that's roughly $15,100 pulled into income whether he needs the cash or not. She turns 65 the same year, which opens her seven-month Medicare window. Two separate deadlines, one tax return, and the tax return is where they collide: his extra income can raise their joint income enough to shrink her senior deduction or trigger a Part B surcharge.
There's a catch in the claiming side too. If he claimed at 62 and she's the lower earner, her spousal benefit stopped growing once she hit full retirement age, and it can't start until he files. The same claiming age calculation shapes every couple's decision, and most people get the arithmetic wrong. Her own waiting does nothing for that piece.
Put every date on one shared calendar: his RMD, her Medicare enrollment, Part D selections, and both tax-return deadlines. Run the numbers on a QCD before December: his gift counts toward the RMD and keeps the income off the return, which protects her deduction rather than blowing past it.
Then weigh survivor protection against claiming patience. If the higher earner is older and in poor health, delaying his claim may matter more than the RMD timing. If the lower earner is still working, the spousal benefit may already be frozen, so waiting buys nothing. Check both years' returns before moving a dollar.
One shared timeline beats two separate strategies every time.
Frequently Asked Questions
I was born on January 1. Which birth-year group am I in?
Social Security treats you as born the year before. A January 1, 1960 birthday makes you a 1959 baby, with a full retirement age of 66 years and 10 months, not 67. The same rule applies to any birth on the 1st of a month—it counts as the previous month.
My husband claimed at 62. What survivor benefit will I get?
It's capped at the larger of what he was actually receiving or 82.5% of his full amount. If his full benefit was $2,400 and he claimed at 62 for about $1,800, you get $1,980—$420 less than the full amount. Ask for the computation in writing.
Do I have to take my first RMD in 2027 if I was born in 1954?
Yes, 2027 is your first required year. You can delay the first withdrawal to April 1, 2028, but then you'll take two withdrawals in 2028—about $31,000 on a $400,000 IRA if the first is about $15,100. For most people, taking it in 2027 is cleaner. Ask a tax preparer to run both years.
Does Cobra count as health coverage after 65?
No. Cobra and retiree coverage do not count when it comes to Medicare enrollment. When your job ends, you have 8 months to sign up for Part B. Miss it and you pay a 10% penalty on your premium for life. Call Social Security before you rely on Cobra.
Will the senior deduction still be around in 2027?
Under current law, the $6,000-per-person senior deduction runs from 2025 through 2028. That's up to $6,000 for a single filer or $12,000 for a couple. It phases out above $75,000 single or $150,000 couple. Born in 1962? You get it for 2027 and 2028. Born in 1963? Only 2028. Born in 1964–66? None, unless Congress extends it.
What each birth year should do before January 2027
Group one, born 1950 or earlier: get the survivor computation in writing and use qualified charitable distributions from your IRA to keep income under the senior-deduction line. Group two, born in 1954: decide whether your first RMD is taken in 2027 or stacks up in 2028—take 2027 unless a preparer shows you otherwise.
Group three, born 1955–59: if you're the lower earner, stop waiting on a spousal benefit that has already stopped growing. Group four, born in 1962: calendar your Medicare window today and call Social Security about Part B before you rely on Cobra.
Every group: check your Part D drug plan before December 7. The out-of-pocket max rises to $2,400, and plan formularies change in January. Your birth year already sorted you into a group. What you do with its rules before 2027 is still up to you.
Got two birth years in one house?
Scroll back to the shared timeline section and write both dates on one calendar. That single step prevents the tax and Medicare mistakes that cost couples the most.

Hello there! I’m Jesse Joe, the author and editor behind SolganGenius. I’m thrilled you’ve stopped by, and I can’t wait to share with you the essence of what this platform is all about.
I’m a writer, social media enthusiast, and a firm believer in the power of words. I’ve always been fascinated by how a simple phrase or slogan can capture an emotion, convey a message, and even change perspectives. Learn More