If you're collecting Social Security and still working, the 2026 earnings limit is probably the rule you're most worried about. Here's the short version: before full retirement age, you can earn up to $24,480 in 2026 without losing any benefits.
But cross that line and the Social Security Administration withholds $1 in benefits for every $2 you earn over it. In the calendar year you reach full retirement age, the limit jumps to $65,160 and the withholding softens to $1 for every $3. After full retirement age? No limit at all.
The questions start right after the numbers. Does joint income count? What happens to the money they withhold? How do they actually take it back? And the one that trips up almost everyone: what counts as earnings in the first place?
This article walks through all of it in plain English, with the 2026 figures and a few worked examples. By the end you'll know exactly where you stand and what to do before a check stops.
Quick Tips Before You Start
Know your FRA
Full retirement age is 66 if you were born in 1954 or earlier, and 67 if you were born in 1960 or later.
Count only earned income
Wages and net self-employment profit count. Pensions, IRA withdrawals, and investment income do not.
Report expected earnings
File a work report with the SSA if you think you'll go over. It's better than waiting for an overpayment letter.
Use the monthly test in year one
If you retire mid-year, the monthly limit ($2,040 or $5,430) can help you keep benefits in that first year.
Check benefits on your record
If you have excess earnings, benefits paid to a spouse or child on your record may also be withheld.
1. This Test Hits Retirement Benefits, Not SSI or Disability
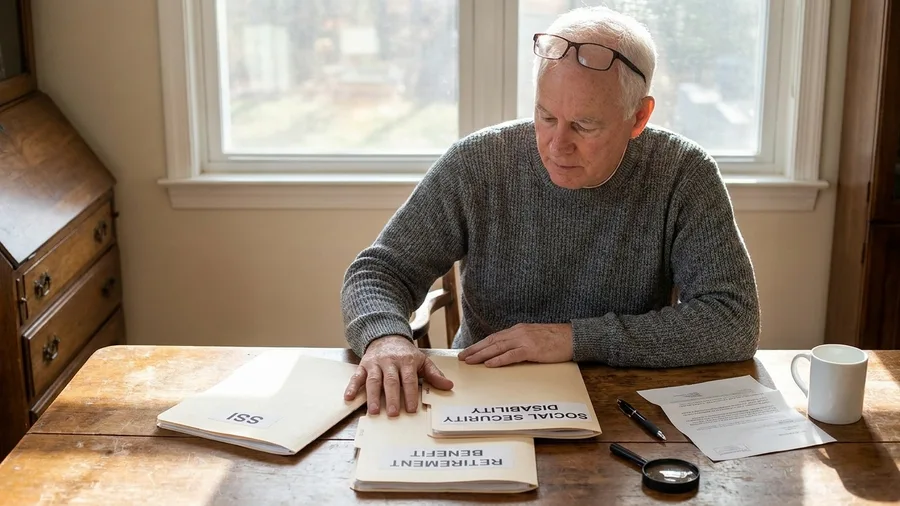
Those 2026 numbers you just saw have a specific address, and it isn't every benefit check the government sends out. The earnings test belongs to Social Security retirement benefits, and it only bites before you reach full retirement age.
That distinction matters more than it sounds. SSI and Social Security disability have their own eligibility rules, and those rules are usually stricter, with income cutoffs that sit well below the retirement limit. The retirement earnings test was built for a narrow situation: someone claimed their retirement benefit early, then went back to work. SSI and disability are judged on entirely different grounds, so the $24,480 figure is not your number to plan around if you're on either of those.
Here's the part that makes people relax. Once you reach full retirement age, the earnings limit disappears. You can earn any amount and keep every dollar of your benefit. No withholding, no work report, no monthly math.
So if you're past FRA, you can close this page. If you're not, or you're helping a spouse or friend who isn't, keep going, because the next thing to pin down is exactly when your own FRA lands.
💡 Tip: Check your benefit statement or the SSA website to confirm whether you're receiving retirement, SSI, or disability benefits. They're not interchangeable.
| Situation | 2026 annual limit | Withholding rate | Monthly equivalent |
|---|---|---|---|
| Under full retirement age | $24,480 | $1 for every $2 over | $2,040 |
| Year you reach full retirement age | $65,160 | $1 for every $3 over | $5,430 |
| After full retirement age | No limit | None | None |
2. Full Retirement Age Moves With Your Birth Year
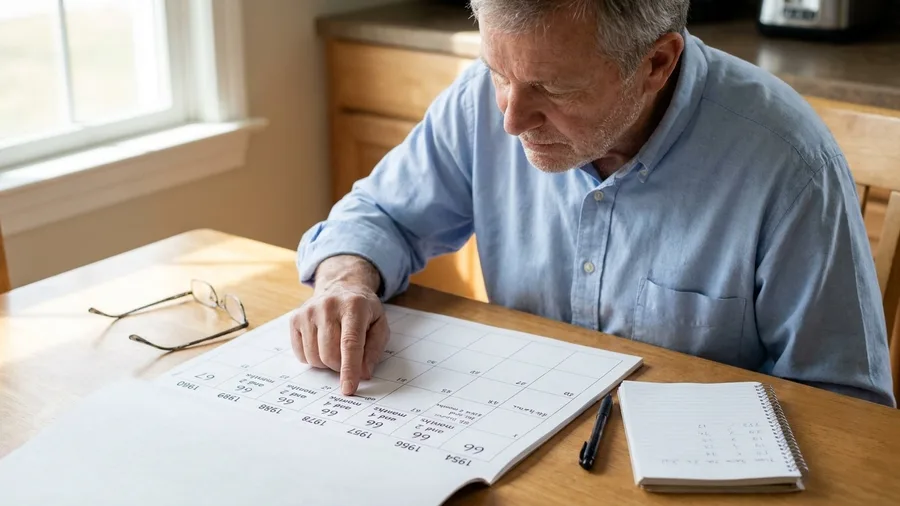
Unlike the programs we just set aside, this rule doesn't treat everyone the same. Your full retirement age comes down to your birth year.
Born in 1954 or earlier, and your FRA is 66. Born in 1955, it's 66 and 2 months, and it climbs by two months for each birth year after that. Anyone born in 1960 or later lands at 67 under current law, and that's where it's scheduled to stay.
Find your birth year, match it to the schedule, and you've got the line that decides which limit applies to you and when the limit stops entirely.
3. The 2026 Limit Is $24,480 Before FRA
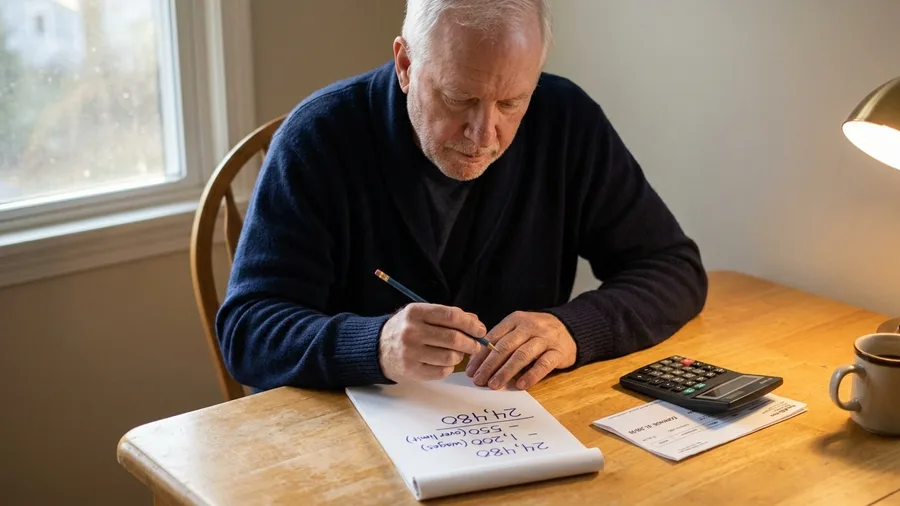
For 2026, if you're under full retirement age, you can earn up to $24,480 without losing a cent of benefits. Cross that line and Social Security withholds $1 in benefits for every $2 you earn above it.
Run the math on a real number. Say your countable wages come to $30,000. That's $5,520 over the limit, so about $2,760 gets held back. You still collect most of your benefit, but a chunk is gone.
Only countable earned income feeds this calculation, and there's a full breakdown coming on what counts. Pensions, IRA withdrawals, dividends and interest don't touch it. Neither does this limit once you're past FRA.
💡 Tip: Use the SSA's earnings test calculator online to run your own numbers before you report.
💡 PRO TIP
Pro Tip: Check Your FRA Year
The higher $65,160 limit only applies in the calendar year you reach full retirement age, not the year before. Mark your FRA year on the calendar now so you don't miss it.
4. In Your FRA Year the Limit Jumps to $65,160
Which is why the year you actually reach full retirement age gets its own, far friendlier set of numbers. For 2026, that year's limit is $65,160, and the withholding softens to $1 for every $3 you go over.
It's a huge jump from $24,480, but it applies only in that one calendar year, not a full twelve months beforehand. The year before you hit FRA, you're still under the lower limit. Earn $70,000 in your FRA year and you're $4,840 over, so roughly $1,613 gets withheld.
Once you pass FRA, the limit vanishes completely. So if you're close, think about timing: shifting a bonus or a big project into your FRA year can save you some withholding.
5. The Earnings Test Is Individual, Not Joint
No. The earnings test is individual, not joint. Each person's earnings are measured separately, so a spouse pulling in well over the limit won't touch your benefit as long as your own earnings stay under it.
There's a catch, though. If anyone else collects on your work record, like a spouse or a child, your excess earnings can affect what they receive. That's a separate issue from your own check, and it's worth checking before you assume everyone's safe.
One carve-out to file away: an ex-spouse's excess earnings don't affect your benefit, and yours don't affect an ex-spouse's benefit drawn from your record.
6. Withheld Benefits Can Come Back Through ARF
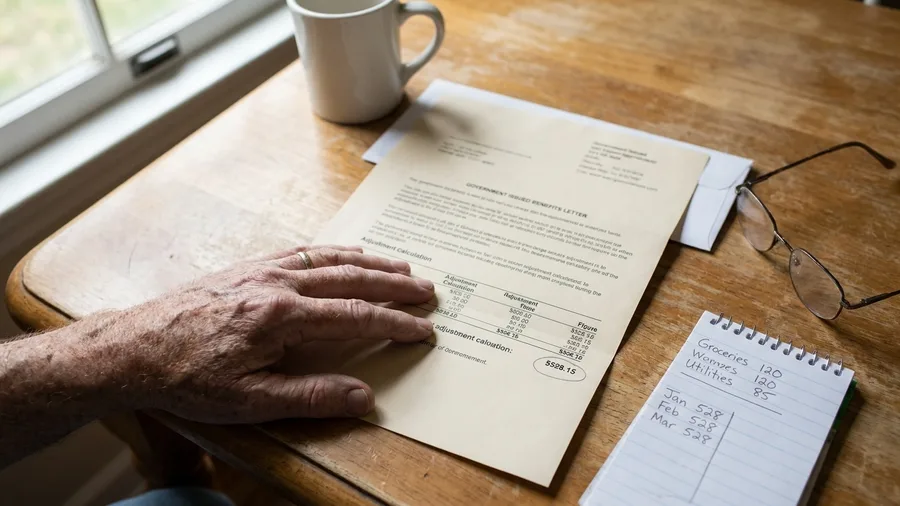
Picture your first Social Security deposit after full retirement age arriving, and it's a little bigger than you expected. That's not a mistake. It's the adjustment to the reduction factor, or ARF, and it exists because the money withheld by the earnings test isn't gone for good.
When you claim early, your benefit is permanently reduced. For the first 36 months before FRA, the cut is 5/9 of 1% per month; beyond that, 5/12 of 1% per month. Roughly, each month early shaves about half a percent off your check.
Here's the part that surprises people: any month where no benefit was paid because you earned too much doesn't count against you. At full retirement age, SSA adds that reduction back in.
Say you claimed 24 months early, so your benefit carries about a 12% reduction. If six months of checks were withheld along the way, you'd get roughly 3 percentage points back at FRA. Small, but permanent.
💡 Tip: Keep a record of which months you didn't receive a check. It'll help the SSA apply the ARF correctly.
💵 How the Earnings Limit Withholding Works
You exceed the limit
The SSA calculates how much you earned over the limit.
They calculate withholding
They apply the $1-for-$2 or $1-for-$3 rate to the overage.
They withhold entire monthly checks
No partial checks—they hold back full monthly benefit amounts until the debt is covered.
Checks resume
Once the overage is recovered, your benefits start again.
7. SSA Withholds Whole Checks Until Overage Is Recovered
That ARF adjustment only matters because SSA actually takes the money back first, and it does it in a way that can catch you off guard. There's no gentle trim off each check. The agency withholds entire monthly payments until the overage is recovered.
Here's the math. Say your monthly benefit is $2,000 and you finish the year $10,000 over the limit. At the $1-for-$2 rate, $5,000 gets withheld, which is two and a half months of checks. SSA might hold January, February and March, then start paying again in April.
So the hit isn't spread out. It lands in a lump, and for those months your benefit income is simply zero. If rent, groceries and prescriptions depend on that deposit, March gets uncomfortable fast.
The catch is that nobody warns you beforehand. SSA works from what it knows, and unless you report your expected earnings, the withholding can start without a letter you'd notice. If you know you'll cross the limit, budget the missing months now, before the checks stop. People born before nineteen seventy should also review urgent Social Security warnings for mistakes that follow you for years.
💡 Tip: Set aside some of your earnings to cover the months without a benefit check.
8. Report Expected Earnings Before SSA Finds Out
Waiting for SSA to catch up is the opposite of what you want, even though it feels easier than picking up the phone. If you expect to earn above the limit, file a work report and tell SSA what you think you'll make.
You can do it through your online account, by phone, or at a local office. Ask which form or online update is right for your case, and bring your estimated earnings for the year. That estimate is what SSA uses to start withholding if it needs to.
Reporting may trigger withholding sooner, but it beats an overpayment letter landing four or five years later. Keep a copy and update SSA if your estimate changes a lot.
💡 Tip: Ask the SSA which work report form or online update applies to your situation—it can vary.
⚠️ COMMON MISTAKE
Common Mistake: Ignoring an Overpayment Letter
If the SSA says you were overpaid, don't ignore it. Contact them right away, ask for the calculation, and discuss repayment options. Waiting can make the balance grow.
9. A Monthly Test Can Help in Your First Year
The work-report path assumes a clean year, but the first year you claim is rarely clean. Retire in September after a full year of wages and the annual test looks brutal, because your income already blew past the annual limit before you ever claimed. This is where the monthly test saves you.
The monthly limit is simply the annual limit divided by 12. For 2026, that's $2,040 under the $24,480 limit, or $5,430 under the $65,160 limit.
The monthly test applies in that first calendar year if you have at least one month where you earn under the monthly limit and aren't self-employed in that month. It runs for the rest of that year; after that, the annual test takes over.
Say you earned $40,000 through August and stopped. Your annual total exceeds the limit, but September through December count month by month, and if you stay under $2,040 in those months, you keep every check. It's not automatic; ask SSA to apply it. Then a new calendar year means back to the annual test.
Retire mid-year and it's worth asking directly whether the monthly test covers you.
💡 Tip: Self-employed? The monthly test works differently. Check with the SSA before relying on it.
Report Your Earnings vs. Wait and See
Report to SSA
- Avoids surprise overpayment letters
- Lets you plan cash flow
- Shows good faith
- May start withholding sooner, but you're in control
Wait and See
- Risk of overpayment years later
- Possible penalties or interest
- Less time to adjust your budget
- More stressful in the long run
10. Your Overage Can Suspend Benefits on Your Record
It can, and that's the part people miss.
If you have excess earnings, benefits paid to others on your record get withheld too, including a current spouse or a child drawing on your work history. The SSA withholds from what your record pays out, not just your own check.
There's one real exception: an ex-spouse's benefit from your record is not affected by your excess earnings, and your benefit from an ex-spouse's record is insulated from theirs. So a remarried couple where the current spouse collects on the worker's record should plan for that check pausing too.
11. Only Wages and Net Self-Employment Count
You're filling out the earnings report, and the line asking for your income sits there blank. Then comes the question: does the pension from the old job go in that box? Does the dividend check?
The SSA only counts gross wages from a job and net earnings from self-employment. That's the whole list. Pensions, most annuities, IRA and 401(k) distributions, dividends, interest, and capital gains stay out of it, which matters because a year of heavy investment income can look big on your tax return and still leave your benefits untouched.
If you're self-employed the number is net profit after ordinary and necessary business expenses, not the gross receipts on your invoices. There's a wrinkle here, too. The SSA has special rules for time you spend working in the business, especially in that first year, so run the details past them or a tax preparer before you settle on a figure.
Getting this wrong is easy, and it is expensive. Keep clean records through the year and check with the SSA before you report anything, so the number they receive is one you can back up.
💡 Tip: If you have both wages and self-employment income, add them together to see if you're over the limit.
What Happens If You Already Got the Money
The envelope shows up in a year you weren't thinking about Social Security at all. Four or five years after the fact, a letter says you were overpaid.
That doesn't mean a rule changed overnight. It means the SSA has finally matched your earnings record to the benefits you were paid, and the difference has to be settled. A $10,000 overage at the $1-for-$2 rate leaves $5,000 of benefits you weren't owed, and if those checks already landed in your account, the agency will want them back or a way to recover them.
Contact the SSA promptly once the notice arrives and ask for the calculation they used. Then find out what your options are for repayment or for disputing the figure if you think it's wrong. Ignoring the letter doesn't make the problem smaller, it only lets the balance sit there and grow.
This is where good records pay you back. Bring your earnings paperwork and the work report you estimated, so the SSA can reconcile the year in one conversation instead of three.
The sooner you open that envelope and call, the more choices you'll still have.
Should You Delay Claiming While You Work
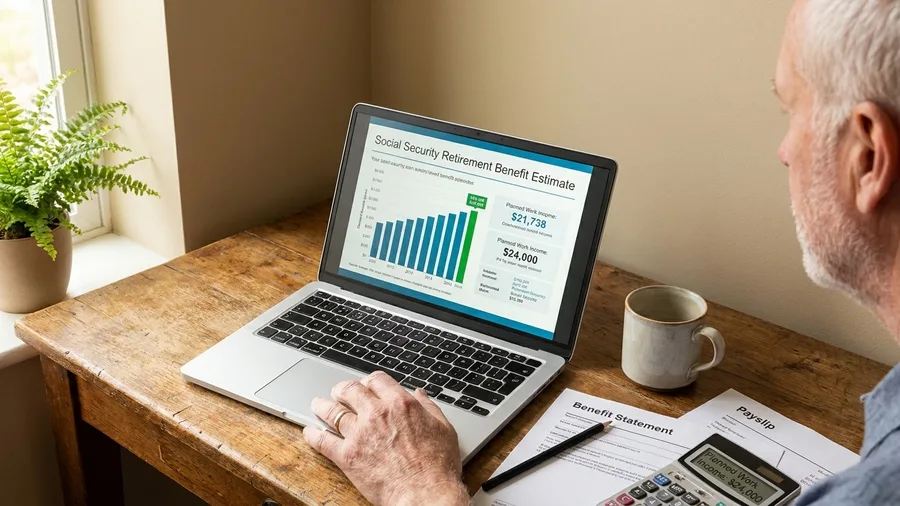
Now flip it around. What if you haven't claimed at all yet, and you're still working? The decision in front of you isn't about withholding, it's about timing.
Claim before FRA and you're inside the earnings test: possible withholding now, and a later adjustment that adds those months back to your record. Wait until FRA or later and there is no earnings limit at all, so a good salary costs you nothing in benefits.
Start with your SSA benefit estimate and your expected work income, then work out whether withholding would leave you short of the bills. A $2,000 monthly benefit is $24,000 a year, and if the limit held back $5,000 of that, you'd feel it. If you need the cash now, claiming early may simply be necessary, and there's no shame in that.
If you expect high earnings and can afford to wait, though, waiting can make your first working years a lot simpler to manage. Withheld benefits do come back through the adjustment at FRA, but they aren't much comfort in the month the check doesn't arrive. If returning to work is part of your plan, read going back to work at seventy for warnings about what it costs.
Honest question to answer: do you need the money now, or do you expect high earnings and have room to delay? Whichever way it goes, check your own estimate on ssa.gov before you decide.
Frequently Asked Questions
Does the 2026 earnings limit apply to my SSI or disability benefits?
No. The limits apply to Social Security retirement benefits before full retirement age. SSI and Social Security disability benefits have their own separate rules, often stricter, so check those programs directly.
What is my full retirement age for Social Security?
It depends on your birth year. Born in 1954 or earlier: 66. Born in 1955: 66 and 2 months. It rises by two months each year until 1960, when it reaches 67.
How much can I earn in 2026 before Social Security withholds benefits?
If you're under full retirement age, you can earn up to $24,480. In the year you reach full retirement age, the limit is $65,160. After full retirement age, there is no limit.
Does my spouse's income count toward my Social Security earnings limit?
No, the earnings test is individual. Each person's earnings are tested separately. Your spouse's excess earnings won't affect your own benefit from your work record.
Are withheld Social Security benefits gone forever?
No. At full retirement age, the SSA adjusts your benefit to add back the reduction for months you didn't receive a benefit due to the earnings limit. This is called the adjustment to the reduction factor (ARF).
Your 2026 Earnings Limit Game Plan
Start by checking your birth year to find your full retirement age. That tells you which limit applies: $24,480 if you're under FRA, $65,160 in the year you reach it, and no limit after.
Then count only your earned income—wages and net self-employment profit. Add them up and estimate how much you'll be over the limit, if at all.
If you expect to go over, file a work report with the SSA right away. It's better than waiting for an overpayment letter years down the road.
And if you're in your first year of benefits, remember the monthly test might help you keep more checks. When in doubt, confirm your own case with the SSA—every situation is a little different.
Check Your Earnings Limit Now
Grab your latest pay stub and your SSA benefit statement. Run the numbers against $24,480 and $65,160 so you know exactly where you stand before you report.

Hello there! I’m Jesse Joe, the author and editor behind SolganGenius. I’m thrilled you’ve stopped by, and I can’t wait to share with you the essence of what this platform is all about.
I’m a writer, social media enthusiast, and a firm believer in the power of words. I’ve always been fascinated by how a simple phrase or slogan can capture an emotion, convey a message, and even change perspectives. Learn More