The April mortgage statement arrives with the same $1,150 due, and the Social Security deposit that covered part of it last month was his, not yours.
Two quotes sit in front of the same 64-year-old woman: $1,420 a month on her own record, $1,940 as his survivor. Nothing on either page says which to take, or in what order, and no third piece of paper settles it.
The check is not the first decision. What gets filed first, and what comes back in writing, is. The gap between a March death and a July application is where money quietly disappears.
Her fixed costs do not pause while a claim processes: $2,540 a month against a survivor check that has not yet cleared the earnings test or withholding.
By the end there is an order to follow. The death report that files nothing, the one call that screens every benefit, the six documents, both quotes at more than one age, and a paper trail that holds up when a letter or a move arrives. That is the whole of the work, and it fits in a folder.
Quick Tips Before You Start
One Folder, Everything
Death certificate, marriage certificate, his W-2, your photo ID, a bank statement, and a copy of every SSA notice you receive.
Write the Questions First
List what you want screened before you dial, so the call does not end with three questions still unasked.
Log Every Call
Representative's name, date, and what was promised, written down the same day.
Ask for It in Writing
Any estimate, determination or overpayment explanation can be mailed to you. Request it before you agree to anything.
Nothing Is Final
A choice made at 64 can be revisited. The paper trail is what makes revisiting possible.
The First Weeks: Death, Documents, and the Claim
Three things happen in the first month and they are easy to confuse: the death gets reported, the record gets frozen, and a survivor claim gets opened. Only one of those is yours to do.
Get this part in order and everything after it runs on a record instead of on memory.
1. The Funeral Home Reports the Death, Not Your Claim
Make the call yourself, and make it before the thank-you notes are written. The funeral director does notify Social Security. That notification matters, and it only does one job: it stops the monthly payment that was going to your husband and updates the record to show he has died. It stops nothing else.
It is a record, not a filing. Nothing in that notification opens a survivor application, and no one at the funeral home will tell you that, because it's not their part of the process. The application in your name does not exist until you call and a representative opens it with your claim date on it.
I have watched a widow sit for five weeks thinking she was done. She had handed over the death certificates at the funeral home in March, heard the words "we take care of Social Security for you," and went home to answer casseroles and cards. No one called her. No paper came. When she finally dialed in April, the representative said the survivor application had never been started, and the March payment was already being pulled back. Five weeks, and the claim date had not moved an inch.
That is the cost of the misunderstanding. Not a penalty exactly, but a clock that never started while she believed it had. Every week the application sits unopened is a week the process behind it does not run, and the money you are counting on waits behind the whole queue.
Have these at the table when you dial, because the call moves fast and you do not want to be digging: the death certificate, your marriage certificate, both Social Security numbers, your photo ID, and the bank information for direct deposit. Set them in one stack before you pick up the phone.
The first words out of your mouth can be plain. Tell the representative your husband has died, give the date, and say you want to open a survivor benefit application in your own name. Ask them to confirm the claim date they are using.
Then write that date on the top document in the stack. That is the paper that counts for you, the one SSA opens on your call, and it exists only because you made it.
💡 Tip: Before you call, write down the date of the death and the date of the marriage. Those two dates drive everything the representative types into the record.
| Quote | Her own retirement | Survivor benefit |
|---|---|---|
| Monthly amount at 64 | $1,420 | $1,940 |
| Monthly amount at full retirement age | $1,860 | Not yet requested — ask for it in writing |
| Difference between the two at 64 | $520 a month in the survivor's favor | |
| Fixed monthly costs | $2,540 | |
| Gap left by the survivor check | $600 a month |
2. Ask SSA to Screen All Benefits in One Call
You will not lose anything by asking too much on this call, and you will not sound greedy or confused. The only real risk is making the call with nothing written down and hanging up with nothing to hold.
Spend ten minutes before you dial. A note card with four items on it is enough: the survivor benefit that runs monthly, anything owed to a child on his record, the one-time death payment, and a Medicare question. Then, on the call, have the representative read each item back and give the next step for that item alone before moving to the next. One benefit finished before the next one starts.
Write down the representative's name and the date at the top of the card, and ask for a written confirmation of what you were told before the call ends. Everything lives on one record: the $1,940 survivor figure, a possible death payment, and the Medicare answer. Call twice and you get a second representative and a second version of the file. A name, a date and a letter back are what let you hold them to it at the kitchen table.
3. Missing Documents Delay the Claim More Than Missing Answers
The belief worth killing is that a slow claim is a hard claim you argued badly. Most delays are a missing certificate. A claim stalls on paper, not on answers.
Build the folder before the call. One system that works is a single manila folder with a printed index page in the front and a slot beside each line. The slots: death certificate, marriage certificate, birth certificate, his W-2 or her self-employment return, one bank statement, her photo ID. Lay it flat where the mail lands and leave it there.
The dates of the marriage and the death decide which month the claim can begin, and a date given from memory becomes a second call and a later start. If the marriage certificate had come out of the box in May instead of June, the July filing would not have been shoved into August, and the first check would not have slid with it. Each notice that comes back goes in the same folder. It is the only asset in this process that costs nothing and protects everything.
What to Do Now, Soon, and Not Yet
- 📞 Call Social Security and open the survivor application — Nothing else in this article works until that application exists in your name.
- 📄 Assemble the certificate set and his W-2 — Missing paperwork delays the claim more than any missing answer.
- 🗂️ Start the notice folder with copies of everything you send — Later letters get answered from this folder.
- ✍️ Sign a claim based on one quote — Wait until both your retirement quote and the survivor quote are on paper.
- 🔢 Budget from the survivor check alone — Request the survivor quote at full retirement age before you fix the monthly number.
- 🚫 Agree to a repayment on the phone — Ask for the overpayment explanation in writing first.
Two Checks, One Decision: Your Own vs. Survivor
You are not choosing between two versions of one benefit. You are holding two separate quotes at the same age, each with its own starting rules, and the comparison is only as good as the paper it is written on.
Do not sign either one until both numbers exist in writing and both are dated.
4. Own Retirement and Survivor Check Are Separate Decisions
A friend of mine pulled up both figures on her kitchen table and set them side by side, dollar signs facing each other like a fight card, and she sat there for twenty minutes before touching her coffee. Her own record at 64 pays $1,420. His survivor benefit at that same age pays $1,940. Five hundred twenty dollars a month is the difference, and she had no third piece of paper telling her which one to file or which to file first.
Each benefit carries its own rules about when it starts and what it pays at each age, which is why the gap is not the whole story. The larger number looks obvious until the question underneath it gets asked. So put the question to a representative exactly that way: can I switch from one to the other later, and what would each choice pay at my current age?
No claim gets filed until both numbers are in writing, and right now the comparison is half a page. Her survivor quote at 64 is on paper; her survivor quote at full retirement age has never been requested. Until that second figure is in hand, she is weighing a finished number against a blank space.
And the rules that decide her case belong to her age, her work record and her marital status, which means the official SSA survivors page or an actual representative, not a forum thread about what a friend of a friend was told. A neighbor's answer is not a determination. Neither is one that arrived in a comment section at eleven at night.
Two quotes, both written, both dated, both in the folder before a signature goes anywhere. If it is not written down, it is not a number yet.
💡 Tip: Ask for each quote by age: at 64, at full retirement age, and at 70. Three ages, three numbers, one sheet of paper.
💡 PRO TIP
Get the Quote, Not the Explanation
A representative can read you a dollar figure for any claiming age and mail it to you. Ask for the number at 64, at full retirement age and at 70, then put all of it in the folder. A percentage on a phone call cannot be budgeted.
5. Starting Age Changes the Check You Keep for Life
The waiting is the part that eats at her, because doing nothing feels like letting the cushion thin out one month at a time while the paperwork sits. Here is the size of that waiting on her own record: $1,420 a month at 64, and $1,860 at full retirement age. That is $440 more every month, before a single survivor dollar enters the conversation.
Her survivor side of that comparison is still missing. The $1,940 at 64 is written down; the survivor quote at full retirement age was never asked for. Ask for it in dollars, to sit beside the $1,940, so both ages can be read against each other on the same page.
Then set the difference against the gap she actually lives with. Fixed costs run $2,540 a month and the survivor check covers $1,940, which leaves $600 short. The $440 gain on her own record would close most of it.
But here is the trade you have to see before you wait. Put the question in months rather than percentages: at the higher amount, how many months does it take to earn back what she gives up by holding off, and what does she pull from savings while she waits for the raise to start? A percentage over the phone cannot go on a budget. A dollar figure at each age can, and it prints out.
Claim Now vs. Wait for the Higher Check
Claim at 64
- $1,940 a month starts immediately on the survivor side
- Covers most of the $2,540 fixed costs right away
- Less strain on savings in the months before part-time pay arrives
- The lower amount is locked in for life
- Nothing left to draw down while you wait
Wait for Full Retirement Age
- A larger survivor quote, in writing, before you decide anything
- $440 more per month on her own record at full retirement age
- The gap between check and costs shrinks, or closes
- Requires drawing from savings in the meantime
- Worth pricing in months, not percentages
6. A Part-Time Paycheck Can Change the Benefit — Tell SSA
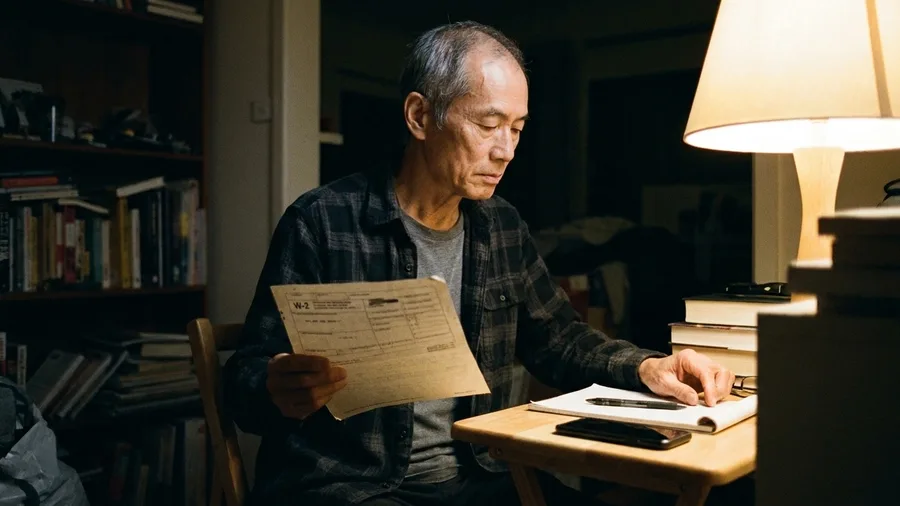
$31,000 a year. That is what her part-time bookkeeping brings in, and every arithmetic page in that folder quietly assumes the check arrives at the advertised amount.
It might not, and that is the honest cost of keeping the job. Social Security applies an earnings test to money earned above an annual limit before full retirement age, and the test runs on her actual figure: the $31,000 from bookkeeping, not a vague question about whether working affects anything. What it can do is lower or hold back part of a check, and it can do it before she has adjusted a single line of her budget.
So the job is still worth keeping, and the paperwork should say so. Bring last year's W-2 and this year's expected earnings to the call or the office, so the estimate comes off real numbers instead of a guess. Then ask for the overpayment rule in writing before accepting the first check: what happens if the estimate comes out high, and how would any excess come back out?
That last piece is the one that catches people. The $1,940 on the quote and the $1,940 that lands in the bank are two different amounts until her earnings figure is on the record, in writing, in a form someone can point to.
If a letter ever says she was overpaid, the move is calm: call the number printed on the letter, keep the letter in the folder with every other notice, and ask for the explanation in writing before agreeing to send anything back. A repayment arranged from memory is an amount that never gets checked.
Keep the job. Keep the W-2. Ask what the income does before it does it. The estimate exists to be reviewed, not guessed.
The Survivor Check in Practice — At a Glance
💵 Monthly quote at 64
$1,940
🏠 Fixed monthly costs
$2,540
📉 Monthly gap
$600
💼 Part-time pay
$31,000/yr
⏱️ First check arrived
September, two months after filing
📄 Quote at full retirement age
Not yet requested
The number that matters
Until the earnings figure is on the record in writing, the quote and the deposit are two different numbers.
Living on the New Number: Budget, Taxes, and Changes
Once the claim exists, the work shifts from paperwork to arithmetic. The check is smaller than his paycheck was, the first one arrives later than you expect, and both of those facts hit the same month.
Build the budget on the number that actually lands, then keep it updated as each new written estimate arrives.
7. Budget the Gap the Survivor Check Leaves
The fix for a check that comes up short is one sheet of paper, filled in by hand, dated at the top.
You already know roughly what will land and roughly when. Now pencil it against what leaves every month: $1,940 in, and $2,540 out – mortgage $1,150, utilities and insurance $480, groceries $420, car $310, medications $180. The subtraction is the whole exercise. It leaves $600 that has to come from somewhere else, month after month, and seeing it once in your own handwriting is different from carrying a vague worry around the kitchen.
Do not try to close all $600 this week. Start with a number small enough to be embarrassing: $40 off the grocery line, which is one store-brand swap and one fewer delivery order. That is not the solution, and it is not meant to be. It is proof the gap can be moved at all, which is the part that gets hard to believe at 2am.
The lag is what the small number is really buying time against. Filed in July, paid in September, with the bookkeeping pay also not arriving until September – two months run on savings alone, so anything you shave off groceries in July has to be set aside, not spent, or it never reaches the gap.
Write the date next to the total. When the quote for your own age at full retirement age comes back, you add one line and see exactly what changed from which starting point. Edit the grocery figure down a little each month. The sheet is not a verdict, it is a running record.
Where the $2,540 Goes Each Month
Cut from groceries and the car first. Leave the mortgage, medications and insurance alone.
8. Taxes Do Not Stop at the Funeral — Check Withholding
Maybe, and your part-time pay is what decides it.
Social Security becomes partly taxable once your combined income crosses a threshold set by the IRS – combined income being your adjusted gross income, plus any tax-free interest, plus half the benefit. At $31,000 from the bookkeeping, you are near or over the line, which means the answer depends on the pay figure, not the benefit. Two women drawing $1,940 can owe different amounts. The threshold and the rate come from the IRS page on Social Security benefits, not from a neighbor's return.
The reframe is that withholding is a decision you make on paper, not a bill that surprises you in April. Either file the SSA withholding form so tax comes out of the check, or set a standing transfer to savings each month and leave it alone. Pick one, put the date on it, and the question is closed for the year.
Four Places the Paperwork Goes Wrong
9. Remarriage, a Move, or New Work Reopens the Decision
Put a date on the calendar to pull the folder out, and put a second date on it for whenever life changes shape.
The tax election holds only while circumstances hold. A move, a remarriage, a new job, a retirement – each one can reopen a decision you thought was finished. No remarriage age rule is quoted here, because the answer depends on your age, your work and your marital status; verify it on the SSA survivors page or at a local office before you set a wedding date or sign a lease.
The folder is what makes that possible. Award letter, application date, every SSA notice in the order they arrived – that stack answers an eligibility question faster than memory can, and in the words SSA itself used. When something changes, request a fresh written determination. Do not assume the check carries on unchanged just because no letter arrived to say otherwise.
Once a year, sit down with the file and ask the same question you asked in the first week: what is in writing, and what is in the folder. If a notice is missing or a determination is stale, that is the item for next week.
The choice made at 64 was never meant to be permanent. What makes it changeable is the paper trail, kept current, so a letter or a move lands on a file that already has an answer in it.
Frequently Asked Questions
If the funeral home already told Social Security, do I still have to apply?
Yes. The funeral director's notification stops the monthly payment to your husband and updates the record, but it does not open a survivor application. You call and a representative opens one in your name with your own claim date. Ask for confirmation of that application in writing before you hang up.
Should I take my own Social Security or my husband's survivor benefit first?
Get both quotes in writing at the same age first, then ask the representative plainly: can I switch later, and what would each choice pay at my current age? In the typical case the two quotes at 64 were $1,420 and $1,940 a month — $520 apart — and the survivor quote at full retirement age had not even been requested. Sign nothing until both pages exist.
Will my part-time job reduce the survivor benefit?
The earnings test applies to your actual pay, so the answer depends on the figure. Bring last year's W-2 and this year's expected earnings — in the example, $31,000 from part-time bookkeeping — and ask for the estimate on those numbers. Request the overpayment rule in writing before you agree to any repayment.
How long does it take to get the first survivor check?
Longer than the month you file in. In the typical case the claim was filed in July and paid in September, so two months ran on reserves. Plan the budget for that gap before the first deposit arrives, and cut from groceries and the car rather than the mortgage, medications or insurance.
Will I owe tax on the survivor benefit?
Part of it may be taxable depending on your total income, and your part-time pay is usually what pushes total income over the line. Check the current thresholds on the IRS page for Social Security benefits, then see a tax preparer before your first April with the award letter and your withholding election in hand.
Do I lose the survivor benefit if I remarry?
The rules depend on your age, your work history and your marital status, so check the official SSA survivors page for your situation and confirm at a local office before any date is set. Nothing decided at 64 is permanent, but the award letter and notices in your folder are what make a later change possible.
Before You Sign Either Claim, Get Both Numbers on Paper
Nothing gets signed until both numbers exist on paper. The funeral home's report files no claim. One screening call covers survivor benefits, children's benefits, the death payment and Medicare. Six documents go in the folder. Both quotes come back in writing at more than one age. The $31,000 gets reported, the $600 gap gets budgeted, withholding gets elected, and every change earns a new written determination.
Two pieces of paper are still on the table: $1,420 on your own record at 64, $1,940 as his survivor. Neither number moved. The question did. It is no longer which check is bigger; it is which claim to file first, and what has to be in your hand when you do.
This week, call Social Security before either claim is filed. Ask for both estimates in writing and use the official survivors page to check the rules for your age, your work history and your marital status. When the April statement lands, the only thing due on it is the mortgage, and you will know exactly which check covers it.
Make the Call Before You File
Ask for both benefit estimates in writing at three ages, get the next step for each item on your list, and put the confirmation in the folder.

Hello there! I’m Jesse Joe, the author and editor behind SolganGenius. I’m thrilled you’ve stopped by, and I can’t wait to share with you the essence of what this platform is all about.
I’m a writer, social media enthusiast, and a firm believer in the power of words. I’ve always been fascinated by how a simple phrase or slogan can capture an emotion, convey a message, and even change perspectives. Learn More